Nigeria’s electronic invoicing requirements are changing how affected businesses create, validate and exchange invoices. The Nigeria Revenue Service (NRS) Merchant Buyer Solution (MBS), part of the Electronic Fiscal System (EFS), goes beyond generating a PDF or emailing a receipt. It involves structured transaction information, official taxpayer registration, validation and traceable invoice exchange.
For businesses preparing to register, accountants overseeing records and developers connecting their software, the essential questions are practical: where does a taxpayer register, what information must be supplied, how is an Invoice Reference Number (IRN) handled, and what must happen before an invoice can be described as validated? This guide uses official NRS documentation verified on 1 November 2026, while explaining which technical details remain dependent on the taxpayer’s approved integration route.
1. What is the NRS Merchant Buyer Solution?
MBS is the NRS platform supporting Nigeria’s phased e-invoicing and fiscalisation framework. It provides a method for taxpayers and authorised service providers to submit structured invoice details, obtain validation information and exchange electronic invoices. Its official resource centre describes both portal-based issuance and API-based workflows.
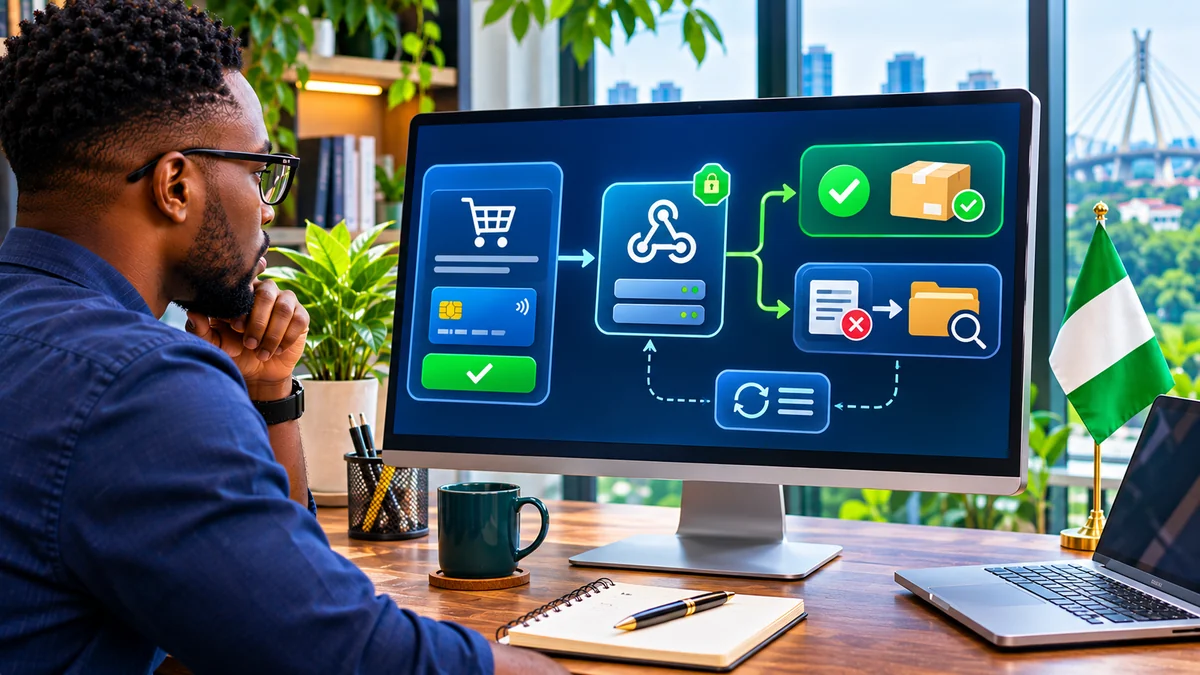
A PDF invoice generated by ordinary accounting software is not automatically an NRS-compliant fiscal invoice. The transaction must follow the requirements of the applicable taxpayer category and reporting route. Nor does a successful card payment through a payment gateway substitute for tax-invoice validation. Invoice creation, payment collection and eventual settlement are related but separate processes.
2. Which businesses should be registering in 2026?
The rollout follows NRS taxpayer bands. The February 2026 notice puts medium taxpayers, broadly ₦1 billion–₦5 billion in annual turnover, on an indicative 1 July 2026 go-live with review in October–November and enforcement indicated for January–March 2027. Emerging taxpayers below ₦1 billion have a planned 1 July 2027 go-live and enforcement window in early 2028. The February timetable itself says its future dates can change.
Large taxpayers were addressed first. A later July 2026 NRS announcement set 31 July 2026 as their full compliance deadline, superseding earlier enforcement timing. Some official notices refer to large taxpayers as above ₦5 billion, others as ₦5 billion or more; an entity on the threshold should confirm its category with NRS. The official rollout is not a universal 2026 enforcement deadline for every sole trader or SME. KPMG’s timeline summary provides the band-by-band phases.
3. Registering a business on the MBS portal
- Begin at the official MBS portal overview , not a link supplied by an unverified agent or message.
- Confirm the company’s registered legal identity, current Tax ID, tax-office records and contact email before opening or enabling the business profile.
- Follow the applicable sign-up or taxpayer-enablement steps, providing the requested business details. These can include sector, turnover, ERP details, reporting preference and invoice-exchange arrangement.
- Review the business profile, authorised users and NRS account access. Keep evidence of registration, enablement and correspondence.
- Choose an eligible method for issuing invoices: portal forms or batch upload, approved technology provider, or supported direct integration where the taxpayer qualifies.
- Complete any required onboarding checks and tests; do not treat creation of a login as evidence of completed fiscalisation.
The NRS onboarding guide distinguishes taxpayer enablement from the additional registration and service-level agreements required for System Integrators and Access Point Providers. Not every merchant must itself register as one of those service-provider types. The portal’s screens and requirements may change, so follow current instructions rather than relying on an old screenshot.
4. Know the difference between taxpayer, System Integrator and Access Point Provider
| Participant | Primary role | Key question |
|---|---|---|
| Taxpayer / business | Issues taxable-supply records and remains responsible for correct business data | Is this my correct legal entity and invoice? |
| System Integrator (SI) | Maps ERP/accounting fields and prepares compliant invoices and integration | Does the source system match NRS schema and signing rules? |
| Access Point Provider (APP) | Supports secure invoice exchange, transmission and acknowledgement | Did the invoice reach the required recipient(s)? |
The NRS System Integrator description includes ERP compatibility, UBL data mapping, cryptographic signing, key management and certificate processes. Its APP description addresses secure exchange between trading partners and the NRS. Verify a proposed vendor in the current NRS provider directory and assess its actual assigned role; claiming to support invoices or accounting does not alone establish accreditation.
5. Portal-based creation, batch uploads and API integration
The official NRS resources describe an MBS portal workflow that can create individual invoices using an online form or batch-upload multiple invoices using an NRS-provided Excel template. These methods can serve businesses whose existing systems are not directly connected, subject to their eligibility and the current portal functionality.
API integration is more relevant for companies with significant invoicing volume or existing ERP, POS and sales systems. The platform documents UBL-aligned XML and JSON; taxpayers may connect through authorised integration arrangements, and the November 2025 changelog describes eligible direct fiscalisation reporting using a taxpayer’s own API keys and a specified integrator service value. Do not assume that direct reporting or any one endpoint is available to every account without confirmation.
6. What information must an NRS e-invoice contain?
The NRS invoice schema describes mandatory and conditional fields. These include a registered BusinessID, IRN, IssueDate, InvoiceTypeCode, InvoiceKind, currency codes, supplier information, tax totals, monetary totals and invoice lines. Buyer fields and other references depend on the transaction scenario.
| Invoice information | What to verify |
|---|---|
| Business identity | Legal supplier details, current Tax ID and assigned business identifier |
| Invoice reference | Unique internal number, valid issue date and IRN procedure |
| Transaction type | Applicable B2B, B2C, B2G or G2B invoice kind |
| Line items | Quantity, accepted unit code, description and prices |
| Taxes | Correct tax categories and amounts for each supply |
| Financial totals | Tax-exclusive, tax-inclusive and payable amounts reconcile |
| Adjustments | Credit/debit notes, referenced documents and payment status |
The 13 July 2026 portal update says Tax ID replaces TIN as the legal identifier for businesses. Some versioned API examples still name a technical property Tin; developers must map the actual current Tax ID into the accepted schema rather than arbitrarily renaming keys. The portal also added standardised unit-of-measure codes and payment-status updates for instalments in April 2026.
7. How an Invoice Reference Number works
An IRN is a traceable reference in the invoice fiscalisation process. The NRS System Integrator IRN guide describes constructing one from the taxpayer’s internal invoice number, an NRS-assigned eight-character service ID and an invoice date in YYYYMMDD format. It gives an illustrative combination such as INV001-94ND90NR-20240611. A taxpayer must not invent the service ID or reuse the same invoice number for unrelated sales.
There is an important documentation distinction: the portal resources describe validated invoices receiving an IRN and validation details, while the SI technical workflow requires the calculated IRN in the validation payload. Treat these as different descriptions of the portal and integration lifecycle, not permission to claim that a locally calculated identifier proves successful NRS validation. Retain the actual platform confirmation and any official signed or verified result.
8. Invoice validation: The step that matters most
NRS validation checks whether invoice data matches required structure and business rules. Its versioned schema documents POST /api/v1/invoice/validate (with the configured base URL) for invoice content validation before subsequent signing and exchange procedures. The exact steps depend on the taxpayer’s reporting route and the current environment.
- Prepare the invoice from the approved business transaction, including correct parties, item lines and tax classifications.
- Check the mandatory values, accepted code lists, date formats and totals locally.
- Submit through the supported portal or integration method.
- Inspect any returned validation errors and correct source data through authorised workflows.
- Retain the validated reference, response, timestamps and any digital-signature or certificate evidence required by the route.
- Complete required reporting, transmission and recipient acknowledgement stages; do not equate a successful HTTP request with final exchange completion.
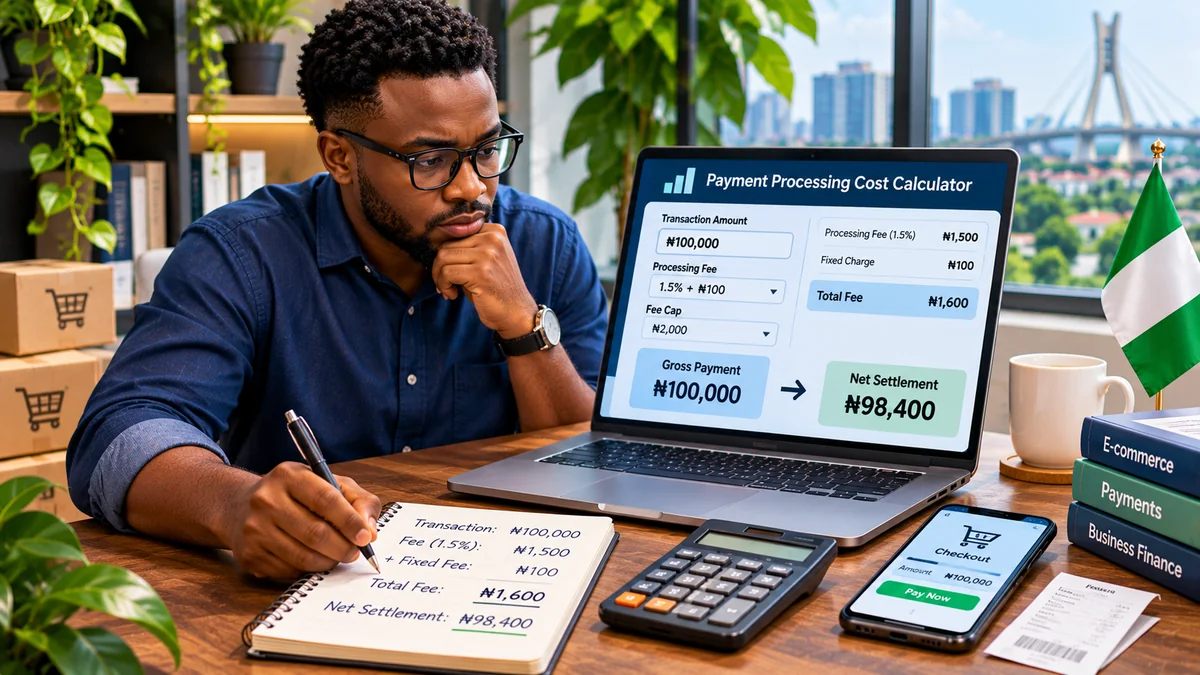
For example, a ₦100,000 taxable supply at an applicable 7.5% VAT rate would have ₦7,500 VAT and ₦107,500 tax-inclusive total before other adjustments. This is a calculation illustration only: not every Nigerian transaction is taxable at the standard rate. The NRS monetary-total documentation separates line amounts, tax-exclusive amounts, tax-inclusive amounts and payable amounts. A mismatch can trigger validation failure.
9. QR codes, digital signatures and authenticity
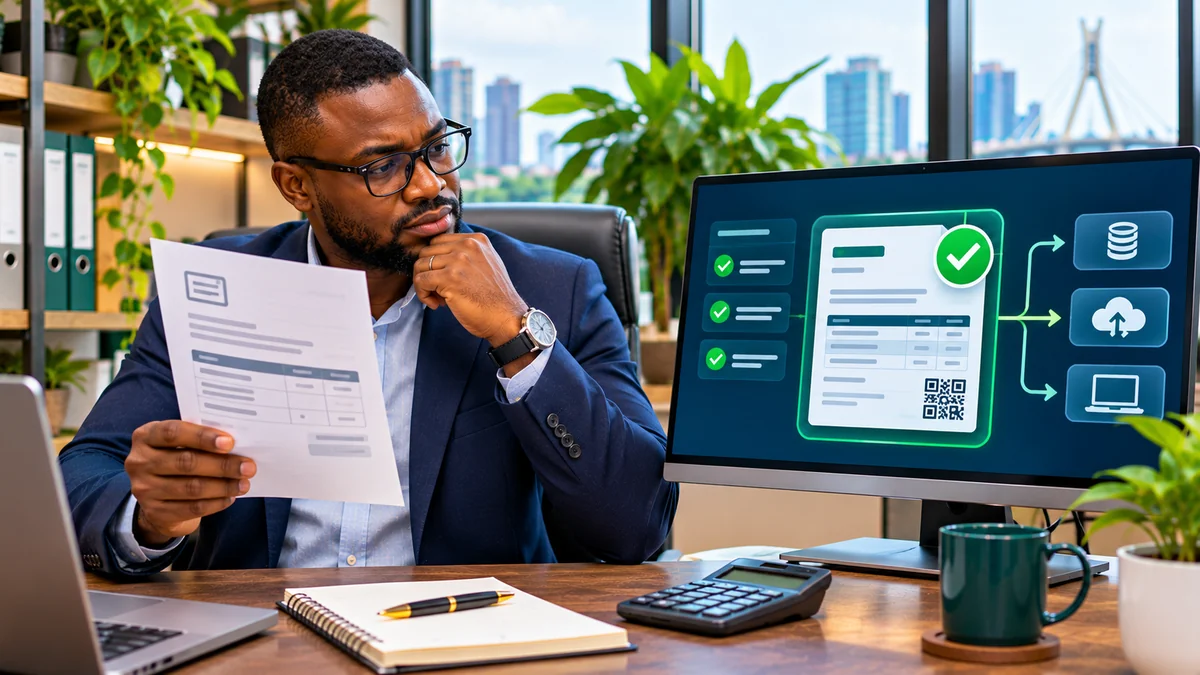
The NRS resource centre describes sharing a validated e-invoice with buyers, including a QR code used for verification. Its SI technical guidance also describes cryptographic stamps, ECDSA and signing controls for the relevant integration workflow. Technical teams must use the approved certificates and algorithms applicable to their chosen integration.
A decorative QR code on a PDF or an invoice number generated locally is not itself evidence of government validation. Businesses should verify invoice authenticity through the official process and preserve the relevant validation result. Signing keys, certificates and issued credentials need controlled storage, access limits and renewal procedures.
10. Transmitting and acknowledging invoices
Validation and transmission are not interchangeable. The APP invoice exchange documentation includes invoice lookup, transmission and receipt acknowledgement functions. It identifies statuses including TRANSMITTING, TRANSMITTED, ACKNOWLEDGED and FAILED. Receiver acknowledgement can be necessary before an invoice becomes completely transmitted.
In an ERP dashboard, show separate, honest states for issued, validated, awaiting exchange, acknowledged and failed invoices rather than displaying every submitted invoice as fully compliant. Handle webhook notifications durably and ensure a retry does not generate a second financial invoice. When there is a delay, reconcile with the provider or NRS status before resending.
11. Secure API access and reliable operations
The current NRS authentication guide documents x-api-key and x-api-secret for API requests. Credentials should remain server-side, never inside public frontend code, and HTTPS must be used. Some versioned guides reference other dashboard or token conventions; verify the precise authentication specification of the endpoint and API version used in production.
Production systems should implement input validation, unique invoice identifiers, access control, encrypted secret storage, monitoring, queue-based processing and immutable audit history where required. Track requests and responses without exposing sensitive data. Treat transport success, schema validation, signing, exchange and payment as separate stages, and test retries after connection failures.
12. What if an invoice is rejected, cancelled or paid in instalments?
The NRS portal resource explanation describes a rejection or cancellation window of 72 hours in certain portal workflows, with correction and resubmission. Do not interpret this as a universal right to cancel every invoice under all circumstances or as a blanket exemption from other statutory record requirements. Follow the case-specific workflow and current NRS rules.
For changes after issuance, use the appropriate credit note, debit note, adjustment or payment-status mechanism, retaining the original invoice history. The April 2026 NRS changelog added PARTIAL status for instalment and split-payment reporting. Invoice issuance and bank payment settlement must remain distinct: a card or transfer notification does not automatically change an invoice into an NRS-validated document.
13. What businesses should test before going live
- A standard B2B invoice with valid supplier and buyer identifiers; and a permitted B2C invoice scenario.
- Correct taxable, exempt or zero-rated classification under applicable law, with totals that reconcile.
- Invoice number uniqueness and the assigned service ID in IRN construction.
- Quantity and unit code validation, discounts, credit notes and partial-payment updates.
- Invalid Tax ID, missing data, rejected schema, failed signature or expired certificate scenarios.
- Network timeouts, repeated submission attempts, missing webhook notification and delayed acknowledgement.
- High-volume imports, batch submissions where permitted and multi-branch records attributed to the right legal taxpayer.
- Access privileges, audit logs, retrieval of submission evidence and secure handling of API credentials.
The NRS onboarding guide calls for sandbox testing, final integration review and production configuration. A test invoice that passes format validation does not alone prove a business has obtained every required approval or completed production registration.
14. Where do business software tools fit?
A management system can help keep invoices, sales, customer records, credit notes and reconciliation organised before formal fiscalisation. For hospitality operators, P-Biz Solutions’ hospitality accounting page describes receivables, payables, journals and reporting; its documentation covers billing and invoices. These are relevant operational capabilities to evaluate, **not evidence of accreditation or a live NRS MBS integration**. Request a technical demonstration and verified provider status before relying on it for compliance.
Where a business owner needs to plan the cost of new software, training or consultancy, KudiScope provides money tracking and budgeting across existing accounts. It can help with financial planning, but it does not provide an NRS fiscalisation service. Other sites should not be recommended as compliance or training providers unless a relevant, verified offering can be established.
15. A simple implementation plan for SMEs and larger organisations
| Phase | Action | Evidence |
|---|---|---|
| Readiness | Confirm taxpayer category, legal Tax ID and existing invoice workflow | Registration and scope records |
| Onboarding | Enable business profile and select permitted portal/API/provider route | NRS/provider confirmations |
| Data mapping | Match fields, invoice kinds, codes, amounts and IRN rules | Mapping and test cases |
| Validation | Test normal, error and correction scenarios | Actual validation responses |
| Exchange | Handle signatures, QR, transmission and acknowledgements as applicable | Transmission logs |
| Operations | Monitor, reconcile, train staff and respond to updates | Exception and audit reports |
A further internal resource is FlyingEze’s earlier report on the national e-invoicing initiative . Businesses still organising statutory records after incorporation can also consult the verified post-CAC registration guide . Two additional FlyingEze articles about the rollout timetable and preparing accounting software are currently draft/scheduled; their public URLs should only be linked after publication.
Frequently asked questions
Is MBS registration the same as complete e-invoicing compliance?
No. Registration creates or enables access, while compliance requires eligible invoices to follow the applicable reporting, validation and transmission process. Obtain evidence of the actual result.
Can a small business use the NRS portal without an ERP?
The NRS resource centre describes individual invoice creation and Excel batch upload via the portal. Check whether that route is available and appropriate for the taxpayer’s current phase and account.
Does an IRN automatically prove the invoice was validated?
No. SI documentation describes preparing an IRN as part of the submission workflow. Retain the actual official validation and reporting response; do not rely on a self-generated reference.
Must every Nigerian business use an approved third party?
Not necessarily. NRS describes portal-based, provider-assisted and eligible direct integration methods. The supported route depends on the taxpayer and the requirements in force.
Is a successful bank payment equivalent to NRS invoice validation?
No. A bank or gateway verifies payment collection; the NRS fiscal system validates and reports invoice data under a separate workflow.
Conclusion
The NRS Merchant Buyer Solution introduces a more structured way for Nigerian businesses to register, validate and exchange fiscal invoices. Getting it right means understanding taxpayer eligibility, registering with accurate business details, selecting the right connection method and tracking the entire invoice lifecycle.
Before declaring a system compliant, verify that the business has completed the required onboarding and that its invoices are correctly validated, transmitted and acknowledged where applicable. The goal is not simply a new invoice layout, but a reliable, auditable bridge between everyday commerce and national tax reporting.