For many Nigerian business owners, electronic invoicing simply means creating an invoice in Word, Excel or accounting software and emailing the resulting PDF to a customer. That is convenient, but it is not the same as the electronic fiscal invoicing being introduced by the Nigeria Revenue Service (NRS).
Nigeria's 2026 e-invoicing programme, known as the Merchant Buyer Solution (MBS), involves structured invoice information, an approved reporting route and NRS validation. A PDF is primarily a way to display or share an invoice. An NRS-compliant e-invoice is a record processed under the applicable fiscalisation framework. Importantly, a validated e-invoice can still be presented to a buyer as a PDF; the difference is the verifiable electronic record behind it.
This guide compares the two approaches, explains who needs to change and shows what business owners should ask their software vendors. Research verified 1 November 2026; taxpayer deadlines and technical requirements may be updated by NRS.
1. What is an ordinary PDF invoice?
A Portable Document Format (PDF) invoice is a document containing information about a commercial transaction. It may show the supplier's business name, customer details, invoice number, date, goods or services, tax where applicable, total payable and payment instructions. It can be produced from Microsoft Word, Excel, a POS terminal, an accounting package or an e-commerce system.
PDFs are useful: they preserve a readable layout, can be emailed or printed and often fit existing records workflows. They may remain appropriate commercial records for businesses not yet required to use the NRS fiscalisation system, subject to applicable invoice and record-keeping laws. But a PDF file alone does not show that the NRS has received, validated or accepted its underlying transaction data.
2. What is an NRS-compliant e-invoice?
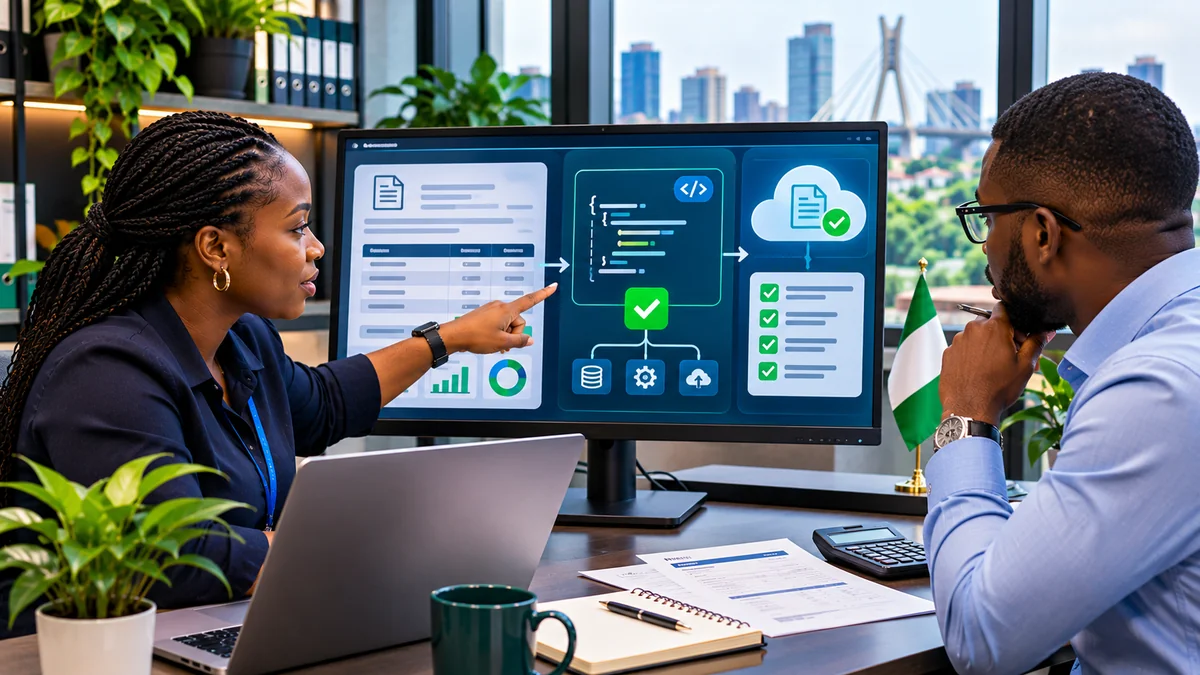
An NRS e-invoice is structured transaction data submitted and handled according to the relevant Merchant Buyer Solution / Electronic Fiscal System requirements. The official NRS e-invoice resource centre documents an MBS portal for individual invoice creation or Excel batch submission, alongside API-based exchanges using XML or JSON.
The NRS platform checks invoice information, reports validation errors and supports unique invoice references and verification details. The underlying rules are set out in its UBL-aligned invoice schema . The system also includes business enablement, technical signing or authentication where relevant, transmission and associated audit evidence. A merchant may still give a customer a human-readable or printable copy after the electronic record is processed.
3. PDF invoice vs e-invoice: The key differences
| Question | Ordinary PDF invoice | NRS fiscal e-invoice |
|---|---|---|
| Main purpose | Readable document or attachment | Structured fiscal transaction record |
| Format | PDF visual layout | NRS-prescribed data structure, including supported XML/JSON routes |
| Government validation | Not implied by file creation | Processed through applicable NRS validation/reporting route |
| Reference | Business invoice number | Business number plus applicable IRN/official validation details |
| Verification | Merchant's own records | Relevant NRS verification and audit records |
| Corrections | Often replaced or manually edited | Must follow permitted corrections, credit/debit-note processes |
| Customer copy | Usually PDF, email or print | May also be shown as a readable PDF/print representation |
The central misunderstanding is that e-invoicing does not describe what the finished invoice looks like; it describes how the underlying transaction information is structured, validated and managed. Putting a QR code, logo or 'tax invoice' label on an ordinary PDF does not, by itself, make it an NRS-validated record.
4. Why Nigeria introduced fiscal e-invoicing
Section 23 of the Nigeria Tax Administration Act, 2025 provides that, where NRS deploys an Electronic Fiscal System, persons making taxable supplies must use it to record and report supplies, maintain accurate records and follow the Service's transition arrangements. The aim is to support consistent fiscal reporting and a traceable record of transactions.
This statutory framework is not a statement that every trader was required to complete technical integration on 1 January 2026. The NRS has specified implementation phases by taxpayer segment. A company must check both whether its transactions fall within the legal requirements and whether its assigned rollout phase is currently in force.
5. Which businesses are affected in 2026?
| Segment | Indicative annual turnover | Published rollout position |
|---|---|---|
| Large | Generally over ₦5 billion | Revised full compliance deadline: 31 July 2026 |
| Medium | ₦1 billion–₦5 billion | 1 July 2026 go-live; projected enforcement Q1 2027 |
| Emerging | Below ₦1 billion | Planned July 2027 go-live; projected enforcement Q1 2028 |
The NRS February 2026 timetable, summarised by KPMG , identifies engagement, pilot, go-live, post-launch review and enforcement separately and describes future dates as indicative. The 19 July 2026 NRS notice subsequently extended the deadline for large taxpayers to 31 July. Some notices describe the large threshold as ₦5 billion and above; businesses exactly on the threshold should confirm classification.
A small business below ₦1 billion should not infer an immediate universal 2026 MBS enforcement deadline from the rollout headlines. Equally, a later e-invoicing phase is not a blanket exemption from existing tax, invoicing or bookkeeping obligations. Verify individual exemptions and taxable-supply treatment separately.
6. What happens to an invoice in the NRS workflow?
- The business records a legitimate sale or taxable supply in its POS, ERP, accounting system or eligible portal workflow.
- The required supplier, buyer, invoice, line-item, tax and amount fields are prepared according to the current NRS schema.
- The taxpayer submits the information through an authorised MBS portal, batch or integration route.
- NRS validation checks the information, and errors must be corrected through the permitted process.
- The invoice carries applicable NRS reference and verification details, such as an IRN and validation evidence.
- The business shares the validated invoice or an appropriate visual copy with the buyer and retains the required records.
- Where applicable, exchange, transmission or recipient acknowledgement steps are completed and recorded.
The NRS portal guidance describes near-real-time validation and sharing invoices with verification QR codes. But the System Integrator guidance describes constructing an IRN from the business invoice number, NRS-assigned service ID and issue date before a validation request. These are descriptions of different workflow stages: an IRN constructed locally is not standalone proof of acceptance. Preserve the actual platform response.
7. Does a PDF with an IRN or QR code count as an e-invoice?
Not automatically. A code printed on the invoice can be copied or fabricated, and a business can generate a visually convincing PDF without reporting anything to the NRS. For an affected taxpayer, the important evidence is the actual compliant fiscalisation process and verifiable invoice status.
On the other hand, a PDF exported from a properly validated fiscal record can be a convenient customer-facing copy. The business should retain the structured source data, relevant unique reference, validation response and transmission records, rather than keeping only the exported file.
8. What data does the e-invoice contain that an ordinary PDF may not capture reliably?
The NRS invoice schema describes fields such as BusinessID, IRN, IssueDate, InvoiceKind, supplier and buyer parties, invoice lines, tax totals and monetary totals. Some are mandatory; others depend on the transaction type. The schema also distinguishes B2B, B2C, B2G and G2B scenarios.
For example, an invoice may visually say '12 cartons' while the integration needs an accepted unit-of-measure code for the item. The NRS April 2026 update provided standardised unit codes, including EA for each and KGM for kilogram. Other changes allow PARTIAL payment status for instalment-based payments. Software must map the underlying sale correctly rather than guess values from text displayed on a PDF.
9. Example: Two invoices that look almost identical
Imagine a Nigerian wholesaler sells taxable goods worth ₦100,000. If the standard 7.5% VAT rate correctly applies, the illustrative tax amount is ₦7,500 and total payable ₦107,500. One version is prepared in a spreadsheet and saved as a PDF. Another uses the same valid transaction data but passes through the applicable NRS schema and validation process.
To the buyer, both might show the same supplier name, invoice number, line items, tax and grand total. The second, however, has associated structured submission and verification records. The difference is not the visual design or the arithmetic alone. It is whether the required digital fiscal reporting process has been completed. The example does not imply that every supply attracts 7.5% VAT; the correct classification depends on the transaction.
10. Does e-invoicing replace bookkeeping, receipts or bank statements?
No. E-invoicing strengthens the fiscal invoice record but does not by itself replace the general ledger, customer balances, bank statements, payment confirmations, stock movement or proof of service. Businesses should still record sales, receivables, refunds and actual money received. A successfully validated invoice can remain unpaid; likewise, a successful card or bank transfer does not automatically prove the invoice is validated.
A useful accounting system links the internal invoice, NRS validation details, customer payment reference and subsequent settlement without collapsing them into one generic 'complete' status. Keeping those events distinct supports better reconciliation and dispute resolution.
11. Can existing PDF invoicing software be upgraded?
Often it can, but this depends on the quality of its underlying data and whether a supported NRS integration route is available. A software vendor should demonstrate that the platform can produce the required invoice fields, calculate taxes correctly, preserve unique references, report corrections and maintain evidence of validation.
The NRS onboarding documentation explains the roles of System Integrators and Access Point Providers. The resource centre also describes individual portal issuance and Excel batch uploads for suitable workflows, alongside APIs for larger or technically integrated organisations. An existing PDF generator can remain as the output layer, but it cannot substitute for an official validation process.
12. Common mistakes when switching to e-invoicing
- Assuming email delivery automatically proves government validation.
- Using a generic PDF QR generator and labelling it 'NRS verified'.
- Applying standard VAT to all goods or services regardless of their actual tax category.
- Reusing invoice numbers when submissions are retried or records are corrected.
- Deleting original invoice history instead of recording appropriate credit or debit adjustments.
- Mistaking a payment gateway's success webhook for fiscal invoice acceptance.
- Storing only PDFs while discarding structured submission and validation evidence.
- Assuming software advertising an e-invoicing feature has official NRS accreditation.
The NRS technical changelog also announces changes to identifiers, invoice kinds, payment status and tax codes. Businesses should revisit vendor mapping when the documentation changes rather than preserve obsolete field assumptions.
13. What should a business owner ask an accounting software provider?
- Does the product support the current NRS Merchant Buyer Solution requirements for our taxpayer band and invoice scenarios?
- Can you show our own invoice information mapped into the official structured schema, rather than just exporting a PDF?
- Which registration, taxpayer enablement and provider approvals are needed?
- Does the software retain actual IRNs, validation responses, rejections and acknowledgement evidence?
- How does it handle cancelled invoices, credit notes, partial payments and corrections?
- What happens during internet outages, duplicated submissions or expired credentials?
- Who is responsible for updates when the NRS schema or regulatory timetable changes?
- What are the setup, licensing, integration and support costs, and how will our staff be trained?
Avoid buying a replacement accounting package solely on the strength of promotional claims. Request a documented demonstration and confirm provider status through the official NRS portal . Complete implementation needs operational, accounting and technical review.
14. Where do P-Biz Solutions and KudiScope fit?
Hospitality businesses preparing their underlying invoice and accounting records may evaluate P-Biz Solutions' hospitality accounting capabilities , including receivables, payables, journals and reconciliation. Its product documentation also describes billing, invoices and payments. These operational capabilities may help organise source records, but no official NRS MBS accreditation or live compliant fiscalisation integration has been independently verified. Ask for evidence before relying on it for statutory reporting.
Businesses budgeting software upgrades, professional assistance or staff training may use KudiScope's financial planning and budgeting tools to track planned expenditure. KudiScope does not hold customers' money and is not an NRS e-invoicing service. It should not be presented as a substitute for tax-compliant invoicing or professional advice.
15. A practical transition checklist
- Confirm the applicable NRS taxpayer category and latest compliance timetable.
- Audit the existing invoices, billing workflow and legally registered taxpayer details.
- Verify the current Tax ID; NRS announced the replacement of TIN terminology in July 2026.
- Clean item descriptions, tax codes, customer identities, quantities and invoice identifiers.
- Choose an eligible portal, batch or approved integration method.
- Test structured validation, reference generation, correction notes and error handling.
- Preserve proof of actual NRS acceptance and any required transmission/acknowledgement.
- Keep readable PDF invoices where useful, but generate them from accurate and, where required, validated records.
- Train accounting and customer-service teams on the difference between issued, validated, paid and settled.
- Reconcile periodically and monitor new NRS regulations, schema changes and rollout notices.
For business-registration and tax-record basics, FlyingEze's post-CAC registration guide explains why the Tax ID and organised bookkeeping matter. Its earlier e-invoicing report offers historical context. Additional current NRS guides on FlyingEze should be linked only once their public URLs are verified after publication.
Frequently asked questions
Is a PDF invoice illegal in Nigeria in 2026?
No blanket rule makes all PDFs illegal. The issue is whether an affected taxable supply must be processed through the NRS electronic fiscal system. A PDF may still be used as a readable copy, and businesses outside a current enforcement phase must still follow their applicable record and tax obligations.
Can a validated e-invoice be downloaded as a PDF?
A validated e-invoice can be shared in a human-readable representation, including where the supported workflow generates a PDF. Its legal/technical status comes from the underlying compliant validation process, not the file extension.
Does adding a QR code make a PDF NRS-compliant?
No. A self-generated QR code does not establish an NRS validation result. Verify the invoice using the official process and reference details.
Do all SMEs need to stop using PDF invoices immediately?
No. The NRS has adopted different rollout phases by taxpayer category. Smaller emerging taxpayers have a later planned implementation phase, while ordinary bookkeeping duties continue. Confirm any applicable exceptions or later NRS notices.
Do payment receipts and e-invoices mean the same thing?
No. A receipt or payment confirmation generally documents collection; a fiscal e-invoice records and reports the supply under the prescribed electronic invoice framework. The events may be linked but are not interchangeable.
Conclusion
The distinction between ordinary PDF invoices and Nigeria's new e-invoicing system is not whether an invoice is printed or emailed. It is whether the required structured transaction information has been submitted, validated and retained through the applicable NRS fiscalisation process.
Businesses do not necessarily need to abandon readable PDFs. They need to understand the legal phase that applies to them, preserve accurate source data and ensure that any required fiscal invoice has genuine validation evidence. Confirm your taxpayer category, test your software and treat official NRS guidance—not a logo or QR code on a document—as the foundation of compliance.