A freelance developer might receive payment from a Nigerian startup, a European agency and a global gig platform in the same month. A designer could pay for internet data, subscriptions and electricity from the same account used for groceries. When tax season arrives, the challenge is often not the tax form itself: it is proving what was earned, what was spent for work and what has already been deducted by clients.
This guide shows Nigerian freelancers how to organise their 2026 income and business expenses using the Nigeria Tax Act, 2025 and the Joint Revenue Board's 2026 Personal Income Tax Guidelines. Crucially, income earned from 1 January to 31 December 2026 generally belongs in the annual individual return due by 31 March 2027. A return filed during March 2026 ordinarily concerns the preceding 2025 basis period and should follow the government's transition rules. The figures below are illustrations, not personal tax advice.
1. Who is a freelancer for Nigerian income-tax purposes?
Freelancers—including writers, developers, consultants, video editors, designers, marketers, tutors and many content creators—commonly earn income from a trade, business, profession or vocation rather than exclusively through an employer's payroll. A self-employed individual's profits normally fall under the personal income-tax system. Where the freelancer operates through an incorporated company, the company's obligations may differ from those of the individual, and the two records must be kept distinct.
The Joint Revenue Board (JRB) Personal Income Tax Guidelines, 2026 expressly cover self-assessment returns, income from non-employment activities and content creators. Earnings from subscriptions, advertising, platform revenue sharing and endorsements may be taxable business income. A freelancer with a separate salaried job also needs to disclose relevant income from other sources.
2. Understand the 2026 tax year and the filing deadline
| Period | What it covers | Normal individual filing date |
|---|---|---|
| Return due in 2026 | Income from the preceding 2025 basis period; transition rules apply | 31 March 2026 |
| Income earned in 2026 | 1 January–31 December 2026 | 31 March 2027 |
Section 13 of the Nigeria Tax Administration Act, 2025 requires an annual individual return and, for business/professional income, an audited financial statement or a statement of accounts attested to by the taxpayer. The JRB's February 2026 guidelines specify submission by 31 March of the year of assessment for the previous basis period, generally even where no tax is payable.
The Federal Ministry of Finance's June 2026 transition guidance says the new Nigeria Tax Act operates from 1 January 2026 while returns relating to periods ending before that are governed by the previous rules. Do not apply the new 2026 brackets retroactively to an earlier 2025 tax calculation without proper transitional guidance.
3. Identify the right tax authority and Tax ID
For most resident self-employed individuals, filing is with the relevant State Internal Revenue Service where they are tax resident. The FCT Internal Revenue Service and NRS administer particular categories, including some residents or non-residents under statutory rules. The PwC administration summary describes this jurisdictional allocation; verify your actual residence and filing arrangement before selecting a portal.
Retrieve or confirm your individual Tax ID using the official NRS/JRB Tax ID portal . The platform links an individual to an existing NIN-based identity, while business entities use their registration details as applicable. Use the correct identity on invoices and tax returns; do not enter a company's tax identity when submitting the personal return of a sole proprietor without confirming the applicable filing arrangement.
4. Record all freelance income, not only bank deposits
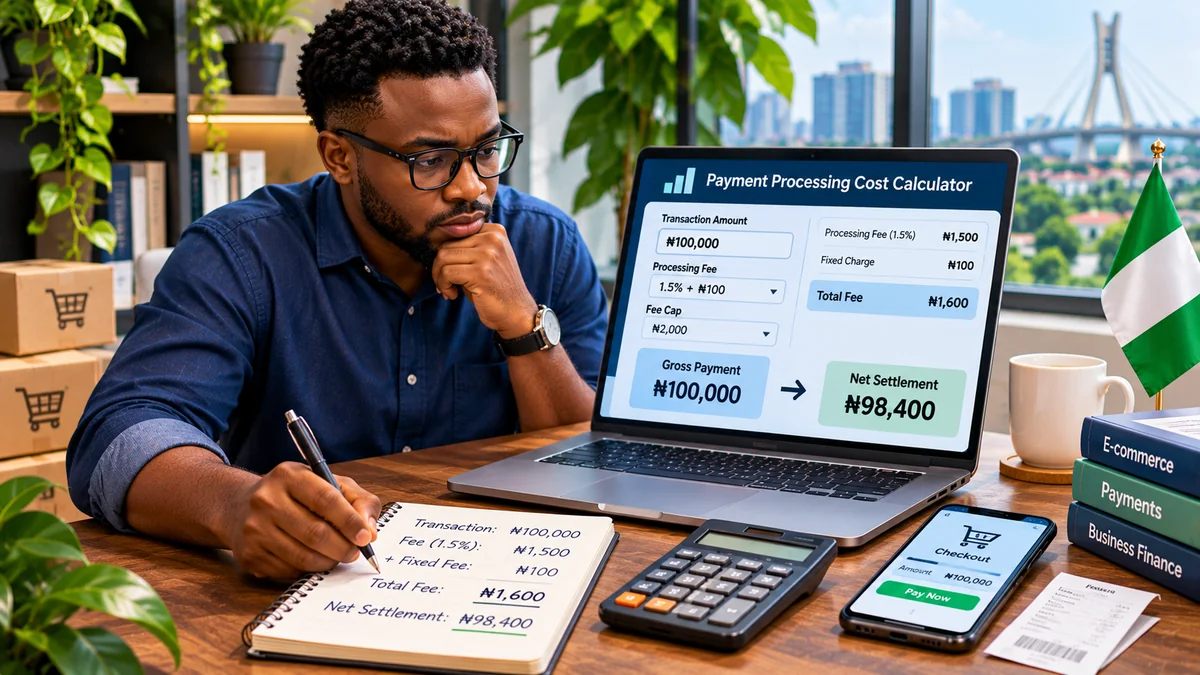
Create an income register for every client project, subscription, royalty or platform payment. Record the invoice number, client, service, contract currency, invoice date, gross amount, payment date, amount received, platform fees, withholding tax and supporting documents. Income for tax purposes is not necessarily identical to the sum of bank credits, especially where the client deducts tax or platforms net fees before payout.
| Field | Illustrative record |
|---|---|
| Invoice / client | INV-028 / Agency A |
| Service and date | Website maintenance / 15 June 2026 |
| Gross invoice | ₦250,000 |
| WHT deducted by client (illustrative) | ₦12,500 |
| Bank amount received | ₦237,500 |
| Support | Invoice, remittance advice, bank credit, WHT evidence |
The sample withholding amount is hypothetical, not a universal rate applicable to freelancers. The register preserves the ₦250,000 gross invoice separately from the ₦237,500 net receipt. Otherwise, deducting a tax credit may be mistaken for lost revenue and the annual figures may be understated.
5. Do not count transfers between your own accounts as new earnings
If you move ₦100,000 from one of your banks to a wallet, then from that wallet to another bank, you have not earned ₦200,000 in fresh client income. Mark internal transfers as transfers, and link the debit and credit. Similarly, distinguish legitimate loan proceeds, loan repayments, refunded purchases, asset disposals and personal gifts from ordinary freelance sales; their actual legal tax treatment must be assessed separately rather than automatically classifying every bank credit as taxable fees.
This matters when reconciling monthly statements. A well-designed tracking tool should let you classify business income, personal transfers and expenses without counting the same money twice.
6. Separate business expenses from personal spending
Section 20 of the Nigeria Tax Act, 2025 generally allows eligible expenses wholly and exclusively incurred to produce the income of a trade, business, profession or vocation. Personal and domestic spending should not be deducted simply because it came from a freelancer's bank account. Keep invoices, receipts, payment proof and a short explanation of the business purpose.
| Expense category | Evidence to preserve | Caution |
|---|---|---|
| Software subscriptions | Vendor invoice, payment record, work purpose | Separate personal entertainment tools |
| Internet and phone | Data receipts, usage basis | Claim only supportable business portion |
| Payment processing fees | Platform fee reports and receipts | Do not confuse withholding tax with a fee |
| Work-related travel | Transport receipts, client/project notes | Personal journeys are not business costs |
| Workspace | Rental agreement and relevant receipts | Mixed home use requires care |
| Contractor payments | Scope, invoice, proof of work and payment | Review withholding and reporting duties |
| Equipment | Purchase invoice and asset register | Laptops and other capital assets may need capital-allowance treatment |
An expensive laptop is not automatically a fully deductible operating expense in the month it is purchased. Capital expenditure and qualifying allowances are governed by separate rules. Where a phone, electricity supply or internet connection serves both work and personal life, use a reasonable, evidenced allocation and ask an adviser to check its tax treatment.
7. Keep personal reliefs separate from business expenses
Business costs and personal reliefs are different categories. The 2026 framework includes certain eligible deductions and a rent relief for qualifying individuals: 20% of eligible annual rent, capped at ₦500,000, subject to the required evidence and the taxpayer's circumstances. The old consolidated relief allowance is no longer the standard deduction under the new framework.
The JRB 2026 guidelines show the rent-relief calculation and discuss relevant landlord and property details. Do not automatically deduct the entire household rent as a business expense and then claim the same rent again without assessing the rules. Keep a separate schedule for personal reliefs, pension contributions and other eligible claims.
8. Organise overseas freelance income and FX conversion
Payments from overseas clients may arrive in dollars, pounds, euros or another currency before being converted to naira. Nigerian tax residents are generally assessed on worldwide income under the 2026 framework; simply leaving money in a foreign account does not automatically exempt it. Keep the foreign invoice, original currency amount, date, payment-platform statement, applicable exchange conversion and actual naira proceeds.
Document which exchange rate and accounting method were used, keep it consistent and confirm the tax authority's accepted basis. Do not confuse FX conversion fees with deductions of foreign tax. Where foreign tax was actually paid on income also taxed in Nigeria, a credit may be available within statutory limits and treaty conditions, but not merely because the client is overseas. See the PwC foreign-tax-credit guidance .
FlyingEze's guide to working for foreign companies and handling contracts and payments covers payment channels, invoices and cross-border terms in more detail.
9. Reconcile withholding tax instead of recording it as an expense
Some corporate clients withhold tax from eligible contractor or consulting payments and remit it to the relevant authority. Withholding is generally an advance tax collection mechanism rather than proof that all of the freelancer's annual obligations have been settled. Obtain the applicable deduction or credit evidence and match it to the gross invoice, client and period.
The JRB guidelines discuss withholding obligations on payments to non-employees. Applicable rates and exemptions depend on the transaction, payer status and relevant regulations; never assume every freelance invoice is subject to the same percentage. Keep a WHT-credit ledger separate from operating expenses. Where credits are admissible, they reduce the net assessed tax payable after computing the annual liability.
10. Use the 2026 individual income-tax bands correctly
| Annual chargeable income band | Rate |
|---|---|
| First ₦800,000 | 0% |
| Next ₦2,200,000 | 15% |
| Next ₦9,000,000 | 18% |
| Next ₦13,000,000 | 21% |
| Next ₦25,000,000 | 23% |
| Above ₦50,000,000 | 25% |
These bands appear in the Fourth Schedule to the Nigeria Tax Act, 2025 and the JRB 2026 guidelines. They are marginal rates applied to chargeable income after the relevant allowances and deductions, not a flat tax on all gross invoices. The first ₦800,000 band at 0% does not automatically eliminate the obligation to file. Avoid repeating online claims that every person earning above ₦800,000 pays 20% on their entire income.
11. Worked example: From ₦6 million revenue to an estimated tax figure
Consider a self-employed designer with ₦6,000,000 in gross 2026 service revenue and ₦1,800,000 in properly evidenced, deductible operating expenses. Ignoring other reliefs and adjustments, the illustrative chargeable income is ₦4,200,000.
| Calculation | Illustrative amount |
|---|---|
| Gross freelance revenue | ₦6,000,000 |
| Less eligible business expenses | −₦1,800,000 |
| Illustrative chargeable income | ₦4,200,000 |
| First ₦800,000 × 0% | ₦0 |
| Next ₦2,200,000 × 15% | ₦330,000 |
| Remaining ₦1,200,000 × 18% | ₦216,000 |
| Illustrative income tax before credits | ₦546,000 |
| Less assumed supported WHT credit | −₦100,000 |
| Illustrative balance | ₦446,000 |
This simplified example assumes an individual sole proprietor with all stated expenses allowable, no further reliefs, no different tax treatment, and ₦100,000 of valid WHT credits. It is not an actual assessment. Real liability depends on all income sources, documentation, capital allowances, eligible reliefs, tax residence, credits and the relevant authority's rules.
12. Build a monthly bookkeeping routine
- At month-end, export all bank, wallet, cash and freelance-platform transactions covering the month.
- Match each customer receipt to an invoice or other source and flag unexplained credits.
- Identify transfers between your own accounts and do not count them as new income.
- Tag expenses as business, personal or mixed, and preserve supporting documents.
- Reconcile platform fees, refunds, unpaid invoices and withholding credits.
- Check invoices issued but unpaid, and payments received for work not yet recorded.
- Update a monthly profit-and-loss summary and a separate tax/relief schedule.
- Back up the records securely and check that the cash, bank and invoice totals agree.
A spreadsheet can be sufficient if it is accurate and consistently maintained. A money-tracking application may make classification and duplicate detection easier, but must not be represented as a tax-filing product unless that capability is documented and supported.
13. Prepare the statement of accounts required for filing
The Nigeria Tax Administration Act and JRB guidelines contemplate an audited financial statement or an accounts statement attested to by the taxpayer where income arises from trade, business, profession or vocation. Ask the relevant authority which documents and filing format apply to your circumstances.
A year-end package might include an annual income register, expense summary, profit-and-loss statement, bank reconciliation, asset register, WHT-credit schedule, details of relevant reliefs and evidence of tax already paid. If you have employment income in addition to freelance projects, keep the relevant payslips and PAYE records and disclose all applicable sources.
14. How KudiScope or other business tools can help
For individuals using a mixture of bank accounts, wallets and cash, KudiScope documents transaction tracking, categorisation, duplicate review and the distinction between personal, business and mixed spending. These are useful for assembling financial records and recognising transfers that should not be double-counted. However, KudiScope does not hold the money, is not a bank, and has not been verified here as an official tax-filing platform or source of tax-deductibility decisions.
When a freelancer has a separate registered business or hospitality operation, an accounting or invoicing system may help provide more structured ledgers. Do not recommend enterprise software solely to file an individual's return. Choose tools based on genuine record-keeping needs and preserve exports and supporting documents so you can change products without losing the audit history.
15. Avoid these common freelancer filing mistakes
- Treating all credits to a bank account as new freelance income.
- Recording only the net amount after a client's withholding tax rather than the relevant gross fees.
- Claiming personal groceries, family transfers or unrelated household costs as business deductions.
- Writing off laptops or other capital purchases without checking the capital-allowance rules.
- Ignoring income earned on foreign platforms or assuming money left abroad is automatically exempt.
- Applying the new 2026 tax rates to a 2025 filing without checking the transition guidance.
- Assuming a zero tax calculation means no annual return is required.
- Failing to retain a statement of accounts and proof of withholding, payments or foreign taxes.
16. Practical year-end filing checklist
- Verify individual Tax ID and relevant state or FCT tax authority.
- Close and reconcile the 2026 income and expense registers at 31 December.
- Prepare the required accounts statement and separate deductible expenses from personal reliefs.
- Compute chargeable income using the correct year's legislation and progressive rates.
- Match valid WHT/PAYE and foreign-tax credits with official supporting evidence.
- Complete the authority's current self-assessment return and attach required schedules.
- Pay any balance due using official channels, retain confirmation and verify the filing status.
- Calendar the 31 March 2027 individual deadline and any business-specific obligations that differ.
For business-name registration and related obligations, FlyingEze's post-CAC registration checklist provides useful further context. This article concerns the individual freelancer's income-tax records; an incorporated company or employer can face separate corporate tax, PAYE, VAT or withholding obligations.
Frequently asked questions
If I earned freelance income in 2026, when do I normally file?
Under the JRB 2026 guidance, the annual individual return covering the preceding 2026 basis period is normally due by 31 March 2027. Returns filed in March 2026 generally concern the 2025 basis period and transitional rules.
Does the first ₦800,000 tax-free band mean I do not need to register or file?
Not automatically. The JRB guidelines require taxable persons to register and file an annual return whether or not tax is payable, subject to applicable legal and administrative arrangements.
Can I deduct my internet data, software and laptop?
Eligible work expenses may be deductible if properly substantiated. Mixed personal/work costs need supportable allocation; capital assets such as laptops can require capital-allowance treatment instead of an immediate operating-expense deduction.
Do foreign client payments count if I leave the money outside Nigeria?
Nigerian tax residents are generally subject to taxation on worldwide income, subject to exemptions and credits that must be assessed for the actual circumstances. Keep foreign invoices, payout statements and exchange records.
Can withholding tax deducted by a Nigerian client reduce my annual tax?
Where properly deducted, remitted and supported, eligible WHT can be credited against the appropriate final liability. It is not automatically a business expense or a substitute for filing.
Conclusion
Freelance tax preparation becomes easier when each transaction has a clear purpose and supporting document. The most important habit is to separate gross business income from net payouts, business expenses from personal spending, and tax credits from ordinary costs.
For the 2026 income year, organise records throughout the year, reconcile them at 31 December and prepare the required individual return ahead of the normal 31 March 2027 deadline. Accurate records support a defensible assessment, make errors easier to correct and help freelancers understand the true profitability of their work.