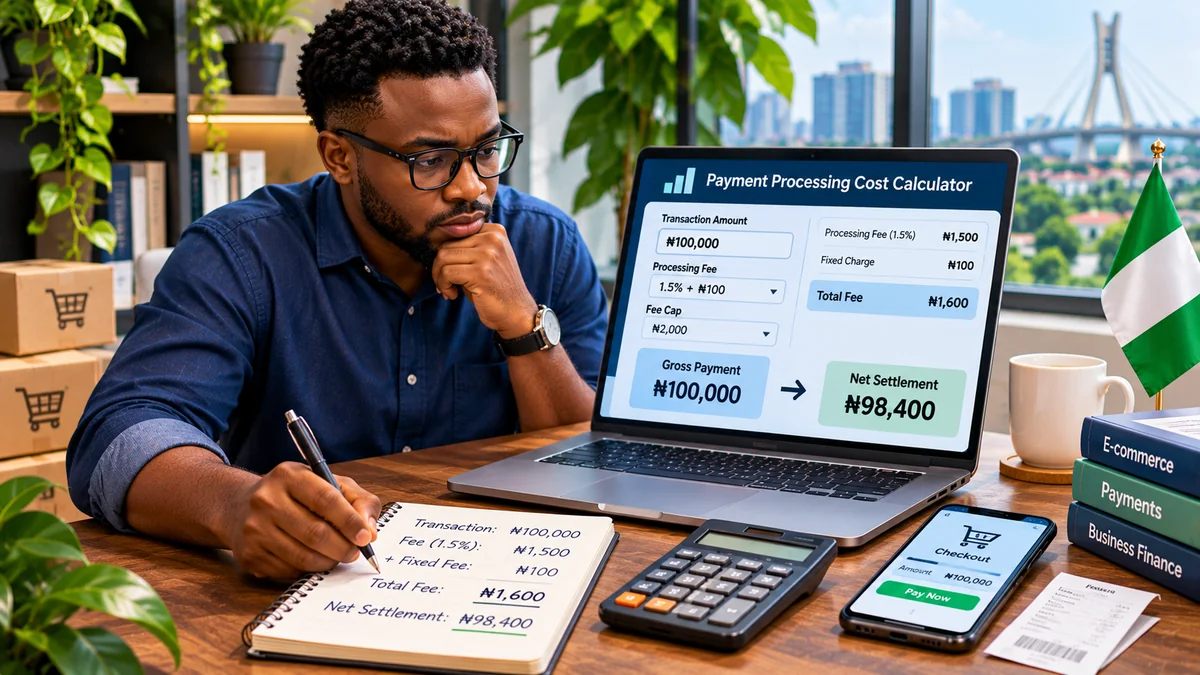
Accepting online payments is essential to many Nigerian businesses, but processing fees can quietly reduce profit. Whether a customer pays by card, bank transfer or USSD, the merchant needs to know the amount collected, the charges applied and the money actually available after settlement. A ₦100 charge looks small on one sale; across 1,000 sales it totals ₦100,000. Different channels, fee caps, payout charges, refunds and taxes can materially change the result.
This guide uses published Nigerian pricing from Paystack, Flutterwave and Monnify as checked on 1 November 2026. It explains how to estimate a single transaction, forecast monthly fees and reconcile the outcome. Provider terms may change, so the calculations are illustrations rather than quotations for a particular merchant.
1. What counts as a payment processing cost?
The full cost can include a percentage-based collection fee, a fixed charge, VAT on the provider's service where applicable, transfer/payout fees, legally required duties, currency conversion, refunds and dispute-related deductions. A card checkout fee may differ from a dedicated virtual-account or POS terminal fee at the same provider.
The Central Bank of Nigeria describes web transfers, POS, mobile and other channels in its payment modes overview . Merchants should distinguish the channel and product in each quotation. Also distinguish a charge on the provider's service from VAT, if applicable, on the goods or services the merchant sells.
2. The three basic fee calculations
Percentage fee
Multiply the payment amount by the published percentage. At 1.5%, ₦20,000 × 0.015 = ₦300 before other charges. A percentage may vary by country, card type or channel.
Fixed charge
A fee of 1.5% plus ₦100 gives (₦20,000 × 0.015) + ₦100 = ₦400. However, the fixed component may be waived for smaller payments, so do not add it blindly.
Fee cap
When the base fee is capped at ₦2,000, a calculated ₦3,100 base fee is reduced to ₦2,000. That does not necessarily cap separate taxes or disbursement charges. The practical formula is: base collection fee = min(rate × payment + applicable flat charge, provider cap), taking account of any waiver.
3. Published Nigeria collection fees: Paystack, Flutterwave and Monnify
| Provider / relevant product | Published standard local fee | Important qualifications |
|---|---|---|
| Paystack local checkout | 1.5% + ₦100; capped at ₦2,000 | ₦100 waived below ₦2,500 |
| Flutterwave Nigeria collections | 2% | 7.5% VAT applies to the stated processing fee |
| Monnify local cards/USSD | 1.5%; capped at ₦2,000 | Published prices are VAT-exclusive |
| Paystack dedicated virtual account | 1%; capped at ₦300 | Separate product and eligibility rules |
| Monnify bank transfers | 1.5% capped at ₦2,000 / ₦500 flat | Which alternative applies requires contract confirmation |
The rates are from official Paystack pricing , Flutterwave Nigeria pricing and Monnify pricing . Do not interpret the Monnify bank-transfer flat-fee option as universally available. Special pricing for educational institutions, large merchants and alternative products may also apply.
4. Calculate fees for a ₦100,000 online payment
Consider a successful ₦100,000 domestic card/checkout payment with the merchant bearing the processing fee. At Paystack, 1.5% of ₦100,000 is ₦1,500; adding ₦100 gives a ₦1,600 base fee and ₦98,400 before any further adjustments. Flutterwave's 2% base fee is ₦2,000; its published 7.5% VAT on the fee adds ₦150, leaving ₦97,850 in this simplified illustration. Monnify's 1.5% card base fee is ₦1,500, with its VAT-exclusive treatment requiring an additional tax check.
| On ₦100,000 | Base collection fee | Result before additional adjustments |
|---|---|---|
| Paystack checkout | ₦1,600 | ₦98,400 |
| Flutterwave | ₦2,000 | ₦98,000 before ₦150 fee VAT; ₦97,850 after |
| Monnify local card | ₦1,500 | ₦98,500 before applicable VAT |
The examples are not an exact prediction of a settlement batch. They exclude refunds, reserves, adjustments and any account-specific terms. Paystack's table uses its stated base local transaction charge; merchants should check their actual statement and invoice for applicable tax treatment.
5. Understand how fees change with payment size
| Payment amount | Paystack checkout base fee | Flutterwave base fee | Monnify local card base fee |
|---|---|---|---|
| ₦2,000 | ₦30 (no ₦100) | ₦40 | ₦30 |
| ₦10,000 | ₦250 | ₦200 | ₦150 |
| ₦100,000 | ₦1,600 | ₦2,000 | ₦1,500 |
| ₦200,000 | ₦2,000 (capped) | ₦4,000 | ₦2,000 (capped) |
The figures deliberately show base fees before applicable taxes. Caps mean the cheapest provider can change as the payment amount increases. At ₦10,000, a fixed ₦100 component makes a difference; at ₦200,000, a capped fee matters more. If most of your transactions are very small, fixed charges can be disproportionately expensive relative to gross revenue.
6. Model monthly fees, not only individual sales
Suppose a merchant processes 200 successful local payments of ₦10,000 each during a month. Gross sales collections would be ₦2 million. Under the illustrative standard base charges, Paystack fees would total 200 × ₦250 = ₦50,000; Flutterwave fees 200 × ₦200 = ₦40,000, or ₦43,000 including 7.5% VAT on those fees; and Monnify local-card base fees 200 × ₦150 = ₦30,000 before VAT.
This comparison holds the payment size and channel constant for clarity. Real merchants process a mixture of transaction values and channels, some of which fail or are refunded. A more reliable forecast calculates each transaction or each amount band separately, then adds provider fees, payout costs, tax on fees and exception handling.
7. Who pays the processing fee: Merchant or customer?
Some providers allow the merchant to absorb the charge or pass it to the buyer. Flutterwave's published Nigeria pricing says the default payer is the customer, with a dashboard option to change this. Paystack also provides a fee-passing option for eligible Nigerian merchants. That choice should be disclosed clearly at checkout and comply with applicable consumer rules and merchant terms.
A frequent error is assuming that adding the fee from the original price will leave the merchant whole. If a provider charges a percentage on the final amount paid, the extra fee is itself subject to processing charges. Paystack's fee-passing documentation describes a gross-up calculation for Nigeria-based merchants.
For an uncapped 1.5% + ₦100 transaction where the merchant must receive ₦100,000, a simplified gross-up is (₦100,000 + ₦100) ÷ (1 − 0.015) ≈ ₦101,624.37, before rounding rules and any separate applicable tax. Charging merely ₦101,600 would not fully offset a percentage fee applied to that higher amount. Use the provider's own fee-bearing feature and live checkout calculation rather than a hardcoded example.
8. VAT on payment fees is different from VAT on your sales
A processing provider's service fee and the underlying sale are not the same taxable transaction. Flutterwave explicitly states its transaction fees are subject to 7.5% VAT. Monnify states its displayed rates exclude VAT. Therefore, a 2% fee does not necessarily mean the merchant's total processing expense is exactly 2% of sales.
For example, a ₦2,000 processing fee with 7.5% VAT adds ₦150, giving a total service charge of ₦2,150. Whether the merchant may recover input VAT, and how VAT applies to the products being sold, depends on its tax circumstances. Businesses should keep provider invoices and obtain professional tax advice where needed rather than automatically treating all VAT as identical.
9. Add outgoing transfer fees and stamp duty
Collecting a customer payment and sending money out are separate events. For example, Paystack's Nigerian transfers pricing lists outgoing transfer fees of ₦10 up to ₦5,000, ₦25 for ₦5,001–₦50,000 and ₦50 above ₦50,000. Flutterwave publishes the same three transfer charge bands. Monnify has its own payout bands, published as ₦10 for less than ₦10,000, ₦20 at ₦10,000–₦49,999 and ₦40 at ₦50,000 and above, excluding VAT.
A separate statutory duty may apply. Paystack's September 2026 guidance states that ₦50 stamp duty applies from 18 February 2026 to qualifying merchant outflows of ₦10,000 or more, except approved payroll cases. Paystack explains this is distinct from the transfer service charge and that it does not levy this duty again on merchant inflows. Do not blindly add ₦50 stamp duty to every card checkout; track the exact liable transfer and payer.
For a merchant sending a ₦100,000 payout from an applicable Paystack balance, the illustrated cost is ₦50 transfer fee + ₦50 stamp duty = ₦100, aside from the principal. Ten qualifying payouts would therefore incur ₦1,000 in these charges, before any other applicable expenses.
10. International collections and currency conversion
International cards are commonly priced differently from local Nigerian cards. Paystack publishes 3.9% + ₦100 for supported international Visa, Mastercard and Verve payments, with different pricing for American Express. Flutterwave lists 4.8% for international transactions. Monnify lists 4%. The published amounts may exclude separate FX costs, VAT, settlement-currency differences and other terms.
Before using these percentages in a financial model, check where the customer is located, the card's origin, what currency the customer pays, what currency the provider settles and any exchange rates or charges. A Nigerian business earning in foreign currency but paying suppliers in naira has exchange-rate exposure beyond the gateway's advertised collection rate.
11. Refunds, chargebacks and other exceptional expenses
A returned order may leave the business with processing costs even when the customer's purchase is reversed. Paystack's refund guidance updated in October 2026 states that original transaction charges are non-refundable, and its refund eligibility window for new refund requests changed from 15 October 2026. Other providers' refund fee treatment must be checked independently.
Chargebacks can also reverse sale proceeds, trigger operational work and potentially lead to contractual fees or reserves. Businesses should track the payment, refund, dispute and final provider adjustment separately. Budget for a realistic refund and dispute rate using actual history, rather than assuming every processed payment permanently becomes revenue.
12. Reconcile gross collections to net settlement
An effective monthly payment report should track gross customer payments, fee deductions, processing-fee VAT, refunds, chargebacks, additional adjustments and actual net bank deposits. A successful transaction record is not proof that its exact gross amount was deposited in the bank. Settlement timing, batching and charge deductions can change the amounts and dates.
For a multi-branch business, attach the original sale and provider transaction to the appropriate branch and operating unit. Treat payouts and bank receipts as separate ledger events. For a related comparison of available Nigerian payment providers, FlyingEze has scheduled Paystack vs Flutterwave vs Monnify: Comparing Payment Solutions for Nigerian Businesses, and the public link should be added after that article is published.
13. How to reduce processing expenses without compromising payments
- Measure your real average transaction value and channel mix before comparing providers.
- Confirm which specific checkout, virtual-account, POS or direct-debit product uses the quoted fee.
- Include flat charges, caps, VAT, outgoing transfers, duties and possible FX costs in the budget.
- Ask about merchant-specific discounts and eligible educational or volume-based pricing.
- Reconcile provider fee invoices and settlements each month, investigating unexplained differences.
- Consider who bears the fee, but disclose any checkout surcharge accurately and avoid misleading customers.
- Choose a reliable integration with strong verification, dispute handling and reporting, not merely the lowest headline rate.
A reliable online checkout can also improve trust. FlyingEze's existing article How Payment Gateway Integration Can Boost Your Website's Credibility explains the broader commercial importance of properly implemented online payments.
Frequently asked questions
Does the cheapest percentage guarantee the lowest total cost?
No. Fixed fees, caps, VAT, payout charges and transaction mix can change the result. Compare like-for-like products and actual monthly totals.
Does Paystack always charge ₦100 in addition to 1.5%?
No. Its published Nigeria checkout pricing waives the ₦100 fixed component for transactions below ₦2,500 and caps eligible local fees at ₦2,000.
Is Flutterwave's local fee 2% or 2% plus VAT?
Flutterwave publishes a 2% standard local collection fee and says its transaction fees are subject to 7.5% VAT. A calculation of full service expense should account for the applicable fee VAT.
Is Monnify's ₦500 flat transfer fee available to everyone?
Its pricing table displays a capped percentage and a ₦500 flat alternative for bank transfer/direct debit, without establishing universal eligibility for every merchant. Confirm the applicable pricing in writing.
Should stamp duty be added to all online card sales?
No. Applicable stamp duty depends on the type of transfer and the relevant statutory/provider rules. Paystack's 2026 merchant-outflow guidance distinguishes eligible payout duty from customer collection fees.
Conclusion
Payment processing costs are a measurable operating expense for Nigerian online businesses, not just a small deduction hidden on a settlement statement. Correct forecasting starts with each transaction's percentage, fixed component and cap, then adds relevant taxes, payouts, refunds and currency costs.
Compare providers using your own payment size and channel mix, verify live contracts, and reconcile gross sales to net bank deposits. The right payment solution is one that allows customers to pay reliably while keeping the business's full cost of accepting money clear and sustainable.