How Companies Use MTN Programmes to Raise Capital
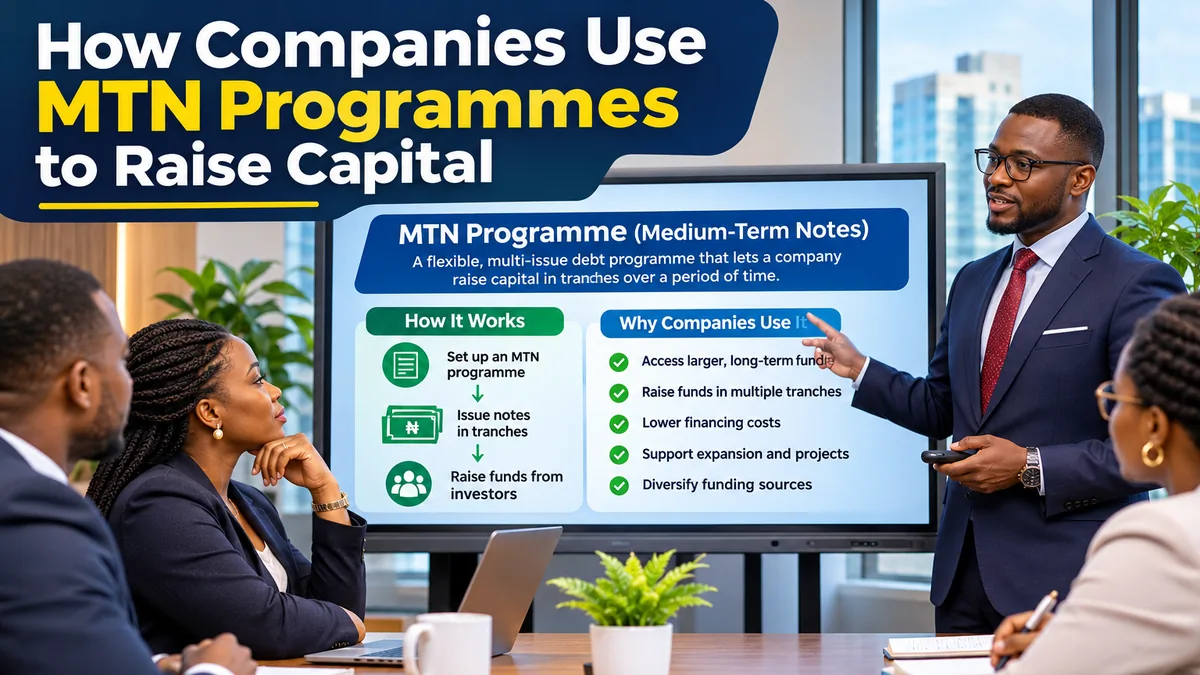
A company planning a factory, refinancing an expensive loan or expanding its lending business may need more capital than one bank is willing to provide on acceptable terms. One option is a medium-term note (MTN) programme: a financing framework through which an eligible issuer can sell debt securities to investors in separate issues over time, subject to the programme documents, market demand and applicable approvals.
The central advantage is flexibility: the issuer can establish an authorised programme limit and raise money through individual series or tranches when financing needs and market conditions justify an issue. A ₦50 billion programme does not mean the company has already collected ₦50 billion. It may initially sell only ₦10 billion of notes, then make further issues within the programme's conditions—or never use the full capacity.
Here is how companies design, launch and manage MTN programmes, with verified examples from Nigeria's FMDQ securities market. This is general financial education, not an invitation to invest or a substitute for regulated transaction advice. Research verified: 8 November 2026.
What is an MTN programme?
An MTN is a debt security under which the investor lends to the issuer in exchange for promised payments according to its terms. Unlike selling shares, issuing ordinary debt does not by itself transfer ownership or voting rights to investors. The US Securities and Exchange Commission's corporate-bond explanation sets out this basic lender-and-borrower relationship.
An MTN programme is different from a single MTN. It is the legal, regulatory and operational platform for potential issues. The programme documents typically establish common terms and maximum outstanding size, while an individual series or tranche sets specifics such as the amount raised, price, coupon, maturity, redemption arrangements and investors entitled to participate.
The expression medium-term is a market convention, not a guarantee that every note matures within a narrow range. Actual MTN programmes can support substantially longer tenors: FMDQ's 2026 NMRC listing describes a 10-year issue under a medium-term note programme. Always read the maturity of the actual series rather than relying on the programme's name.
Why would a company choose an MTN programme?
An eligible issuer may prefer staged issuance when its capital needs arise at different times. For example, a manufacturer could fund equipment this year and a second production line next year. A mortgage-refinance company might issue longer-term notes when funding becomes necessary to support lending. A holding company could use debt capital to refinance existing liabilities, provided its documents allow that use.
| Issuer objective | How an MTN programme may help | Important qualification |
|---|---|---|
| Raise money in stages | Separate series can correspond to project phases | Each issue still needs buyers and required approvals |
| Match funding to cash flows | Different maturities or amortisation structures may be available | Repayment capacity must support every obligation |
| Diversify lenders | Access institutional or other eligible debt investors | Eligibility depends on the offering and regulations |
| Refinance existing debt | Replace or reorganise maturing obligations | New rates, fees and covenants may be worse |
| Build capital-market visibility | Disclosure and potential listing can broaden investor awareness | Listing does not guarantee liquidity or credit quality |
These are potential benefits, not promises of cheaper finance. The wider impact of borrowing rates and fees is especially important when evaluating whether an MTN is genuinely more economical than a bank facility.
Step 1: Define the capital need and debt capacity
Management starts with a financing plan: how much cash is needed, when it is needed, what it will be used for and how investors will be repaid. Treasury and finance teams project operating cash flow, existing debt service, working-capital demands, capital expenditure and possible economic shocks.
The programme limit should reflect realistic financing plans, not merely an impressive headline. Directors must assess whether future interest and principal commitments are manageable, including if revenue weakens, exchange rates move or interest rates remain elevated. A debt issue can raise cash today while creating a concentrated repayment obligation years later.
Step 2: Appoint advisers and design the programme
An issuer typically works with a lead issuing house or arranger, legal advisers, relevant dealers or bookrunners, trustees, rating agencies, registrars and other service providers as required by the structure and market rules. Their responsibilities vary: an arranger coordinates documentation and distribution; dealers help place notes; trustees act within the terms of the trust documents; and ratings provide an opinion on specified credit risks rather than guaranteeing repayment.
Programme documentation generally defines the aggregate limit, eligible note forms, conditions, disclosure, events of default and a mechanism for documenting later issues. A specific drawdown then has its own pricing supplement or other transaction-specific document. LexisNexis's MTN drawdown overview describes both dealer-arranged and syndicated issues.
Step 3: Complete the required regulatory process
In Nigeria, MTN issuance must be assessed under the applicable Securities and Exchange Commission rules , including the amendments issued in April 2025 and the framework of the Investments and Securities Act, 2025. The rules differ by issuer type, securities structure, investor eligibility and offering method.
Where shelf registration is available, an issuer may establish a core disclosure framework that supports later offerings with the necessary supplements and approvals. It is wrong to assume approval of a programme automatically authorises every future tranche without further steps. Private-company debt issuance has separate restrictions, including qualified-investor requirements under the SEC's 2025 rules. Specialist legal advice is essential before marketing securities.
Registration or exchange listing should never be described as a regulator's promise to repay investors. The issuer remains responsible for its obligations, and investors need to consider the specific note and credit support.
Step 4: Choose the terms of an individual issue
When the company is ready to raise money, it works with advisers to decide the amount, currency, term, coupon, issue price, payment dates, security or guarantees, redemption method and other protections.
For example, a company may prefer a fixed coupon to know its nominal interest commitment in advance, while another could consider a floating-rate structure if the programme permits it. A bullet note ordinarily repays its principal at maturity; an amortising note returns principal in instalments. Some structures include early redemption provisions, with implications for investors and issuers alike.
Deal-specific terms must be explicit. A headline yield is not necessarily the coupon, and the proceeds the company receives after issuance costs may differ from the notes' face value.
Step 5: Price and place the notes with investors
The arranger or dealers assess demand, market yields, the issuer's financial condition, credit enhancements, comparable debt and the proposed tenor. They may solicit indications of interest or run a book-building process where permitted. The final coupon, issue price and allocation depend on the offering arrangements and investor orders.
Depending on the transaction and Nigerian regulatory rules, buyers may include institutional investors such as pension-related funds, insurers, asset managers or other qualified participants. Do not assume every MTN is available to retail investors or that every programme provides a liquid secondary market.
Market demand can improve execution, but it can also disappear during periods of elevated yields or reduced liquidity. An issuer may postpone an intended drawdown or accept a higher financing cost than anticipated.
Step 6: Receive proceeds and use them as disclosed
After subscription, allocation and settlement, the issuer receives the net proceeds of the particular notes sold, subject to transaction arrangements and deductions. The funds should be applied as described in the offer documents—for example to eligible capital projects, refinancing or specified business activities.
Money raised is not equal to programme capacity. Suppose a hypothetical company establishes a ₦50 billion programme with authorised terms but makes these issues:
| Illustrative series | Capital raised | Illustrative use |
|---|---|---|
| Series 1 | ₦10 billion | Production equipment |
| Series 2 | ₦15 billion | Factory expansion |
| Series 3 | ₦5 billion | Eligible debt refinancing |
| Total issued | ₦30 billion | Across three issues |
In this purely hypothetical example, total face amount issued is ₦30 billion, not ₦50 billion. An apparent ₦20 billion difference is unused programme capacity, subject to the programme's outstanding-balance calculation, maturity, legal restrictions and approvals. It is not cash sitting in the company's bank account.
Step 7: Budget for interest, principal and ongoing obligations
An MTN programme does not end when funds arrive. The issuer needs a continuing debt-service schedule, accurate accounting records and the resources to comply with covenants, disclosure obligations, investor notices and redemption terms.
Suppose one hypothetical ₦10 billion note is issued at par with an 18% annual fixed coupon, paid twice yearly, and bullet repayment after five years. Ignoring taxes, fees and defaults, its annual coupon would be ₦1.8 billion, with two payments of ₦900 million each year; the ₦10 billion principal would become payable at maturity. This is a teaching calculation, not a Nigerian market quote.
For notes issued below par or with amortising principal, the cash flows and effective financing cost differ. Finance teams should model more than simple coupon percentages: include arranger and professional fees, listing expenses, credit enhancement, taxes, financing charges and any covenant-related costs.
Real Nigerian example 1: DLM's ₦30 billion MTN programme
On 5 March 2026, FMDQ Securities Exchange announced the listing approval of ₦7.30 billion and ₦1.70 billion composite notes under a ₦30 billion medium-term note programme associated with DLM SPV. The notes used a structured, sovereign-bond-backed arrangement designed to support financing activity, according to FMDQ's announcement .
The visible issues total ₦9 billion. That does not show that ₦30 billion was already raised. Nor should the structure's ratings or unusual reported yields be treated as typical of ordinary unsecured corporate MTNs. The example demonstrates how a programme can support particular tranches with separately disclosed features.
Real Nigerian example 2: NMRC's ₦440 billion programme
FMDQ reported on 8 May 2026 that Nigeria Mortgage Refinance Company (NMRC) listed an ₦11.50 billion, ten-year, 17.25% fixed-rate Series 1 bond under its ₦440 billion medium-term note programme. The exchange said the proceeds would support NMRC's mortgage-refinancing activities and long-term funding of primary mortgage lenders. Read FMDQ's transaction announcement .
The official issue listing describes quarterly coupon dates and bullet redemption unless otherwise provided. This illustrates how a relatively small first issue can sit inside a much larger programme framework—and why a note labelled “medium-term” may have a ten-year tenor.
How does an MTN programme compare with a bank loan, commercial paper or equity?
| Option | Typical financing characteristic | Key trade-off |
|---|---|---|
| Bank loan | Negotiated borrowing with lenders | Bank limits, security and covenants |
| Commercial paper | Usually short-term debt for funding needs | Frequent refinancing risk |
| MTN programme | Multiple potential debt issues under a programme | Upfront structuring, disclosure and market access costs |
| Standalone bond | One separately structured debt issue | May be less flexible for repeated issues |
| New equity | Capital raised by selling ownership interests | Dilution and governance considerations |
Borrowing through securities and selling shares are fundamentally different. FlyingEze's coverage of FGN bond settlement offers useful context about the mechanics of Nigeria's broader debt market, although government bonds have different credit characteristics from corporate notes.
Important risks for issuers and investors
For issuers, the principal dangers include interest-cost surprises, inability to refinance at maturity, cash-flow mismatch, covenant breaches, unsuccessful offerings, foreign-currency exposure where relevant, and the reputational consequences of a default. Multiple tranches can diversify maturities, but poor planning can still create a difficult repayment concentration.
Investors face credit risk if the issuer cannot pay; interest-rate risk if market yields rise and the note's resale price falls; liquidity risk if few buyers exist; and potential call or reinvestment risk where early redemption is permitted. These are standard debt-security risks described in Investor.gov's bond education . An investment-grade rating or exchange listing does not eliminate them.
Where a structure relies on guarantees, security, an SPV or assets backing the notes, investors should read precisely whose obligation they hold and what protections apply. Marketing terms such as “secured”, “AAA-rated” or “capital protected” should never replace a review of the signed documents.
Issuer checklist before launching an MTN programme
- Map the required funding to specific uses and realistic project timelines.
- Stress-test operating cash flows and total existing debt service.
- Compare programme fees and debt pricing with loans, commercial paper and equity.
- Confirm issuer eligibility and current SEC and exchange requirements with advisers.
- Obtain board approvals, complete due diligence and prepare the offering documents.
- Select qualified arrangers, dealers, trustees and other service providers.
- Document how each series will be priced, allocated, reported and redeemed.
- Build systems to track outstanding amounts, investor payments and covenants.
- Disclose proceeds and material risks accurately; update investors as required.
Frequently asked questions
Does registering a ₦50 billion MTN programme mean raising ₦50 billion immediately?
No. It establishes a framework or limit subject to its terms. Cash is raised only through actual note sales and settlement. The limit should not be reported as proceeds received.
Are MTN programmes only for banks?
No. Eligible corporates, special-purpose issuers and other permitted entities can use MTN structures. Nigerian examples include mortgage-refinancing and structured-finance issuers. Requirements depend on issuer type and offering rules.
Do MTNs always have shorter maturities than corporate bonds?
No. MTNs are a way of structuring and distributing debt, and actual maturities vary. FMDQ lists a ten-year NMRC issue under a medium-term note programme.
Can any Nigerian individual invest in an MTN issue?
Not necessarily. The investor category and offering restrictions depend on the securities, issuer and current law. Some debt issues are restricted to qualified investors.
Does an MTN programme guarantee cheaper finance?
No. Total financing costs depend on yields, issuance expenses, market conditions, credit risk, hedging and ongoing compliance. A company should compare its actual all-in alternatives.
Is an MTN programme the same as MTN Nigeria, the telecom company?
No. Here, MTN stands for medium-term note, a debt-financing instrument. It is unrelated to the telecommunications brand.
Conclusion
An MTN programme lets an eligible company prepare a debt-financing framework and issue securities in stages rather than automatically borrowing the full headline programme amount. Its value lies in disciplined funding flexibility: matching capital raised with projects, investor demand and repayment capacity.
Nigeria's DLM and NMRC transactions show these programmes in action, while also demonstrating why deal-specific terms matter. Companies considering MTNs should consult regulated advisers, compare all-in costs, understand the current SEC rules and build the cash-flow discipline needed to repay every note issued.