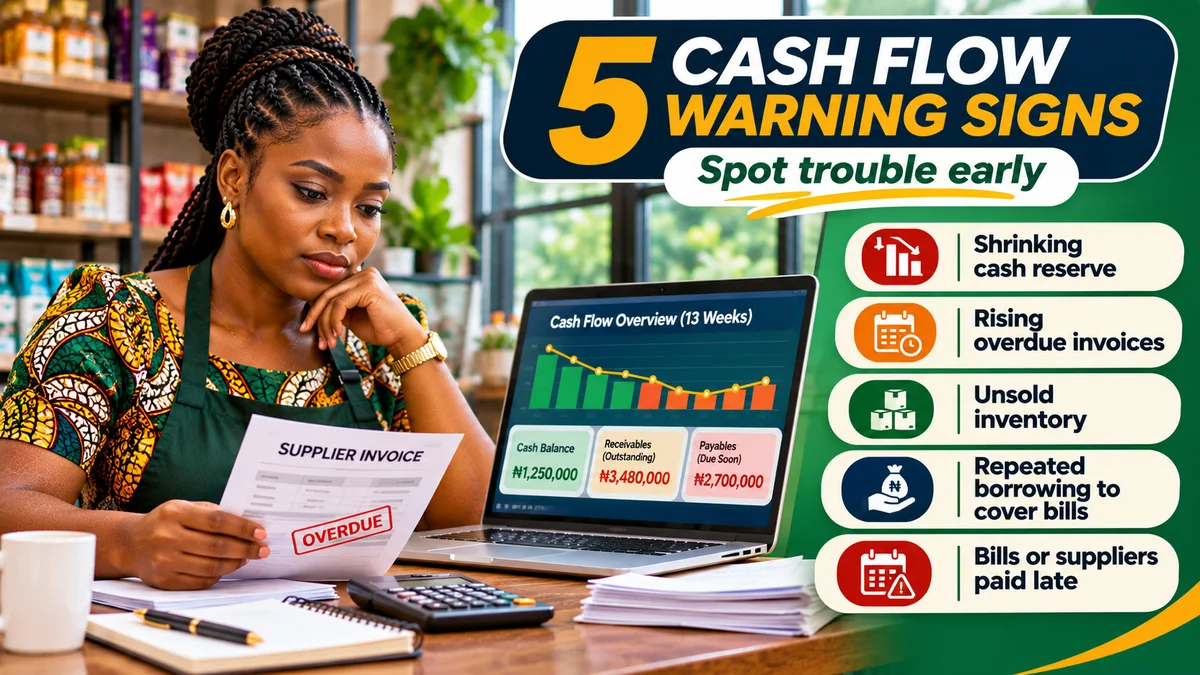
Five cash flow warning signs small business owners should never ignore are shrinking available cash, growing overdue customer invoices, excessive slow-moving stock, repeated borrowing to cover ordinary costs, and increasingly late payments to suppliers, employees or other essential creditors. None automatically proves that a company is failing. Together—or when worsening over several weeks—they can indicate that money is leaving the business faster than it can be replaced.
A Nigerian shop may be busy every day and still lack enough cash for its next stock order. A Lagos service company can show a profit on paper but wait weeks for a large customer to pay. A restaurant may record strong weekend sales yet have insufficient cleared funds for salaries, electricity, generator fuel and suppliers. The Australian Government's financial-distress guidance identifies late-paying customers, difficulty paying debts, deteriorating liquidity and reliance on borrowing as warning signs. The British Business Bank likewise warns that even profitable firms can experience serious working-capital pressure.
This guide explains how to identify each problem, which numbers to check and what action to take before an avoidable cash shortage becomes a crisis. Examples are fictional, not Nigerian industry statistics or forecasts for a real company. Research verified 3 November 2026.
Why cash flow problems can hide behind healthy sales
Cash flow measures money entering and leaving a business over time, while profit uses accounting rules that can recognise income before customers pay and expenses before cash changes hands. The IFRS Foundation's IAS 7 overview distinguishes operating, investing and financing cash flows. A management forecast should separately show actual receipts, payments and financing rather than presenting a new loan as trading revenue.
Imagine delivering ₦2 million of goods on 30-day credit after paying ₦1.4 million for stock. The sale may create an accounting margin, but cash is still tied up in what the customer owes. If staff, rent and electricity are due next week, an apparently profitable period can be a liquidity problem. Warning signs matter because they reveal timing, concentration and recurring funding gaps before a month-end financial statement tells the full story.
Warning sign 1: Your cash reserves keep shrinking
Bank and cash balances naturally fluctuate. What deserves attention is a sustained downward trend or a forecast showing that available cash will fall below the amount needed for unavoidable commitments. Compare reconciled, usable funds across bank accounts, cash on hand and cleared payment balances. Exclude customer money held for another purpose, uncleared settlements and transfers between your own accounts so you do not double-count cash.
For example, if genuinely available cash falls from ₦1.8 million to ₦1.2 million and then ₦700,000 over three weekly reviews, ask why: Did cash collections weaken, did an annual expense come due, or did the business spend too much on inventory? A planned equipment purchase may explain one fall; a persistent operating deficit is a different risk.
Numbers to check
Calculate net weekly cash movement = actual cash received − actual cash paid. Then compare your lowest projected closing balance over the next 13 weeks with a management-defined safety buffer. If a business has ₦600,000 available and ordinary unavoidable cash outgoings of ₦300,000 weekly, it has a rough two weeks of gross cost coverage if no new money comes in. That is not a precise cash runway, because actual receipts and payment dates also matter.
What to do now
Reconcile all accounts, prepare a short-term cash calendar, identify essential commitments, check collections due and temporarily challenge discretionary spending. Do not assume growth or the current bank balance will automatically fund next week's bills. If the projected balance becomes negative, plan an immediate discussion with an accountant or suitable adviser and the affected parties.
Warning sign 2: More customers are paying late, and receivables are ageing
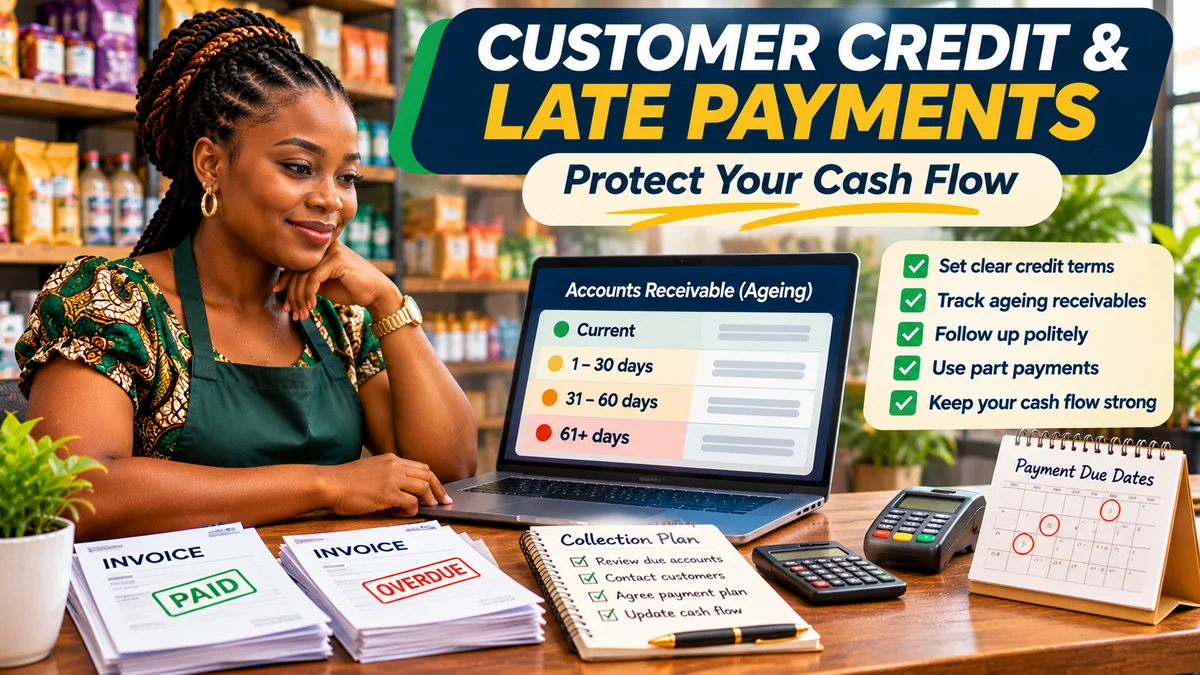
Invoices are not spendable cash. When a growing portion of sales remains unpaid after agreed deadlines, businesses effectively finance their customers while still paying their own costs. The British Business Bank's guidance on late payments recommends sound credit checks, prompt invoicing and professional follow-up; its cash-culture guidance also recommends reviewing whether persistently slow-paying customers should move to cash-on-delivery terms.
Use an accounts-receivable ageing report based on days past the agreed due date. For a fictional retailer with ₦1 million in unpaid invoices, imagine ₦280,000 is not yet due, ₦350,000 is 1–30 days overdue, ₦260,000 is 31–60 days overdue and ₦110,000 is more than 60 days overdue. That means ₦720,000, or 72%, is overdue. The percentage is an example rather than a universal threshold; the trend and likelihood of collection matter most.
Numbers to check
Track the overdue percentage, total overdue naira value, disputed balances and promised-payment dates. For a more mature system, use days sales outstanding alongside the ageing report. Keep a separate column for disputed invoices so finance staff can distinguish a genuine billing problem from a customer who has simply missed a due date.
What to do now
Verify that invoices went to the right decision-maker, include accepted purchase-order references and contain correct payment details. Send courteous reminders, call appropriate billing contacts and record specific commitments. Require deposits or narrower credit limits where justified. Reconcile bank-transfer settlements to invoices rather than accepting screenshots alone. FlyingEze's report on FCMB Collect and digital business collections offers related context on payment identification and reconciliation.
Warning sign 3: Too much money is trapped in slow-moving inventory
Shelves full of products can make a business look successful while reducing money available for payroll and suppliers. Unsold stock carries purchase cost and potentially storage, damage, shrinkage and expiry costs. This affects shops, pharmacies, fashion retailers, food businesses and manufacturers differently, but the core question is the same: how much working capital is sitting in items that customers are not buying quickly enough?
The Australian Government's cash-flow improvement guidance recommends inspecting stock levels, avoiding over-ordering and clearing products that are not selling. The British Business Bank's overtrading guidance also explains how growth can create cash pressure if a business needs more inventory and working capital than it can finance.
Imagine a small retailer holds ₦1.2 million of goods at cost, including ₦400,000 of seasonal inventory that has not moved in 90 days. The ₦400,000 is cash committed to inventory, not a guaranteed ₦400,000 loss or the amount that could necessarily be recovered from a sale.
Numbers to check
Review stock ageing by product, inventory turnover and the proportion of purchases tied to known demand. A simplified days inventory outstanding measure is average inventory at cost ÷ cost of goods sold × days in the period, provided the accounting basis is consistent. Compare similar trading periods rather than setting a universal “good” number across unrelated industries.
What to do now
Stop repeat orders for stagnant items unless there is a defensible reason; check stock accuracy, plan targeted clearance without destroying margins, and consider smaller replenishment batches. Negotiate realistic supplier order quantities and evaluate whether items are obsolete, slow-moving for seasonal reasons or simply overstocked. Preserve access to fast-selling products so an indiscriminate cutback does not harm future sales.
Warning sign 4: You keep borrowing or injecting personal money to pay ordinary bills
Borrowing is not inherently bad. A properly costed loan might finance an asset that increases capacity or help bridge a documented seasonal gap. The warning is repeated dependence on overdrafts, expensive short-term borrowing or personal cash top-ups to pay regular operating bills without a credible repayment plan.
For instance, a business owner contributes ₦250,000 from personal savings in three consecutive weeks to cover fuel, suppliers and salaries. If the business still cannot meet ordinary commitments after those injections, management should assess operating margins, collection timing and fixed costs rather than treating the top-ups as sales. The Australian Government identifies reliance on borrowed funds to keep operating as a potential financial-stress indicator, and the British Business Bank describes dependence on overdrafts as an overtrading warning.
Numbers to check
Separate operating cash inflows from loan advances and owner contributions. Track interest, principal repayments, overdue lender obligations, credit-facility utilisation and weekly cash from operations. An illustrative measure is operating funding gap = unavoidable operating payments − expected operating receipts over the same period, excluding new borrowing. It tells you whether the underlying activities can cover the upcoming commitments.
What to do now
Compare borrowing costs with realistic business returns and revise the cash forecast to include each repayment. Investigate whether delayed collections, underpricing, overstocking or an unprofitable service line is driving the need for cash. If existing debt has become difficult to service, seek professional advice early rather than taking new high-cost loans simply to pay old ones.
Warning sign 5: Bills, wages or supplier payments keep slipping past their due dates
The clearest sign of immediate pressure can be repeated inability to meet commitments that are already due: supplier invoices, wages, rent, essential utilities, loan instalments or applicable taxes. A single delay caused by a payment-processing error is different from a pattern of borrowing from the next week's receipts to cover last week's bills.
Late payments can damage supplier relationships, interrupt restocking and undermine staff trust. They may also expose a business to contractual, statutory or regulatory consequences depending on the obligation. Do not assume Nigerian businesses share the same tax schedules or late-payment penalties; verify the requirements that apply to your entity.
Numbers to check
Prepare a 14-day list of payments due, grouped by contractual urgency, operational importance and consequences of delay. Record due date, amount, approved payment source and responsible person. Compare this with money already cleared and credible receipts expected before each payment date. If cash is insufficient at the time a bill comes due, a positive month-end balance will not solve the immediate problem.
What to do now
Contact suppliers or creditors early to discuss realistic, documented arrangements; prioritise legal and essential commitments with appropriate professional input. Stop promising payment dates unsupported by your forecast. Review avoidable spending, chase collectible invoices and assess options before missing wages or statutory payments. The Australian Government's cash-flow management guide encourages proactive records, cost control and timely advice when liquidity is under strain.
A practical cash-flow warning dashboard for Nigerian SMEs
Rather than waiting until the bank account is nearly empty, review a small dashboard each week. The table below shows both an early-warning signal and the follow-up it should trigger.
| Indicator | Early warning | Check and response |
|---|---|---|
| Available cash | Declining for several weeks; projected to breach a minimum cash buffer | Reconcile balances, update weekly forecast, review discretionary cash outflows |
| Customer receivables | Overdue value and ageing rising | Verify invoice accuracy; contact customers; review credit terms |
| Inventory | Slow-moving stock growing relative to sales | Age stock, stop unnecessary reorders, assess clearance |
| External funding | Repeated borrowing or owner cash injections for routine bills | Separate operating cash from funding; test repayment sustainability |
| Payments due | Repeated missed due dates or increasing unpaid supplier balances | Prepare 14-day payment calendar and agree lawful priorities |
A warning becomes more urgent when multiple indicators occur together. For example, a wholesaler with late-paying customers, excess stock and a near-exhausted overdraft has three interacting problems, even if its sales report looks attractive.
Worked example: a four-week cash slide that needs intervention
Consider a fictional Nigerian distribution business. It starts with ₦1.4 million genuinely available and forecasts the following weekly movements. Every amount is in ₦'000; 700 means ₦700,000.
| Week | Opening | Receipts | Payments | Closing |
|---|---|---|---|---|
| 1 | 1,400 | 700 | 950 | 1,150 |
| 2 | 1,150 | 600 | 1,050 | 700 |
| 3 | 700 | 630 | 850 | 480 |
| 4 | 480 | 580 | 900 | 160 |
Receipts total ₦2.51 million and payments total ₦3.75 million, producing a ₦1.24 million net outflow. The closing balance after four weeks is ₦160,000. If management chose a ₦500,000 minimum operating buffer, week three would fall ₦20,000 below it and week four would fall ₦340,000 below it.
This example does not prove insolvency. But management should not wait until week four to act: the forecast already indicates a material shortfall against its chosen buffer. Investigate whether the decline comes from receivables, purchases, ordinary costs, debt service or a one-off item before selecting an intervention.
Keep this four-week view inside a rolling 13-week cash forecast. A weekly forecast gives enough visibility to identify near-term gaps and plan collections, supplier discussions and financing decisions. A separate monthly or annual budget remains useful for long-term strategy.
What to do in the next seven days if you recognise two or more signs
- Day 1 — Establish the facts: Reconcile bank, cash and payment-channel balances; identify cleared and restricted funds.
- Day 2 — List obligations: Record every payment due over the next 14 days and its actual deadline.
- Day 3 — Review collections: Age customer invoices; resolve disputes and confirm realistic receipt dates.
- Day 4 — Inspect stock: Identify slow-moving products, commitments to buy more and opportunities to reduce excess orders.
- Day 5 — Separate funding: Reconcile loans, owner injections and repayments against operating cash flow.
- Day 6 — Reforecast: Update a 13-week plan, test delayed collections and note the lowest available balance.
- Day 7 — Assign actions: Give each approved collection, cost or supplier-negotiation action an owner and review date.
Do not manufacture revenue merely to fill a forecast, count inter-account transfers as sales or assume that every outstanding invoice will be collected on its printed due date. If your forecast shows that wages or debts cannot be paid as they become due, obtain prompt advice from a qualified Nigerian accountant or lawyer about the business's options.
Which business tools can make the warning signs more visible?
Start with reliable records. A spreadsheet may be enough for a small business with a few accounts and invoices. For more complex operations, a sales, inventory and finance system can help reconcile activity, while a budgeting or money-tracking tool can highlight upcoming commitments.
For example, P-Biz Solutions publicly describes POS, inventory and operational-finance products for businesses such as hospitality and retail firms. KudiScope describes tracking existing bank, wallet and cash activity, spending trends, budgets and upcoming commitments, without holding customers' funds. Check product availability and the fit for your workflow before assuming that either service automatically produces a complete 13-week forecast.
The key is a consistent, verified record of what was received, spent, owed and due. A colourful dashboard based on incomplete invoices or unreconciled transfers will not provide reliable early warning.
Frequently asked questions
Can a profitable small business still have a cash flow problem?
Yes. Profit can include sales not yet paid for. Stock purchases, customer credit, loan repayments or capital spending may consume cash before the business receives enough money from customers.
What is the first cash flow warning sign I should monitor?
Start with reconciled available cash and the lowest forecast balance over the next few weeks. Then investigate receivables, inventory and upcoming commitments to understand why that figure changes.
How much cash should a Nigerian small business keep as a buffer?
There is no universal amount. Base a realistic buffer on essential costs, payment timing, customer concentration, seasonality and access to funding. Review it when circumstances change.
Are rising customer receivables always a problem?
No. Receivables can rise with genuinely growing credit sales. A warning develops when overdue balances, concentration risks or collection times worsen relative to agreed terms and available working capital.
Should I immediately stop buying stock when cash is tight?
Not necessarily. First distinguish slow-moving stock from products needed to fulfil profitable demand. Reducing unnecessary purchases can release cash, but cutting critical inventory without analysis may worsen sales and service.
Is borrowing always a cash flow warning sign?
No. Planned and affordable financing can support productive investment or a seasonal cycle. Repeated borrowing to cover routine losses without a credible repayment source deserves closer investigation.
Conclusion
Cash flow warning signs are most useful before a business misses an important payment. Falling cash reserves, ageing invoices, slow inventory, repeated emergency borrowing and overdue essential bills each reveal a different weakness in the movement of money. Review them together, reconcile the underlying records and maintain a rolling forecast. Acting early gives a business owner more options than reacting after suppliers, employees or customers have already been affected.