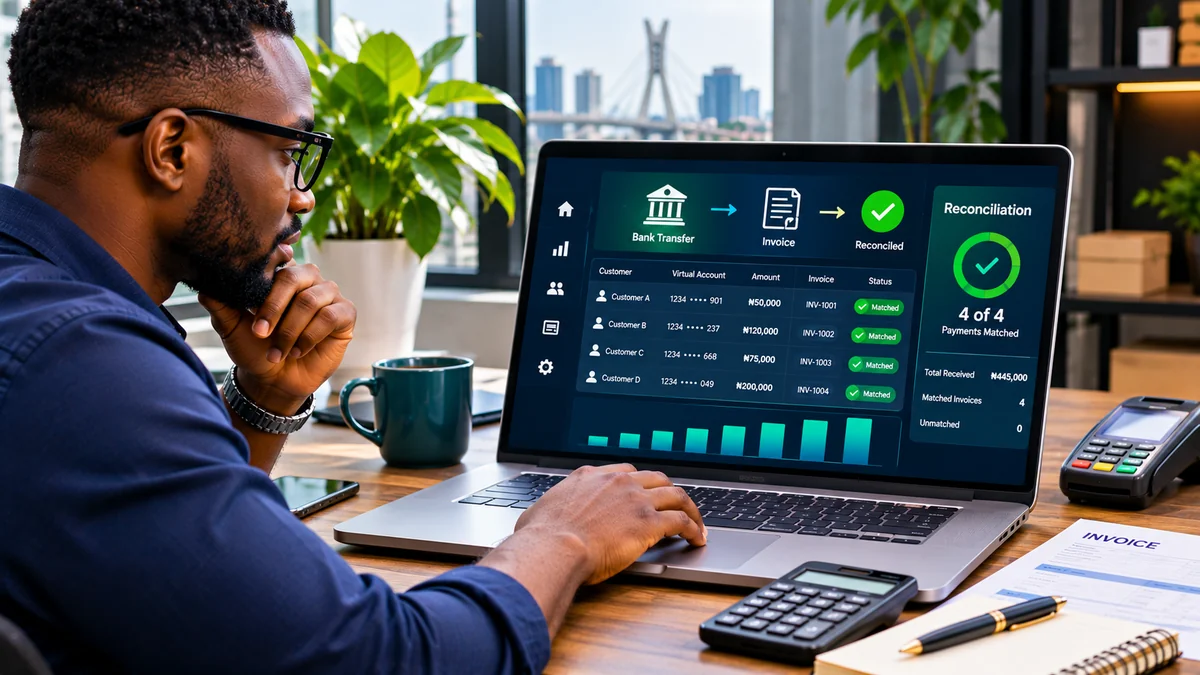
When customers pay a Nigerian business by bank transfer, staff may spend hours checking bank alerts, reviewing screenshots and asking who sent each payment. A transfer could be genuine while still being assigned to the wrong order, and a successful customer payment may not yet match the amount the business receives after processing fees. Virtual bank accounts help solve these problems by linking incoming transfers to an identifiable transaction or customer.
Payment gateways in Nigeria, including Paystack, Flutterwave and Monnify, offer virtual account products for eligible businesses. But an account number alone is not a complete accounting system. This guide explains temporary and reusable accounts, how payment notifications work, and how to reconcile transactions and settlement safely.
1. What is a virtual bank account?
A virtual account is a bank account number issued through an authorised payment-service arrangement and associated with a merchant's payment collection system. Customers transfer funds using familiar banking apps or internet banking. The provider then records the payment and exposes identifiers that help the merchant match it to a customer or an invoice. The business normally receives settlement through its approved provider arrangement rather than automatically owning each displayed collection account as a separate deposit account.
Paystack's dedicated virtual account guidance describes customer-linked bank details that accept transfers anytime, with transactions appearing on the merchant dashboard. Flutterwave's virtual accounts overview distinguishes reusable accounts from temporary collection accounts. Monnify documents persistent customer reserved accounts for repeat transfers. The term 'virtual' does not mean an imaginary transfer: real funds move through the banking system, but attribution is managed digitally.
2. Temporary versus permanent accounts
| Feature | Temporary/dynamic account | Reserved/static account |
|---|---|---|
| Main assignment | One checkout or invoice | One customer or ongoing collection relationship |
| Account lifetime | Often expires after a set period or use | Can be reused under provider rules |
| Typical use | One-time sales, event tickets, deposits | School fees, repeated orders, customer funding |
| Payment matching | Usually matched to a single request | First matched to customer; invoice allocation may need more logic |
| Requirements | Provider-specific | May require extra customer identity verification |
For example, Flutterwave's NGN virtual account documentation describes dynamic accounts with an expiry and static accounts requiring a customer's BVN or NIN. It also distinguishes its Virtual Account product from the simpler Pay With Bank Transfer option. These names are not guaranteed to mean the exact same thing across providers.
3. How a customer payment is collected and matched
- A business creates an invoice, order or customer record in its own application.
- The payment gateway issues eligible virtual bank-account details associated with the transaction or customer.
- The customer transfers money from a supported bank or payment app.
- The provider processes the transfer and records a corresponding transaction.
- A webhook or subsequent verification response gives the merchant a payment reference and status.
- The application verifies the transaction, matches it to the correct customer and applies the business's rules for the invoice.
- Finance staff later reconcile provider transaction records with settlement reports and the bank statement.
Do not treat a customer's screenshot as proof of completed payment. Nor should a front-end 'success' page alone authorise an order or wallet credit. The merchant should independently verify the provider's final status, payment amount, currency and relevant reference before giving value.
4. How virtual accounts reduce manual reconciliation
Without a payment reference or customer-linked collection account, a shop might receive several bank transfers with nearly identical values. Staff must search bank statements and ask customers for sender names, which may not match account-holder information or invoice names. A dedicated account reduces that ambiguity because the account-to-customer assignment is already known.
A school can associate a reserved account with a parent or student billing profile. A wholesaler can issue a temporary account for an order. A hotel can collect an identified deposit. When an eligible transfer arrives, the system creates a traceable record and can suggest the correct invoice.
But a permanent account identifies the customer, not necessarily which of that customer's three outstanding invoices the payment should settle. The business still needs an allocation rule: match the stated invoice reference, allocate to a customer balance, or hold the receipt for review. **Automatic identification is not the same as automatically correct accounting.**
5. Example: Reconciling four incoming transfers
Imagine a Nigerian supplier issues four invoices: A for ₦50,000; B for ₦120,000; C for ₦75,000; and D for ₦200,000. Each customer pays through an assigned collection account. If all four transfers are verified at the exact invoice amounts, gross receipts total ₦445,000. These figures are illustrative, not actual provider transactions.
| Customer | Invoice | Verified transfer | Allocation |
|---|---|---|---|
| A | ₦50,000 | ₦50,000 | Matched |
| B | ₦120,000 | ₦120,000 | Matched |
| C | ₦75,000 | ₦75,000 | Matched |
| D | ₦200,000 | ₦200,000 | Matched |
| Total | ₦445,000 | ₦445,000 | 4 invoices |
Suppose the provider deducts ₦2,500 in total processing charges. The expected net settlement would then be ₦442,500, assuming no refunds, reserves or other adjustments. The accounting records must show gross sales, processing costs and net cash separately. A shortfall between ₦445,000 gross receipts and ₦442,500 net settlement is not necessarily a missing payment.
Monnify's reconciliation documentation explicitly distinguishes transaction-level matching from settlement-level matching, and instructs merchants to compare net settlement fields rather than gross amounts against wallet credits.
6. What happens when the amount is wrong?
Real customers do not always pay exactly what an invoice requests. Someone may transfer ₦9,000 against a ₦10,000 invoice, overpay, send a duplicate payment or transfer to an expired account. Provider behaviour differs by account type; for example, Flutterwave's NGN virtual account documentation states that certain dynamic-account underpayments are automatically reversed, while excess payments can be returned after the intended amount is processed.
Do not generalise that policy to every permanent virtual account. Businesses should define explicit states such as pending, partially paid, paid, overpaid, reversed and disputed. If a permitted partial transfer is received, show the balance owed; if excess money arrives, decide whether a customer credit or refund is allowed under the provider's terms. Do not automatically mark an invoice paid just because a transfer was detected.
7. Compare Paystack, Flutterwave and Monnify
Paystack dedicated virtual accounts
Paystack allows qualifying registered businesses to assign dedicated Nigerian collection accounts. Customer details typically include a name, email and phone number, and some business categories require additional identity checks. Paystack's public pricing lists a 1% transaction fee capped at ₦300 for dedicated virtual accounts. This is not the same rate as its standard card checkout. Paystack's developer guide also describes a requery capability for confirmed transfers whose webhook is delayed; its usage is rate-limited.
Flutterwave NGN virtual accounts
Flutterwave provides dynamic and static NGN virtual account products. Its official guide explains expiry for dynamic accounts, NIN or BVN requirements for static accounts, and payment-status notifications through webhooks. Check the actual product version and merchant eligibility before integrating; availability and API payloads can differ by account and documentation version.
Monnify customer reserved accounts
Monnify supports customer reserved accounts and transaction-linked collection references. Its reserved-account guide requires a customer's BVN or NIN for account reservation and returns an account reference useful for matching. Its public pricing page lists bank-transfer collection at 1.5% capped at ₦2,000 alongside a ₦500 flat option; which option applies should be confirmed with Monnify rather than assumed.
8. Transaction reconciliation versus settlement reconciliation
A reliable system runs two related but different checks. Transaction reconciliation asks whether each payment in the provider's records corresponds to exactly one valid internal transaction, with a matching reference, status, amount and currency. Settlement reconciliation asks whether the merchant actually received the expected net funds after fees, refunds and any other adjustments.
For the first check, import complete provider transactions over a consistent period and look for missing, duplicate, mismatched or reversed payments. For the second, group verified payments by settlement batch, compare provider net-settlement figures with the bank statement, and record discrepancies. Not every payment collected today necessarily settles in the same batch.
For a multi-branch business, preserve the branch and business-unit association when payment records enter the ledger. For marketplaces, distinguish platform fees from seller liabilities and reconcile each provider split independently when supported. Customer payments, merchant settlements and supplier payouts should not collapse into one generic 'paid' status.
9. Webhook security and duplicate payment prevention
Webhooks allow a provider to notify a merchant application when payment events happen. They are valuable but require careful verification because webhook endpoints are publicly reachable and notifications can be delayed, repeated or delivered out of order. Paystack uses an x-paystack-signature HMAC header; Monnify documents a monnify-signature header for production notifications; and Flutterwave's authentication method depends on the specific API version.
Follow the Paystack webhook guide , Monnify webhook guide and Flutterwave webhook guide relevant to the implementation. Authenticate event origin, verify critical details against the provider API, record unique transaction/event identifiers and process account credits atomically. Retry safely and do not grant value twice if the same success event is delivered again.
An internal job should also reconcile missing notifications against provider records. A quick successful webhook acknowledgment is not a substitute for reliable background processing and auditable status updates.
10. Privacy, identification and operational responsibilities
Some account products require customer names, contact details, BVN or NIN. Collect only what the chosen provider and applicable requirements actually need, explain the purpose, transmit data securely and avoid displaying sensitive identifiers in application logs. Restrict staff access and establish retention rules. A virtual account issued through a provider does not automatically confer permission to operate a bank or hold customer deposits outside the merchant's permitted activities.
Before rollout, confirm account limits, allowed business categories, pricing, chargeback and refund procedures, settlement arrangements and operational support. A business may not have identical virtual-account privileges under every payment gateway or at every account-verification level.
11. Which businesses benefit most?
- Schools: Associate recurring bank transfers with parent or student billing records while maintaining a clear invoice-allocation process.
- Hotels and hospitality: Track booking deposits and customer payments without depending solely on screenshots, with separate treatment for refunds and rescheduled bookings.
- Wholesalers and online shops: Use temporary accounts for high-value orders and verify exact payment before dispatch.
- Subscription and software platforms: Use persistent accounts for repeat customer transfers, while recognising that this is not the same as an authorised automatic debit mandate.
- Multi-branch organisations: Reconcile collections by customer, invoice, branch and settlement batch before posting accurate management reports.
12. Checklist before implementing virtual accounts
- Confirm merchant eligibility, account types, customer identification requirements and written pricing for the chosen provider.
- Decide whether each payment needs a temporary invoice account or a persistent customer account.
- Create unique internal IDs for customers, invoices, payment attempts and provider transactions.
- Implement and authenticate provider webhooks, plus server-side verification and idempotent status changes.
- Define business rules for expired accounts, underpayments, overpayments, duplicates, refunds and reversals.
- Reconcile provider transaction records daily or at an appropriate interval and match net settlements against the bank statement.
- Test ordinary and failure scenarios in the provider's approved sandbox, then validate a controlled live rollout.
- Monitor unexplained settlement differences and preserve financial audit logs without exposing unnecessary personal data.
For broader provider selection criteria, FlyingEze has a separate comparison of Paystack, Flutterwave and Monnify scheduled for 11 November 2026. Its public URL should be linked only after publication is confirmed. The live article How Payment Gateway Integration Can Boost Your Website's Credibility provides additional context for online collections.
Frequently asked questions
Is a virtual account the same as a customer's personal bank account?
No. A collection account is created and managed under a payment provider's business arrangement to receive transfers for the merchant. It should not be represented as an ordinary deposit account owned by the customer.
Can a customer reuse the same virtual account?
Yes, if the provider issues a persistent or reserved account and the relevant conditions remain satisfied. Dynamic checkout accounts generally have a limited lifetime.
Does a bank-transfer alert mean an invoice is fully paid?
Not necessarily. Verify the provider's transaction status, the amount received, currency, correct customer or order, and the business's invoice-allocation rules.
Can virtual accounts automatically reconcile settlement into my bank account?
They improve transaction identification, but accounting still needs to reconcile provider-reported net settlement, fees, adjustments and the actual bank credit. These are separate checks.
Which Nigerian payment gateways offer virtual accounts?
Paystack, Flutterwave and Monnify all document eligible virtual-account products. They differ in account lifetime, onboarding requirements, supported use cases and pricing.
Conclusion
Virtual bank accounts can simplify how Nigerian businesses collect transfers, identify customers and maintain accurate payment records. They are particularly useful where numerous customers pay by transfer and manual matching causes delays. However, a virtual account number is only one part of a dependable system: secure verification, clear allocation rules, idempotent processing and settlement reconciliation remain essential.
Choose the provider and account type that fit the actual billing workflow, test failure cases, protect customer data and compare total operating costs. The strongest result is not merely faster payment collection, but more dependable customer balances, invoices and financial statements.