To manage customer credit and late payments without damaging cash flow, agree written payment terms before selling on credit, limit how much each customer can owe, issue accurate invoices promptly and follow up on overdue amounts consistently. When a reliable customer is struggling, a documented payment plan may protect both the relationship and your working capital. The goal is not to collect aggressively; it is to prevent unpaid sales from becoming an unexpected funding problem.
For a Nigerian distributor in Onitsha, a caterer in Lagos or a service firm in Abuja, offering customers seven, fourteen or thirty days to pay may help win repeat business. But suppliers, rent, salaries, generator fuel and loan instalments often must be paid before customers settle their bills. As the British Business Bank's late-payment guidance explains, cash tied up in unpaid invoices can leave otherwise active businesses short of working capital.
This practical guide covers risk checks, deposits, payment terms, accounts-receivable ageing, a polite reminder timetable, disputed invoices, instalment arrangements and a worked naira cash-flow example. The numbers below are hypothetical, and any legal or tax consequences should be checked against your actual contract and applicable Nigerian law. Research verified 3 November 2026.
Why customer credit creates a cash-flow problem
A credit sale is not the same as cash received. If you deliver ₦500,000 of goods today and give the customer 30 days to pay, you may record a sale, but the ₦500,000 is still a receivable until paid. Meanwhile, you may owe your supplier immediately. The result can be rising sales and falling bank balances at the same time.
Customer credit can be useful. It can make purchases easier for established corporate clients and help a business secure larger contracts. But credit also exposes the seller to delayed payment, disputes and eventual bad debt. The Australian Government's payment-terms guidance recommends clear terms, appropriate credit checks and limits before extending trade credit. Those general principles apply to Nigerian SMEs even though specific Australian legal remedies do not automatically apply in Nigeria.
Credit control is therefore the repeatable process of deciding who receives credit, setting limits, recording invoices, monitoring due dates and collecting money professionally.
1. Decide which customers should receive credit
Not every customer needs a pay-later option. Start new or higher-risk buyers on payment before delivery, a deposit, payment on delivery or a small trial credit amount. More established customers with a good payment history may qualify for larger limits or longer terms.
For a business customer, confirm the legal trading name, responsible buyer, billing contact, location, order authorisation, payment process and evidence of past dealings. You can verify corporate details through appropriate official records where necessary. Do not demand excessive personal documents or publish customers' private information; use only checks proportionate to the risk and supported by a lawful basis.
Consider a simple internal rating: low risk (reliable and verified), medium risk (limited history or occasional late payment) and high risk (repeated broken promises, disputed balances or no reliable contact). The rating should guide credit decisions but must be based on actual evidence, not stereotypes or irrelevant personal characteristics.
2. Write payment terms before the goods or service is delivered
Agree the price, deposit, invoice trigger, due date, accepted payment methods, dispute procedure and consequences of non-payment before performing the work. For ongoing supply, record the agreement in a signed contract, purchase order or an appropriately confirmed email. Ensure the customer knows whether “14 days” means from invoice date, delivery or acceptance.
A small-business credit policy might offer:
| Customer or order | Illustrative terms | Control |
|---|---|---|
| First-time buyer | Full payment on delivery | No unsecured credit exposure |
| Custom order | 50% deposit, balance at agreed milestone | Deposit helps fund materials |
| Verified repeat business buyer | 14 days after accepted invoice | Defined credit limit and regular review |
| Large corporate contract | Agreed staged invoices or 30-day terms | Obtain purchase order and billing-process confirmation |
These are illustrative commercial choices, not legally mandated payment periods. The right arrangement depends on bargaining power, profit margin, customer risk and whether the buyer has accepted the agreement. Avoid introducing late fees after a sale without checking the contract and applicable law; do not assume an overseas statutory interest rate applies in Nigeria.
3. Set a credit limit for every approved customer
A payment period controls when the customer should pay. A credit limit controls how much remains at risk. For example, a customer with a ₦300,000 limit already owing ₦250,000 has only ₦50,000 of unused capacity. A new ₦120,000 order would exceed the limit by ₦70,000 before any new payment.
Approve the limit based on available evidence, likely repayment capacity, order frequency and your own cash buffer. Require explicit management approval for exceptions and log who approved them. Review limits when customers consistently pay late or when your business's liquidity deteriorates.
Use a simple control: outstanding invoices + undelivered credit orders + proposed credit sale must remain within the approved exposure limit, using consistent definitions. You can offer a deposit or part-payment rather than rejecting every over-limit order outright.
4. Invoice promptly and remove avoidable reasons for delay
Invoice as soon as your agreement permits. Include the correct customer or entity name, invoice number, date, clear product or service description, amount, applicable tax information, due date, approved bank details and payment reference. Ask in advance whether the corporate buyer requires a purchase-order number, vendor registration or an accounts-payable portal.
The UK's Small Business Commissioner invoicing guide stresses that the person commissioning work may not be the person processing payment; confirm both contacts. This is particularly relevant when supplying Nigerian schools, hotels, offices and larger companies that separate procurement from finance.
Make paying straightforward. Give the customer a valid transfer reference, confirmation route and a secure link or alternative channel where supported. Reconcile bank transfers, POS settlements and payment-provider notifications against invoice numbers; never mark an invoice paid solely because a customer shared an unverified screenshot. FlyingEze's report on FCMB Collect and digital business collections provides related context on payment identification and reconciliation.
5. Create an accounts-receivable ageing report
An accounts-receivable ageing report groups unpaid invoices by how long they have been outstanding. To avoid confusion, this example measures days past the agreed due date, not days since the invoice was created. Keep current invoices separate from overdue ones. A 30-day-old invoice with a 45-day payment term is still current.
Here is a fictional Nigerian business's report as at a chosen review date:
| Customer | Unpaid balance | Days past due | Ageing bucket |
|---|---|---|---|
| A — Retail customer | ₦500,000 | Not yet due | Current |
| B — Event client | ₦250,000 | 12 | 1–30 days |
| C — Distributor | ₦400,000 | 42 | 31–60 days |
| D — Corporate client | ₦150,000 | 75 | 61–90 days |
| Total | ₦1,300,000 | — | — |
Total overdue balances equal ₦800,000 (₦250,000 + ₦400,000 + ₦150,000), or 61.5% of all outstanding receivables in this illustration. This is an internal risk indicator—not a Nigeria-wide industry benchmark. Start by checking the ageing accuracy, disputed items, payment commitments and most consequential exposures; the oldest invoice is not always the one that needs the first call.
6. Use a respectful, consistent payment reminder timetable
Customers sometimes pay late because they did not receive the invoice, the bank details were wrong, approval is delayed or the expected payment date differs from yours. Begin by checking the facts and listening to the customer's explanation.
| Timing | Recommended action |
|---|---|
| 3–5 days before due date | Friendly reminder with invoice, due date and payment reference |
| 1–2 days after due date | Confirm receipt, identify any dispute and request a definite payment date |
| 7 days overdue | Call the agreed billing contact and document the next step |
| 14 days overdue | Escalate internally, consider a written repayment arrangement and review further credit |
| 30+ days overdue | Formal review, documented demand or qualified legal advice as appropriate |
The timetable is a suggested operating process—not a statutory Nigerian collection deadline. Adapt it to the agreed contract, materiality and relationship. The British Business Bank recommends promptly reviewing overdue invoices and keeping communications professional rather than allowing debt to accumulate unnoticed.
A useful reminder says what is owed, which invoice it relates to, when payment was due and how the customer can raise an error. Avoid insulting language, public accusations, repeated harassment or contacting unrelated people. Reserve formal notices for appropriate stages.
7. Respond differently to disputes and genuine cash difficulties
If a customer disputes quantity, quality or an unapproved charge, separate that issue from the portion that is not disputed. Request supporting documents, confirm delivery records and work toward a written resolution. Do not treat a legitimate complaint as deliberate refusal to pay.
When a normally reliable customer has temporary cash difficulties, an instalment agreement may be a better commercial outcome than an indefinite promise. Put the outstanding amount, proposed payments, dates, payment references, responsibility for the undisputed balance and what happens if a scheduled payment is missed in writing. Have both sides acknowledge the arrangement.
For example, a ₦400,000 overdue balance might be repaid as ₦150,000 now, ₦150,000 in two weeks and ₦100,000 after four weeks. These sums reconcile to ₦400,000, but they should be included in the cash forecast only to the extent that receipt is credible. A signed plan improves clarity; it does not transform uncertain payments into guaranteed cash.
8. Protect important customer relationships while enforcing boundaries
Separating service recovery from credit decisions helps avoid arguments. The account manager can listen to the customer and resolve operational issues while a finance lead assesses whether new credit should be approved. Use one current invoice statement and one recorded follow-up owner so customers do not receive conflicting messages from several employees.
For chronic late payers, consider reducing the credit limit, moving to payment on delivery, requesting a deposit or pausing further credit orders where your agreement permits. You may still serve the customer on cash terms. The British Business Bank's cash-culture guidance explicitly discusses cash-on-delivery alternatives for customers who consistently pay slowly.
Do not threaten unlawful action or publicly publish a customer's name or debt details. Nigeria's Data Protection Commission explains that personal information must be processed fairly, lawfully, securely and for appropriate purposes. Keep collection records limited to authorised staff, use secure contact channels and consult qualified advisers about sensitive cases.
9. Connect outstanding invoices to your cash flow forecast
Your business cannot pay bills with the total shown on the ageing report. Forecast receipts in the week you reasonably expect cash to arrive, not automatically in the week each invoice becomes due. Use customer payment history, written commitments and the risk status of each receivable.
Suppose a fictional business has ₦1,800,000 available at the beginning of the week. It expects ₦650,000 in ordinary cash receipts and an additional ₦400,000 from a credit customer, while scheduled payments total ₦2,100,000.
| Cash forecast | Expected payment arrives | ₦400,000 delayed |
|---|---|---|
| Opening cash | ₦1,800,000 | ₦1,800,000 |
| Other receipts | ₦650,000 | ₦650,000 |
| Credit collection | ₦400,000 | ₦0 |
| Planned payments | ₦2,100,000 | ₦2,100,000 |
| Closing cash | ₦750,000 | ₦350,000 |
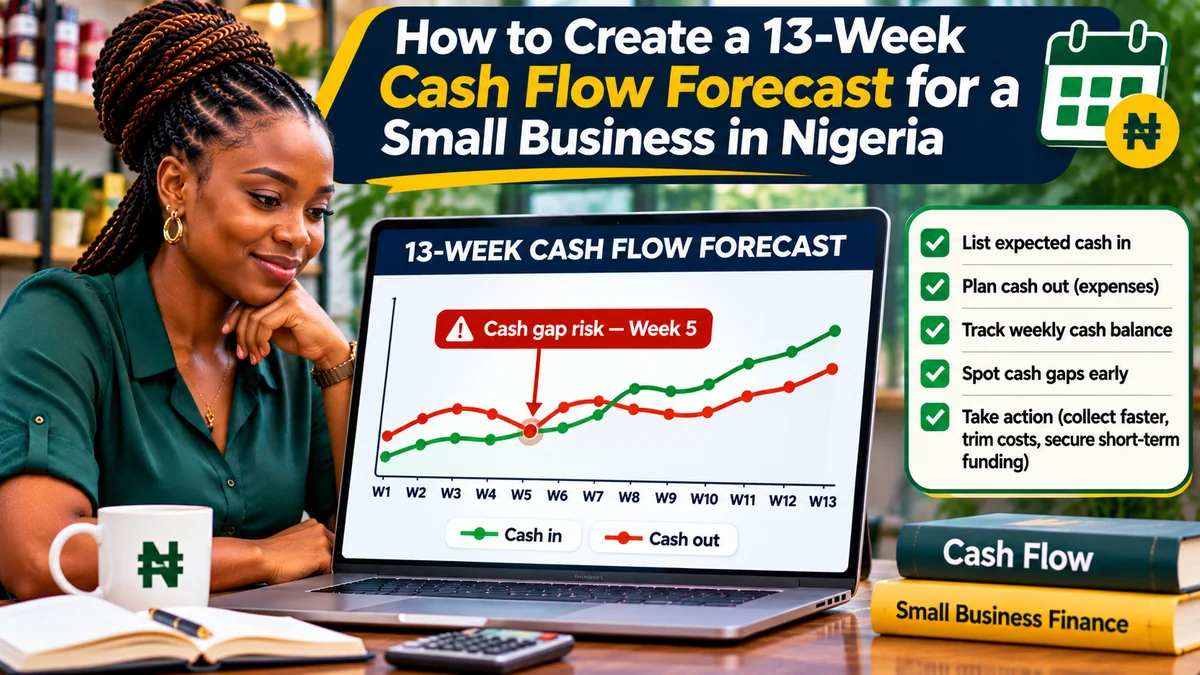
With a management-selected minimum cash buffer of ₦500,000, the delay creates a ₦150,000 gap below the buffer—even though cash is not yet negative. The correct response may be to bring forward reliable collections, reschedule a non-essential purchase or arrange appropriate short-term funding before commitments fall due. Update a rolling 13-week forecast when collection dates change; never silently leave an overdue invoice in the original receipt week.
10. Monitor a few useful credit-control indicators
Review the ageing report at least weekly and track four measures: total overdue naira value, percentage of receivables overdue, promises kept and cash collected against the period's collection plan. Keep a separate log of disputed amounts so staff are not pressured to collect bills that require correction.
For a more mature finance function, estimate days sales outstanding (DSO) using consistent credit-sales and average-receivables figures. A simplified period-based calculation is:
DSO ≈ Average trade receivables ÷ credit sales during the period × number of days in the period.
For instance, ₦1,000,000 average trade receivables divided by ₦3,000,000 credit sales over 30 days gives about 10 days. This is an illustrative measure, not an industry target; compare like periods and consistent VAT treatment. DSO can obscure a small number of very old invoices, which is why it should not replace the actual ageing report.
11. Use software as a control system, not a substitute for decisions
A spreadsheet can work for a small invoice book. Once multiple staff, branches and payment channels are involved, consider tools that capture invoices, due dates, partial settlements, reminders, customer history and audit trails. Reconcile every bank transfer to the correct invoice and restrict who can alter payment statuses or write off balances.
P-Biz Solutions publicly lists customer management, finance, billing and operational capabilities relevant to retail and hospitality workflows. KudiScope focuses on tracking income, expenses, budgets and upcoming commitments, which can support broader liquidity planning. Check the specific functionality available to your business and independently validate any automated receivables or forecasting claims before relying on them.
Neither software platform should decide whether to sue a debtor, charge a penalty or disclose sensitive customer information. Those decisions need appropriate authorisation and, where necessary, qualified professional advice.
When should a Nigerian business consider formal debt recovery?
First confirm the customer identity, contract, evidence of delivery, invoice, due date, payment history and unresolved disputes. Escalate through the agreed process and preserve written communications. For material or persistent unpaid balances, a Nigerian lawyer can advise on a demand letter, negotiation, mediation or appropriate court process and whether any contractual interest or recovery costs are lawfully claimable.
Do not automatically import the UK's statutory late-payment interest rules or an overseas small-claims procedure into a Nigerian commercial contract. The available remedies depend on the facts, applicable law, agreement and forum. Nor should businesses confuse ordinary supplier credit with regulated consumer-lending activities, which can raise additional licensing and compliance questions.
A seven-day credit-control improvement plan
- Day 1: Reconcile customer balances with bank and POS receipts.
- Day 2: Generate a days-past-due ageing report and identify disputed invoices.
- Day 3: Check payment terms, missing purchase orders and invoice contact details.
- Day 4: Send courteous reminders and obtain realistic payment commitments.
- Day 5: Review customer credit limits and deposits for new orders.
- Day 6: Move delayed receipts into the correct cash-flow forecast weeks.
- Day 7: Review collections, unresolved disputes and next week's highest risks.
Then repeat the review weekly. The process works best when sales and finance teams share accurate records and a clear escalation owner, rather than competing over who deserves credit for the sale.
Frequently asked questions
Should small businesses stop offering customer credit entirely?
Not necessarily. Credit can support strong commercial relationships, but it should be selective, documented, limited and monitored. New or higher-risk customers may be better served on deposit or payment-on-delivery terms.
What is the difference between an unpaid invoice and an overdue invoice?
An unpaid invoice may still be within the agreed payment period. It becomes overdue after the due date passes without the required payment. Record ageing consistently from that date.
Can I charge interest automatically when a Nigerian customer pays late?
Do not assume so. The right to charge interest or fees depends on the contract and applicable Nigerian law. Obtain appropriate legal advice before adding penalties, particularly where they were not agreed in advance.
How often should I send payment reminders?
Use a reasonable schedule that reflects the agreement and facts. A reminder before the due date, a courteous follow-up shortly after and a later documented escalation is often more productive than repeated aggressive messages.
Can a partial payment help cash flow?
Yes. A credible upfront instalment can reduce immediate exposure. Record the amount actually received, keep the remaining balance outstanding and reflect future instalments realistically in your forecast.
What should I do if a customer disputes the invoice?
Review delivery, pricing, purchase orders and supporting evidence. Resolve the disputed portion fairly, confirm any undisputed balance and document the agreed next steps.
Conclusion
Healthy customer credit is credit your business can afford to extend and reliably collect. Set fair, written terms; choose credit limits based on evidence; invoice accurately; monitor receivables by days past due; and follow up professionally. If collections slip, adjust the forecast immediately rather than assuming a promise is cash. The result is better customer relationships, fewer avoidable disputes and a stronger ability to pay your own obligations on time.