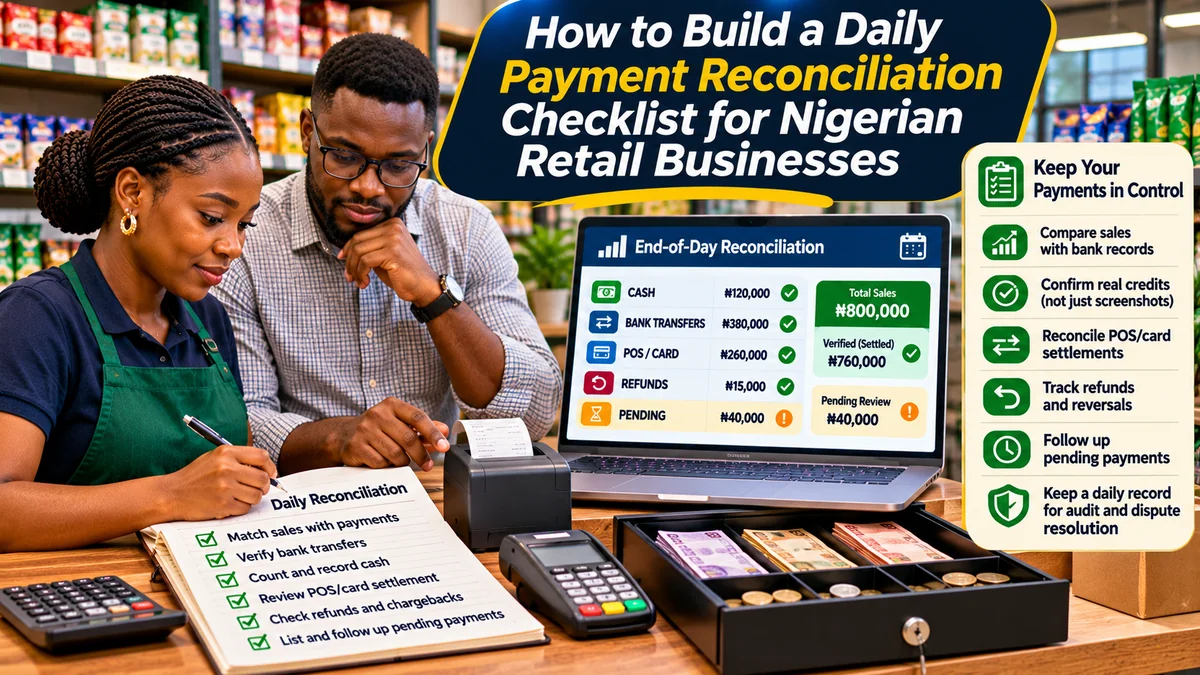
A daily payment reconciliation checklist helps Nigerian retailers confirm that every sale, bank transfer, card/POS payment, cash receipt, refund and outstanding balance is recorded correctly before the business closes for the day. The process is simple in principle: compare the sales register with independent payment records, investigate any difference, and sign off only after the exceptions have been assigned and documented.
Imagine a shop that records ₦1.25 million in customer orders, receives some cash and direct transfers, and collects part of the money through a POS terminal or online gateway. A staff member might mistakenly treat an unverified transfer screenshot as cash received, count a gateway payout twice, or overlook a cash shortfall. Each mistake can distort daily cash and fraud controls even when the sales dashboard looks healthy.
According to the Central Bank of Nigeria's payment-channel overview , internet transfers and POS are important parts of the country's retail payment system. NIBSS reported ₦25.85 billion in digital-payment fraud losses in 2025 , across several fraud categories. These figures are not a measure of reconciliation mistakes alone; they illustrate why independent checks and clear responsibilities matter.
This is an operational guide for supermarkets, shops, pharmacies, restaurants, and small retail chains. It includes a printable daily checklist, a reconciled naira example and an exception log. Research verified 3 November 2026. All store figures are illustrative.
What is daily payment reconciliation?
Payment reconciliation is the process of matching what a business says customers owe or have paid against trustworthy external records of money received and internal records of cash counted. It is different from a sales report: an invoice can exist without being paid, and a payment can be successful before a processor settles the proceeds into the business's bank.
Keep three questions separate: Was the order paid? Where is the money now? Did the business record the payment exactly once? For direct bank transfers, check the business's own bank history. For gateway payments, use authenticated provider transaction records and match later payouts to the merchant's clearing account. For cash, count the notes and coins, then reconcile the expected drawer movement.
Paystack's payout guidance distinguishes customer transactions from subsequent settlement to a bank account and explains that fees and deductions can affect the net payout. A payout must not be counted as a second customer sale.
Set up four records before your first daily closing
Even a small shop needs a sales register, a receipts register, a cash drawer record and an exceptions log. They can live in a single protected spreadsheet or an appropriate POS/accounting platform.
| Record | What belongs in it |
|---|---|
| Sales/orders | Invoice or order ID, date, branch, total, returns or approved discounts, sale status |
| Receipts | Receipt ID, order allocation, channel, confirmed amount, reference, verified date |
| Cash drawer | Opening float, actual cash sales, authorised cash movements, deposits, counted close |
| Exceptions | Unmatched credits, pending receipts, refunds, bank/processor delays, variance, owner, resolution deadline |
Define one trading-day cut-off for the shop, for example 7:00 pm local time. Store timestamps with their timezone, particularly if an integrated platform records times in UTC. Assign branch, till and staff IDs so cash from one cashier is not combined accidentally with another person's shift.
The 12-step daily payment reconciliation checklist
1. Close the sales period and lock the order report
Record the opening and closing time, branch and person responsible. Export the day's sales/orders, including cancelled orders, credit sales, returns, discounts, tax components where applicable, and partially paid invoices. Do not delete a sale because its payment is pending; its status should explain that it remains unpaid or awaiting verification.
2. Collect independent bank and payment-provider records
Obtain incoming transactions from official business banking channels and a merchant transaction report from each processor or POS provider. Paystack documents CSV exports for transactions, payouts, refunds, disputes and other records. Its dashboard guidance describes filtering by date and transaction status before export. Never build the closing report from customer screenshots or debit alerts.
3. Verify direct bank transfers against actual credits
Match each sale marked as paid by transfer with a receiving-side credit. Use the transaction reference, expected amount, available sender information and timing; do not rely on amount alone because two buyers may pay the same sum. If a customer claims a payment but no merchant credit exists, place the order in Payment under review and arrange a fair bank/provider trace without accusing the customer of dishonesty.
4. Match POS/card and online transactions to orders
For each transaction, compare provider reference, order ID, expected amount and successful payment status. The Paystack Verify Payments documentation distinguishes success from pending, failed and reversed. It also warns that an API response's outer status: true only indicates the request succeeded; the payment state is data.status.
Gateway transactions may be legitimately successful even before the net bank settlement arrives. Keep the confirmed customer receipt and later payout as two linked accounting events, not two sales.
5. Calculate gross payments, fees and net payouts separately
Group successful processor collections by payout batch where the provider exposes that information. Compare the gross amount with transaction fees, refunds, chargeback deductions or other provider-supported adjustments, and the expected net settlement. Do not assume a blanket fee percentage—check actual fees on the exported transaction records. Paystack's fee guide explains that processing charges are deducted from transactions before payout.
Paystack's payout detail description shows net payouts, payment composition and deductions. If the payout is expected on a later business day, record a settlement receivable instead of flagging the entire amount as stolen or missing.
6. Count physical cash and reconcile the drawer
Use the formula: expected closing cash = opening float + confirmed cash received − authorised cash paid out − bank deposits/cash transfers out. Compare the result with a physical count and record any overage or shortage.
For higher-value drawers, have the cashier count and a supervisor confirm. Record each petty-cash expense or bank deposit with a receipt or approved movement record. A shortage must not be concealed by changing yesterday's float or inventing a sale.
7. Check refunds, reversals, disputes and chargebacks
Identify completed refunds and unresolved refund requests separately. A refund for a sale made yesterday may reduce today's processor payout without reducing today's gross sales. Link each refund to the original transaction and its approval. Paystack's refund help describes merchant refund records and their status; treatment and eligibility depend on payment channel and provider.
Review disputes and chargebacks as separate exception categories, noting amounts withheld, evidence due dates and outcomes. Do not count a refund or chargeback twice merely because it appears in both a transaction export and a payout adjustment.
8. Identify partial payments and approved customer credit
An invoice worth ₦75,000 with only ₦50,000 confirmed is not fully settled. Record the ₦50,000 receipt and the ₦25,000 balance. Separately identify unpaid orders, customer credit authorised by management, and deposits for future services. Do not force the receipts column to equal all issued invoices when some invoices are correctly outstanding.
9. Investigate duplicate, unidentified and suspicious transactions
Look for the same payment reference applied twice, repeated gateway events, matching credits allocated to multiple orders without documented approval, and credits that belong to no known invoice. Keep unidentified incoming money in an unapplied-credit category until it is identified; it is not automatically an extra sale or profit.
For automated systems, validate webhook signatures and use a unique transaction identifier to prevent duplicate fulfilment. Paystack's webhook documentation describes signed events; its webhook retry help explains why an event can be received more than once.
10. Reconcile supplier payments and other cash outflows separately
Supplier purchases, utility payments, staff advances and owner withdrawals are not negative customer sales. Reconcile them against authorised payment vouchers and bank debits, then categorise them correctly in the cashbook or accounting ledger. Record an owner withdrawal separately from store expenses; otherwise operational profitability and cash records become misleading.
11. Maintain an exception register with owners and deadlines
For every mismatch, record the date, amount, expected record, actual record, evidence, assigned employee, next action and review time. Use statuses such as New, Investigating, Awaiting provider, Resolved and Escalated. An unresolved mismatch can roll into tomorrow's queue, but it must not silently disappear when the next day's worksheet starts.
12. Require sign-off and retain a secure audit trail
Have the cashier or preparer sign the report; use a second reviewer for material amounts or higher-risk branches. Preserve source statements, exports, count sheets and adjustments with access controls. Limit the ability to edit historical reconciliations, and record who changed a status and why. Follow applicable data-protection and retention rules; do not publish customer account details in shared WhatsApp groups or open spreadsheets.
Worked naira example: closing a fictional Nigerian retail shop
The following example is designed to show why sales, collections, net settlements and physical cash must be reconciled separately. Assume one store's order register totals ₦1,250,000 for the day:
| How orders were paid or marked | Amount |
|---|---|
| Confirmed physical cash receipts | ₦260,000 |
| Confirmed direct bank transfers allocated to today's orders | ₦480,000 |
| Successful card/POS and gateway payments (gross) | ₦420,000 |
| Orders awaiting payment or verification | ₦90,000 |
| Total order register | ₦1,250,000 |
The three confirmed collection channels total ₦1,160,000; the other ₦90,000 is outstanding. Therefore, the cashier should not report ₦1,250,000 as confirmed cash received.
Reconcile the processor payout
Suppose successful card/gateway customer payments total ₦420,000 gross. Actual provider fees on those payments total ₦12,000, while a separate ₦20,000 refund from an earlier day's sale is deducted from the same payout batch. The net expected payout is ₦420,000 − ₦12,000 − ₦20,000 = ₦388,000.
The current day's successful customer collections remain ₦420,000 gross. The ₦20,000 refund concerns a prior-period transaction and should be linked to that original sale or liability rather than silently deducted from today's order count. If the ₦388,000 payout will settle tomorrow, record it as expected settlement, not missing cash. A later bank credit of ₦388,000 clears the settlement receivable—it is not a second ₦388,000 sale.
Reconcile direct bank credits and unidentified money
Suppose the business bank statement shows ₦495,000 of incoming direct transfers. Of these, ₦480,000 match today's orders; the remaining ₦15,000 is an unidentified credit, possibly for an earlier invoice. Keep it unapplied while investigating. Do not force the sales register to ₦1,265,000 to absorb the unexplained deposit.
Reconcile physical cash
Assume opening float was ₦50,000; cash receipts were ₦260,000; approved petty-cash spending was ₦30,000; and a documented cash deposit was ₦100,000. Expected closing drawer cash is ₦50,000 + ₦260,000 − ₦30,000 − ₦100,000 = ₦180,000.
If staff count only ₦176,000, the cash shortage is ₦4,000. Record and investigate it separately. The legitimate processor payout delay and the unidentified bank credit do not cancel out that physical cash discrepancy.
| Open issue at close | Amount | Next action |
|---|---|---|
| Unpaid/unverified customer orders | ₦90,000 | Contact buyers and confirm future receipts |
| Processor net payout due | ₦388,000 | Match next payout to clearing account |
| Unidentified bank credit | ₦15,000 | Trace reference and assign to proper account |
| Cash drawer shortage | ₦4,000 | Review cash movements and count evidence |
These are different categories of exceptions. Do not add them together as a single fraud loss or hide one discrepancy with another.
Copy-ready daily reconciliation checklist
Use this simple control sheet at each trading-day close, whether on paper, in Excel/Google Sheets or in a POS system:
| Done? | Daily control | Evidence required |
|---|---|---|
| ☐ | Confirm branch, till, trading date and opening float | Shift log and prior close |
| ☐ | Export sales, returns, unpaid and credit orders | POS/order report |
| ☐ | Match direct bank transfers to invoices | Business bank credits |
| ☐ | Match card/POS/gateway payments to orders | Successful provider transactions |
| ☐ | Reconcile gross charges, fees and expected payouts | Provider settlement report |
| ☐ | Count cash and verify approved cash movements | Signed count and vouchers |
| ☐ | Check refunds, reversals and disputes | Refund/dispute exports |
| ☐ | Identify partial payments and unknown credits | Exceptions log |
| ☐ | Investigate duplicates and unmatched transactions | Reference-level ledger |
| ☐ | Assign unresolved items and follow-up dates | Named owner and deadline |
| ☐ | Save sources and obtain review sign-off | Locked report and approvals |
The checklist should be short enough to complete consistently and detailed enough to reconstruct a transaction during a dispute. A small owner-operated shop may combine preparer and reviewer roles; a chain should use independent review and branch-level controls proportionate to risk.
How to implement the checklist in a spreadsheet
Create four protected sheets: Orders, Receipts, Settlement & Cash, and Exceptions. Use unique transaction and order identifiers rather than matching on amount alone. Standardise the time zone, currency and branch fields. Set a formula to flag orders where confirmed allocated receipts are below the amount due.
Restrict editors, protect formula columns and retain dated versions of each day's closing. For larger businesses, an integrated database should handle simultaneous changes with unique constraints and audit logs; a shared spreadsheet can be overwritten accidentally. Import official bank or provider exports rather than making staff retype hundreds of transactions.
Businesses interested in integrated collection processes can also review FlyingEze's published article on FCMB Collect and digital payment collections . The existing payment tools available to a business should be checked individually rather than assumed to include every reconciliation feature.
When should you automate reconciliation?
Automation is useful when daily volume, multiple branches or repeated manual errors justify the effort. A capable system can import authenticated bank/provider records, match unique references, classify fees and refunds, post settlements to a clearing ledger, and display an exception queue.
Keep separate states for payment initiated, payment successful, net payout scheduled, bank payout received, refunded and disputed. Authenticate incoming webhooks and make event processing idempotent so retries cannot create duplicate sales or refunds. Reconcile provider transactions with bank settlements rather than assuming every webhook means funds have arrived at the bank.
P-Biz Solutions publicly describes inventory and business-management products relevant to retail operations. Verify the specific payments, accounting and branch reconciliation capabilities in the version being evaluated; do not assume all automation or bank-feed integrations are already present.
How to handle discrepancies, fraud suspicion and bank complaints
Begin with investigation, not accusation. A missing credit may reflect network delay, a wrong beneficiary, an unsettled processor payment or an incorrectly matched order. Escalate suspicious patterns to the owner, provider or financial institution promptly with transaction references and relevant evidence.
If the concern is a complaint about a bank's handling of a transaction, the CBN's complaints guidance says to contact the regulated institution first and provides escalation routes for unresolved complaints. The guidance is not a promise that CBN will recover every disputed sale. Suspected active fraud should be reported promptly through appropriate banking and law-enforcement channels, not held back while awaiting a routine month-end review.
Protect customer personal information and avoid posting receipts containing account details in open staff groups. FlyingEze's published report on small-business cybersecurity risks provides related background on account security and staff awareness.
Frequently asked questions
Should a small Nigerian shop reconcile payments every day?
Yes, daily closing is a sensible operating control, especially for businesses accepting cash and transfers. It catches mismatches while staff, customers and transaction details are still available. The precise process can be adapted to scale and risk.
Why does my POS or gateway sales total differ from my bank deposit?
Gross customer transactions can differ from later bank payouts because of processing fees, refunds, disputes, settlement cut-off times and payout schedules. Match the payout report to the underlying transactions before treating the difference as fraud.
Can I count a bank transfer screenshot as a verified payment?
No. Match the transfer to a receiving-side bank credit or an authenticated provider-confirmed successful transaction. A screenshot or sender debit is not independent merchant evidence.
What should I do with an unidentified incoming bank credit?
Record it as unapplied or unidentified, investigate its origin and allocate it only when supported by evidence. It should not be treated as a new sale merely because it increases the bank balance.
How do I treat pending customer transfers?
Keep the order under review and do not mark it paid until verification succeeds. If the customer has been debited, support a trace through official provider channels without automatically demanding a second transfer.
Can a spreadsheet replace accounting software?
A carefully controlled spreadsheet can work for a modest transaction volume. As branches, payment methods and staff access grow, a system with role permissions, audit trails, automated matching and separate settlement ledgers becomes more useful.
Conclusion
Good daily reconciliation is not about making every number look equal; it is about explaining exactly why legitimate records differ. Match orders to verified payments, count cash, distinguish gross collections from net settlements, identify refunds and keep an exception queue with clear ownership.
With this checklist, Nigerian retailers can reduce preventable errors, discover suspicious transactions earlier, and end each trading day knowing which money was collected, which remains outstanding and what must be followed up.