For a Nigerian small or medium-sized enterprise (SME), withholding tax deducted by a customer should usually be recorded as a tax credit—not as a reduction in sales revenue or an ordinary business expense. Where the WHT is creditable, the business recognises its full qualifying income, records the cash actually received and tracks the tax deducted in a separate account such as WHT receivable or income tax paid in advance. It can then reconcile the deduction to a prescribed WHT receipt and apply the credit against its income-tax liability where permitted.
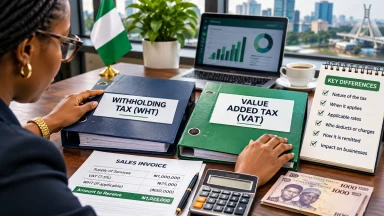
Consider a resident consultancy that invoices ₦1,000,000 for taxable professional services, plus ₦75,000 VAT. A customer deducting 5% WHT from the underlying fee pays ₦1,025,000 to the consultancy and accounts for ₦50,000 in withholding tax. The consultancy should not record ₦1,025,000 as sales revenue: it has ₦1,000,000 of service income, ₦75,000 of output VAT and a ₦50,000 WHT credit or receivable. That distinction protects accurate accounts and tax claims.
This practical guide explains the double-entry journals, monthly reconciliations, credit-note requirements and year-end treatment for Nigerian SMEs in 2026. It assumes the WHT is creditable rather than final tax. Individual circumstances and financial-reporting policies may require professional advice.
What is a withholding tax credit in Nigeria?
Withholding tax (WHT) is tax deducted from specified payments by the person required to make the deduction. In many ordinary business transactions, it serves as an advance payment of the supplier's income tax. The recipient can use properly documented credits against its assessed income-tax liability, subject to the applicable rules.
The Deduction of Tax at Source (Withholding) Regulations, 2024 expressly state in regulation 5 that a deduction is not an extra cost or separate tax added to the contract. Instead, it is an advance or final tax of the supplier. The regulations began applying in January 2025 and should be read with the Nigeria Tax Administration Act, 2025 , which forms part of the 2026 tax-administration framework.
The Lagos State Internal Revenue Service (LIRS) and Taraba State Internal Revenue Service explain that creditable WHT can offset tax assessed when an eligible taxpayer files its returns. Excess qualifying credits may be carried forward or refunded through the prescribed procedures. This does not mean that every deduction is refundable or that WHT is always creditable: some payments attract final WHT.
Why SMEs should not record WHT as an expense or reduce their turnover
Bookkeeping errors typically begin when the accountant looks only at the money arriving in the bank. Suppose a customer approves a ₦1,000,000 service invoice and deducts ₦50,000 WHT before payment. If the SME records only ₦950,000 of revenue, it has understated gross sales by ₦50,000. The missing amount was not a discount: it was tax withheld on the SME's behalf.
For creditable WHT, a practical accrual-accounting treatment is to maintain a separate current-tax asset or prepayment ledger. Names vary between accounting systems—“WHT receivable”, “WHT credit”, “income tax prepayment” or “tax paid at source”—but it should be distinguishable from normal trade receivables and from VAT.
Correct classification also makes it easier to detect a missing credit note, reconcile customers' deductions and show the amount available for an income-tax set-off. It does not automatically establish that every claimed asset will be recovered; recognition and carrying value must reflect the applicable financial-reporting standard, tax treatment and available evidence.
Step-by-step: record WHT on a customer invoice
Assume a Nigerian resident SME supplies qualifying consultancy services to a customer required to deduct WHT, and that the service is standard-rated for VAT. The agreed fee before VAT is ₦1,000,000. The WHT rate is 5%, while VAT is 7.5%. The customer has no separate obligation to withhold VAT in this illustration.
| Line | Calculation | Amount |
|---|---|---|
| Consultancy fee | Agreed service value | ₦1,000,000 |
| Output VAT | 7.5% × ₦1,000,000 | ₦75,000 |
| Total customer invoice | Service fee + VAT | ₦1,075,000 |
| WHT deducted | 5% × ₦1,000,000 | ₦50,000 |
| Cash received | Invoice total − WHT | ₦1,025,000 |
Journal entry 1: issue the full sales invoice
| Account | Debit | Credit |
|---|---|---|
| Trade receivables — Customer A | ₦1,075,000 | — |
| Consultancy revenue | — | ₦1,000,000 |
| Output VAT payable | — | ₦75,000 |
This example uses accrual accounting. Recognise revenue when the relevant revenue-recognition conditions are met, not simply when cash is received. Creating an invoice does not, by itself, prove the customer has already deducted WHT: recognise the WHT asset when the deduction has in fact arisen and the claim is supportable.
Journal entry 2: receive the net payment and recognise the deduction
| Account | Debit | Credit |
|---|---|---|
| Bank | ₦1,025,000 | — |
| WHT receivable / income-tax prepayment | ₦50,000 | — |
| Trade receivables — Customer A | — | ₦1,075,000 |
The journal closes the customer's entire trade debt, even though the bank receives less than the VAT-inclusive invoice. The ₦50,000 is now tracked as tax withheld, rather than as an overdue customer balance or a sales discount. If the customer has merely paid less and has not established a valid tax deduction, do not assume the shortfall is WHT: obtain the remittance details and investigate the difference.
For additional context on the calculations, FlyingEze's earlier guides cover the prescribed WHT categories and the distinction between the tax deducted and the sales price. An accountant should verify the correct percentage, including special exemptions, before posting the credit.
How the customer records WHT payable
A supplier's WHT receivable corresponds to the deducting customer's WHT payable. The same transaction looks different in the books of the two parties.
If Customer A can recover the input VAT, its initial expense/purchase journal for the example may be:
| Customer account | Debit | Credit |
|---|---|---|
| Professional services expense | ₦1,000,000 | — |
| Recoverable input VAT | ₦75,000 | — |
| Trade payables — Supplier | — | ₦1,075,000 |
If the VAT is not recoverable, the purchase/expense accounting must be adjusted under the applicable rules. Upon payment, Customer A debits its trade payable ₦1,075,000, credits bank ₦1,025,000 and credits WHT payable ₦50,000. When it remits the tax, it debits WHT payable and credits bank ₦50,000.
The payer should not treat WHT payable as its own income-tax credit; it is tax withheld from the supplier and owed to the relevant authority. Keeping these accounts separate prevents a business that both receives and makes payments from netting unrelated deductions together.
How to use a WHT credit when recording income tax
At the end of the relevant accounting or assessment period, the SME calculates its income tax according to the applicable law and identifies the confirmed credits available to offset that liability. WHT is a credit against tax, not a subtraction from sales turnover when computing revenue.
Suppose the company's current income-tax liability is ₦300,000, and the ₦50,000 credit in our example is valid, available and accepted for that assessment:
| Income tax settlement | Amount |
|---|---|
| Current income-tax liability | ₦300,000 |
| Less: available WHT credit | −₦50,000 |
| Remaining cash tax payable | ₦250,000 |
First, the company recognises its tax expense and liability as appropriate: debit current income-tax expense ₦300,000; credit current tax payable ₦300,000. Upon using the credit and paying the balance, it debits current tax payable ₦300,000, credits WHT receivable ₦50,000 and credits bank ₦250,000.
That journal settles the liability without expensing the WHT a second time. If income tax has already been recognised or tax payments are accounted for differently under the SME's reporting framework, the accountant should avoid duplicating the expense.
What if tax payable is zero? Do not automatically write off a creditable WHT balance or record a cash refund. Assess whether it remains legally usable, whether a carry-forward or refund claim is available, whether the evidence is sufficient and how recoverability should be presented in the financial statements.
What should a WHT credit register contain?
Even a small business using a spreadsheet should keep a separate transaction-level register linked to its general ledger. Recommended fields include:
| Register field | Example / purpose |
|---|---|
| Invoice and customer reference | INV-2026-014 / Customer A |
| Invoice date and payment date | Separate timing of sale from deduction |
| Gross qualifying fee | ₦1,000,000 excluding separately charged VAT |
| WHT rate and deducted amount | 5%; ₦50,000 |
| Recipient TIN / registration number | Check beneficiary identity and tax records |
| Tax authority | NRS or appropriate state authority |
| WHT receipt / certificate reference | Official or payer-issued evidence and file link |
| Credit period and status | Unconfirmed / supported / claimed / used / disputed |
| Amount used and balance | Track credits not yet offset or recovered |
The total of credits in this register should reconcile to the WHT asset or tax prepayment balance in the general ledger. An ageing view can help distinguish recent deductions from credits that have remained unsupported for months.
More practical bookkeeping guidance is available in FlyingEze's guide to keeping income-tax records .
Which documents prove the WHT credit?
Regulation 8 of the 2024 Withholding Regulations requires the person making a deduction to provide a receipt and statement, with details including the beneficiary's name, address and applicable tax identity; the transaction type; the gross amount; the amount deducted; and the month of payment. The regulations' Third Schedule provides the prescribed format, subject to later authority-specific requirements.
As a minimum, an SME should retain the original invoice, contract or purchase order, bank advice confirming the net payment, customer's WHT remittance/receipt evidence and correspondence resolving any discrepancy. The company's tax ID and the amounts in the receipt should match its records.
If the customer withheld WHT but has not issued a receipt: request the prescribed documentation promptly, retain correspondence and investigate the credit's eligibility and recoverability. A bank statement showing a short payment alone may not establish that the missing amount was legally deducted as WHT.
If the customer issued a prescribed receipt but failed to remit: regulation 8(3) provides that the beneficiary should nevertheless receive the tax credit, while the unremitted deduction becomes a liability recoverable from the withholding agent, with applicable penalties and interest. This is a meaningful protection for suppliers, but keep the valid receipt and associated transaction evidence. Official LIRS guidance can assist with authority-specific questions.
How to reconcile WHT credits every month
- Export sales invoices. List gross service values, VAT and customer names; separate exempt or non-WHT transactions.
- Match receipts. Connect each bank receipt to the relevant invoice, not merely to the customer's name.
- Investigate differences. Confirm whether a short payment is WHT, bank charges, a credit note, a discount or an unpaid debt.
- Post confirmed deductions. Transfer qualifying amounts from trade receivables into WHT receivable, as shown above.
- Collect WHT receipts. Compare the beneficiary information, invoice value, rate, deduction amount and month.
- Reconcile the WHT register. Match the register total to the general ledger and tax-authority records available to the business.
- Review aged credits. Escalate missing receipts and possible incorrect deductions before year-end.
- Prepare tax-return schedules. Group eligible credits by tax period and relevant authority; ensure none is claimed twice.
These practices complement FlyingEze's article on tax record-keeping mistakes Nigerian digital workers should avoid .
Are WHT credits the same as VAT input credits?
No. The two balances must not be combined. WHT receivable normally relates to income tax already deducted on behalf of the recipient. Input VAT relates to eligible VAT paid on business purchases and is treated under separate VAT rules.
In the consultancy example, ₦75,000 is output VAT charged on the invoice, while ₦50,000 is WHT deducted from the service fee. The supplier cannot normally transfer its ₦50,000 WHT credit directly into the input-VAT account. Similarly, a supplier making VAT-exempt services or whose customer is a designated VAT-withholding agent may require different VAT entries.
What if an SME is small, exempt from income tax or has more WHT credits than tax due?
Small-enterprise status and WHT-credit status require different analyses. The 2024 regulations provide conditional relief from the payer's duty to deduct for a qualifying small company or equivalent unincorporated body where the supplier has a valid TIN and the monthly transaction ceiling is ₦2 million. That does not mean a larger customer buying from the SME can never deduct WHT, and it does not make every WHT deduction final or refundable.
If the SME has little or no assessed tax liability but WHT was correctly deducted, review whether the credit can be carried forward or claimed as a refund under the applicable income-tax rules. The Nigeria Tax Administration Act, 2025 (section 55) provides for refunds after review and decisions by the relevant authority, including a possible set-off. The Act's stated 90-day period runs from the authority's decision, not automatically from the date the supplier asks its customer for a WHT receipt; a written refund claim must also satisfy the statutory time limits.
For financial reporting, do not present an uncertain recovery as guaranteed cash. Separate supported claims from amounts under dispute and consider recoverability, possible impairment or derecognition as appropriate to the SME's accounting standards. Where the deduction was a final tax, the usual current-income-tax-credit ledger may not be the correct treatment.
Which WHT rates should SMEs verify?
Correct bookkeeping begins with checking whether the customer used the correct rate. Under the First Schedule to the 2024 regulations, common resident rates include 5% for consultancy, management, technical and professional fees; 2% for qualifying goods supplied by non-manufacturers and some other services; and 10% for rent. Special rules and exemptions, including direct supplies by manufacturers, can change the answer.
Foreign-recipient and certain passive-income transactions may attract final WHT or different rules; a vendor lacking a TIN may face doubled rates on certain non-passive payments. Do not assume the customer is always correct, nor post every invoice's short payment as a tax asset without investigation.
The official LIRS schedule and the gazetted regulations are a more reliable starting point than an old social-media table. Readers can also review common Nigerian income-tax filing mistakes before closing the books.
How should SMEs handle WHT on payments they make to suppliers?
An SME can be both a recipient of WHT credits and a withholding agent for payments made to its own suppliers. The second case creates a WHT payable, not a WHT receivable. If the SME deducts ₦20,000 from a vendor's qualifying invoice, it holds ₦20,000 to remit on behalf of that vendor. It should not offset that amount against credits customers have deducted from the SME without a legally authorised set-off arrangement.
Remittance is generally due by the 21st of the following month for payments to the NRS and, under regulation 7, the 30th of the following month for ordinary state WHT, subject to current authority instructions and applicable special rules. The organisation should give the vendor the prescribed receipt after remittance and keep evidence that the liability was settled. Late remittance exposes the payer to penalties and interest.
Seven bookkeeping mistakes to avoid
- Recording only net bank receipts as sales. Preserve the gross invoiced revenue and recognise WHT separately.
- Debiting a normal expense for creditable WHT. An advance income-tax credit is not simply another operating cost.
- Leaving the entire invoice open as a trade debtor. Once properly withheld, move the WHT element to the tax-credit account.
- Using WHT receivable to reduce VAT payable. Income-tax and VAT credits belong to different regimes.
- Posting assumed deductions without evidence. Confirm why the customer paid less before treating it as recoverable tax.
- Combining WHT payable and WHT receivable. One represents tax the SME owes as an agent; the other is tax withheld from the SME's income.
- Failing to reconcile credits before filing. Missing or duplicate receipts can delay set-off, refunds and audits.
Frequently asked questions
Is withholding tax an expense or an asset in an SME's accounts?
Where WHT is creditable and recoverable, it is normally tracked as an income-tax prepayment or receivable, not as an operating expense. Final WHT and uncertain credits require separate analysis.
Should sales revenue be recorded net of WHT?
No, not merely because the customer has deducted WHT. Record the gross revenue under the applicable revenue-recognition policy, and account for the deducted tax separately.
Can an SME claim WHT without a customer's receipt?
A prescribed withholding-tax receipt is key statutory evidence. Request one, retain the invoice and payment trail, and consult the relevant authority if the customer refuses to provide it.
What if customers deduct more WHT than the SME's final income tax?
Review the applicable carry-forward or refund process and the credit's recoverability. An excess in the accounting register does not itself guarantee an immediate refund.
How do I record WHT deducted from my supplier?
Recognise a WHT payable liability to the tax authority while paying the supplier the appropriately reduced amount. Clear that liability when the SME remits the deduction.
Conclusion
The most important bookkeeping rule is simple: creditable withholding tax is not missing revenue. Nigerian SMEs should recognise their full qualifying income, record the net cash collected, create a distinct WHT-credit balance when the deduction has arisen and is supportable, obtain the prescribed documentation and reconcile credits before claiming them against tax.
In 2026, the 2024 WHT Regulations and the Nigeria Tax Administration Act, 2025 provide the relevant legal backdrop. A disciplined register, correct double-entry journals and timely follow-up with customers can turn a confusing stream of net payments into accounts that are more accurate, easier to audit and better prepared for annual tax filing.
Research verified: 18 November 2026. This article explains general bookkeeping examples and tax provisions, not a substitute for professional tax or accounting advice for a specific business.