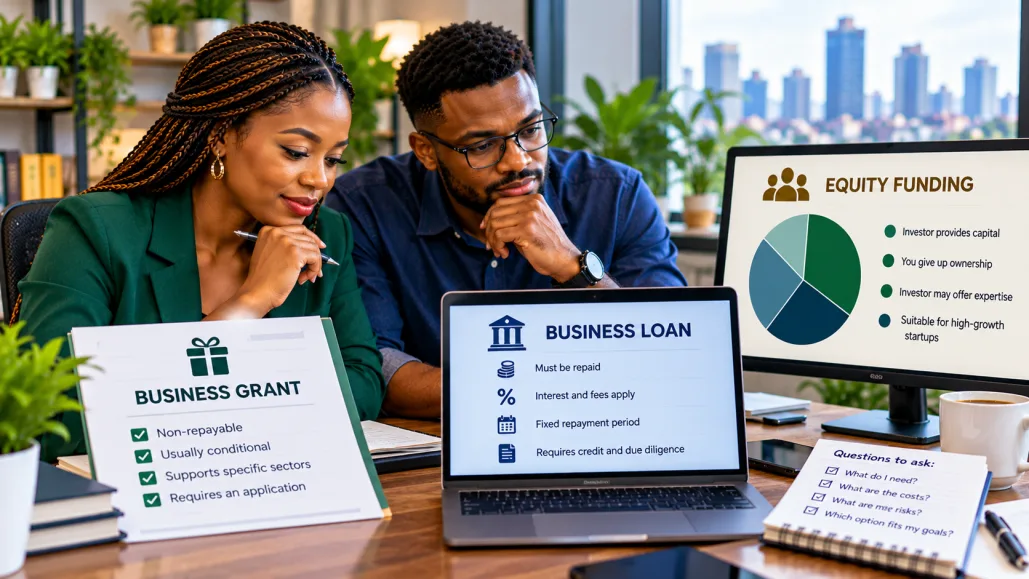
Searching for small business grants in Nigeria can be a sensible first step for a founder who needs capital without monthly repayments. Yet grants are competitive and usually have eligibility and reporting conditions. Loans can finance stock or equipment sooner but require repayment, while equity investment may provide substantial growth capital in exchange for part of the company.
The right funding source depends less on which offer advertises the largest amount and more on what the business needs, when it can generate cash and what the founder is willing to give up. This 2026 guide compares the three options using official Nigerian programme and securities-regulator information, real eligibility examples and clearly labelled financial illustrations.
Grants vs loans vs equity: the differences at a glance
| Question | Grant | Loan | Equity funding |
|---|---|---|---|
| Must the money be repaid? | Usually no, if grant terms are met | Yes, including agreed costs | Not as scheduled debt repayments |
| Does the founder give up ownership? | Usually no | Usually no | Yes, or potentially later under a convertible instrument |
| Main obligation | Eligible spending, milestones and reporting | Cash repayments, security or guarantees | Shareholder rights, governance and possible dilution |
| Often suits | Early validation or targeted social and business programmes | Businesses with predictable repayment capacity | Scalable ventures with high growth potential |
| Main risk | Not winning, delays or breaching conditions | Cash-flow strain and default | Reduced ownership and control |
These are typical structures, not promises. A funding document can combine features, such as a recoverable grant, a convertible loan or an equity round with preferential investor rights. Read its actual legal terms.
1. What is a small business grant?
A grant generally provides funds for an approved purpose without an ordinary repayment schedule. Some funders support youth entrepreneurship, microenterprises, innovation, women-owned ventures or particular sectors. Recipients may still have to complete training, meet milestones, document expenditure or return money if serious conditions are breached.
For example, the Small and Medium Enterprises Development Agency of Nigeria (SMEDAN) Conditional Grant Scheme describes a ₦50,000 grant for eligible microenterprises. Its official programme page also refers to project documentation, monitoring and evaluation. This is a published programme description, not confirmation that a new funding window is open today.
The Tony Elumelu Foundation's 2026 Entrepreneurship Programme announced US$5,000 non-refundable seed funding for successful applicants, alongside training and mentorship. Its annual application cycle began in January and normally closed on 1 March; founders should check future official announcements rather than assume they can apply for that 2026 cohort in October. Its programme guidance explains business documentation and participation requirements before funds are disbursed.
Grant suitability depends on the intended use. A modest award may buy tools, build a prototype or test demand, but it may not finance a large inventory expansion. Do not treat a grant announcement as revenue in a business forecast until funds have actually been approved and received.
2. How business loans work in Nigeria
A loan is borrowed money to be repaid under an agreed schedule, often with interest, fees, security or guarantees. It may be appropriate for a venture with orders, reliable sales and a credible plan to generate the cash needed for instalments. A low advertised interest rate does not make a loan free.
The Federal Government/Bank of Industry MSME intervention FAQ specifically describes its facility as a loan, not a grant. It lists a maximum of ₦1 million per eligible business, 9% annual interest, a three-year repayment period and repayments beginning after a three-month grace period. The scheme requires appropriate CAC documentation, and its route through BOI or partner financial institutions may involve guarantor and other requirements.
That is one programme's published terms, not a universal BOI rate or a promise that the facility is currently accepting applications. The Bank of Industry's broader MSME lending page describes varying products, longer tenors and possible moratorium periods.
Also compare state-level schemes. The Lagos State Employment Trust Fund describes loans for eligible Lagos residents and businesses, with specified rates and local documentation. A founder in another state should not assume eligibility simply because the scheme is advertised online.
3. Read the full borrowing cost, not just the headline rate
Ask for the amount actually disbursed, whether interest is calculated on a reducing balance or another basis, the instalment dates, all processing charges, guarantee obligations and default penalties. The Central Bank of Nigeria's Consumer Protection Framework requires clear disclosure of fees, interest, repayment modalities and relevant contract risks by covered financial institutions.
Imagine a business considering a hypothetical ₦1 million loan to purchase stock. Its sales projection must cover stock replacement, operating expenses, tax obligations and loan repayments—not merely the interest figure. A three-month grace period may delay the first instalment, but it does not cancel the debt. Use the lender's actual amortisation schedule, rather than multiplying an advertised percentage and assuming that gives the final cost.
If the new sales could arrive late or stock may remain unsold, test whether the business can still meet repayments. A founder should not use short-term debt to finance losses indefinitely.
4. What equity funding means for a Nigerian startup
Equity investors provide capital in exchange for ownership shares and associated rights. Unlike a normal loan, equity does not usually require fixed monthly repayments. Investors instead seek a return through eventual dividends, a sale or another liquidity event—and may lose their investment if the startup fails.
Equity can be attractive for technology or other fast-growing ventures that need substantial development spending before profits become predictable. It is less attractive when founders simply need a small amount of short-term working capital and do not want permanent ownership dilution.
Before taking investment, understand the company's valuation, percentage offered, board representation, voting rights, anti-dilution terms, liquidation preferences, founder vesting and exit expectations. These can affect control or proceeds even when the investor owns a minority of ordinary shares.
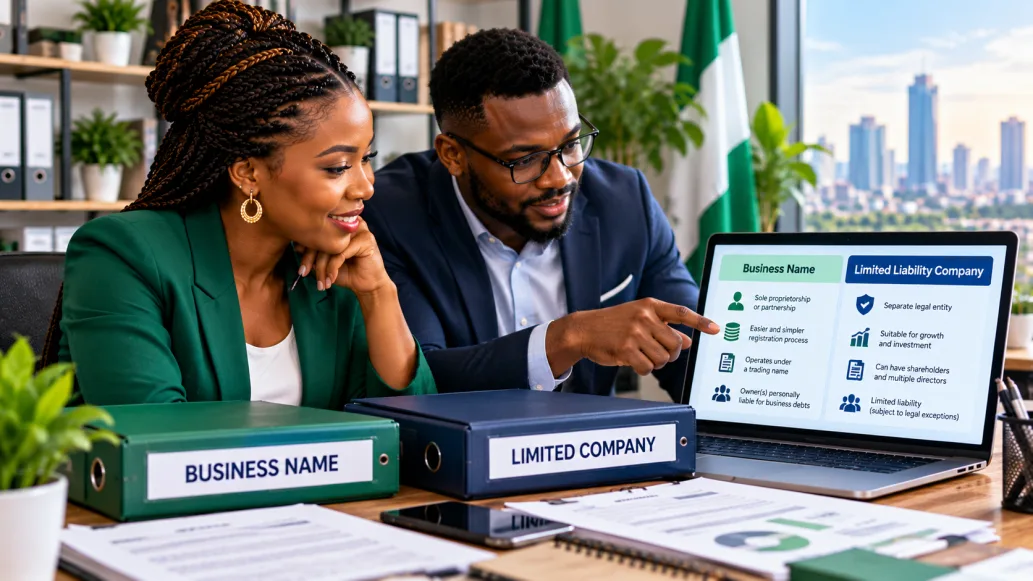
A trading business registered only as a business name cannot issue corporate shares in the same manner as a private company. FlyingEze's comparison of business names and limited companies explains why selecting the right CAC structure matters before approaching investors.
5. Understand dilution with a simple example
Suppose a fictional Nigerian startup is valued at ₦20 million before an investment. An investor contributes ₦5 million for newly issued shares. The illustrative post-money valuation is ₦25 million, meaning the investor receives 20% and existing owners collectively retain 80%, assuming ordinary shares, no outstanding options and no other special adjustments.
The founders do not owe that ₦5 million back as a normal loan. However, they have sold part of the business, and later investment rounds can reduce their percentage further. Valuation terms and special investor rights can change the real economic outcome; this arithmetic is a teaching example, not an offer or valuation recommendation.
6. Equity crowdfunding is regulated—not a free-for-all
Investment-based crowdfunding can allow a qualifying company to raise smaller contributions from multiple investors. But collecting money from the public in exchange for investment returns is not the same as taking donations or selling products in advance.
The Securities and Exchange Commission's crowdfunding rules establish requirements for eligible incorporated fundraisers, intermediaries, investor protection and disclosure. The SEC has warned about unregistered platforms and provides a registered-operator directory .
Before raising or investing money through an online crowdfunding service, check current SEC rules, whether that platform is authorised for the activity and whether the proposed offer is lawful. Private investor transactions may follow different legal processes, so qualified corporate and securities advice is appropriate.
7. Does the Nigeria Startup Act guarantee funding?
No. The Nigeria Startup Act portal describes a startup-labelling framework, ecosystem support and a statutory Startup Investment Seed Fund for eligible technology-enabled businesses. Establishing a fund or an incentive in legislation does not mean every labelled startup automatically receives money.
Founders should check implementation notices, qualification criteria and active application channels before adding such funding to their budgets. Incorporation, record-keeping and credible financial projections remain important for grants, debt and equity alike. For practical compliance preparation, consult FlyingEze's post-CAC registration checklist .
8. Choose funding by need, cash flow and business model
A small clothing retailer with steady repeat sales may benefit from carefully sized inventory credit if profit margins and repayment dates are reliable. Giving away long-term ownership to buy a short-lived stock batch may be unnecessarily costly.
A rural microenterprise needing a machine might reasonably pursue a targeted conditional grant, provided the scheme covers the equipment and the business meets its location and documentation rules.
A software startup developing a new product may prefer equity or suitable grant support during an uncertain research-and-development phase, when loan repayments would begin before dependable revenues exist.
An established service firm expanding to another branch could compare a term loan, a strategic investor or phased self-financing. An investor might contribute industry contacts, while debt may preserve ownership—but only if the firm can service it.
The best choice may be a blend: founder savings and initial sales for validation, a grant for eligible training or equipment, then debt or equity when evidence supports expansion.
9. Prepare a funder-ready application
Grant committees, lenders and investors ask different questions, but all want credible information. Prepare your CAC documents, business description, customer problem, target market, realistic budget, financial records and a clear explanation of what the funding will achieve.
For grants, match every proposed expense to the programme's stated purpose and milestones. For loans, demonstrate a conservative cash-flow forecast and repayment capacity. For equity, explain growth potential, competitive advantage, milestones and exactly what stake and rights may be offered.
If incorporation is still outstanding, FlyingEze's 2026 CAC registration guide explains the official process. Never invent sales, customer commitments or supporting documents to meet a funding threshold.
10. Avoid funding scams and misleading offers
Be sceptical of an individual who guarantees a grant approval after an upfront “release fee”, asks for private banking credentials, advertises a government scheme through an unrelated domain or describes a loan as a non-repayable empowerment package.
Use programme websites linked from SMEDAN , BOI and other verified institutions. Check the institution's legal identity and any relevant regulator, read the offer before paying administrative charges and retain application receipts. Legitimate application conditions can vary, but no credible organisation can guarantee selection in a competitive grant programme.
Frequently asked questions
Are small business grants in Nigeria free money?
They are generally non-repayable when programme conditions are met, but may restrict how money is spent and require training, reporting or verification. Read the award agreement.
Is a BOI MSME intervention a grant?
No. The FGN/BOI intervention FAQ explicitly describes the cited ₦1 million facility as a repayable loan. Other BOI products may have different terms.
Can a startup obtain equity investment without profits?
Possibly. Some investors finance credible high-growth businesses before profitability, but expect evidence of potential, governance and a suitable investment structure.
Can founders combine a grant with a loan or equity?
Sometimes, provided the programme rules, contracts and investor disclosures permit it. Avoid double-funding the same restricted expense or hiding existing obligations.
Internal Linking Recommendations
Startups choosing an investment-ready legal structure should read FlyingEze's business name versus limited company guide . Applicants needing their registration documents can follow its step-by-step CAC registration article . Once registered, the post-registration compliance checklist helps founders organise tax, records, accounts and licences that funders may request.
Final verdict: match the money to the mission
Grants minimise conventional repayment and dilution but require eligibility and patience. Loans preserve ownership but demand reliable cash flow. Equity can support substantial growth without fixed debt instalments, while permanently affecting ownership and governance.
For Nigerian founders, the practical question is not simply “Where can I get money?” but “What can this business responsibly afford to promise in return?” Compare written terms, use verified official channels and choose funding suited to the venture's stage and risk.
Research checked 29 October 2026. Published programme terms do not establish that applications are open today. Funding availability, interest rates and eligibility can change; confirm current documents before applying or accepting an offer.