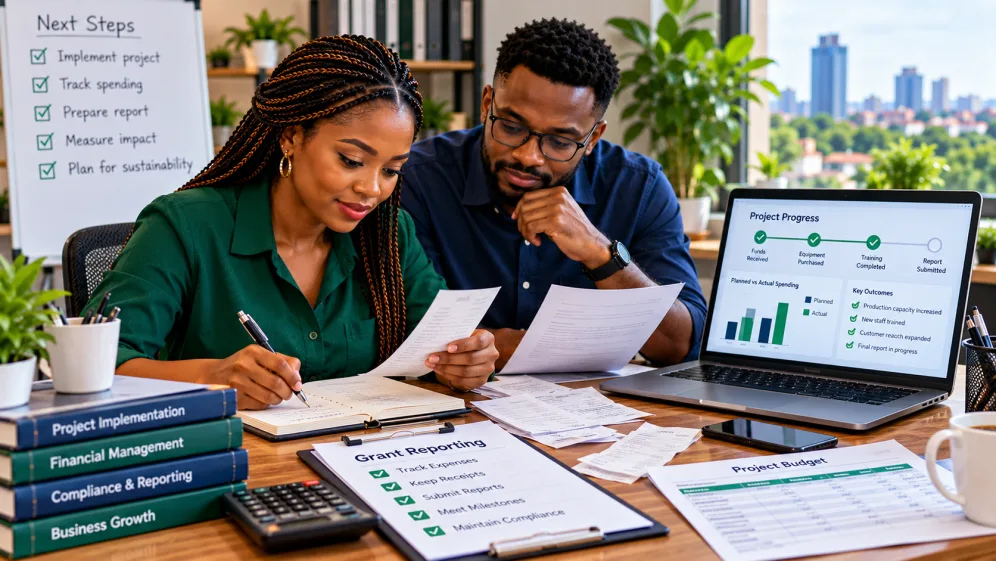
Receiving approval for one of the small business grants in Nigeria can help a founder buy equipment, test a product or expand operations. But the transfer is not necessarily the end of the process. Many funding agreements still require recipients to spend money on approved activities, keep evidence, monitor outcomes and submit reports.
The most important principle is simple: the award agreement determines your obligations. A private foundation, government agency and sector-specific programme may each use different reporting schedules, spending restrictions and repayment clauses. This 2026 guide explains what beneficiaries should do after disbursement, with a fictional financial report and carefully distinguished Nigerian tax and accounting considerations.
What responsibilities begin after receiving a grant?
| Responsibility | Practical action |
|---|---|
| Accept and review the award | Save signed terms, approved activities and reporting dates |
| Control the funds | Maintain a traceable record of grant receipts and expenses |
| Follow the budget | Spend only on eligible items; request changes before reallocating |
| Track project progress | Document outputs, beneficiaries, milestones and delays |
| Prepare financial reports | Reconcile approved budget, actual expenses and balance |
| Assess tax and accounting | Apply relevant 2026 rules and an appropriate reporting standard |
| Close out properly | Submit final evidence and resolve unspent funds as directed |
These are prudent general steps, not a claim that every Nigerian beneficiary must follow the same government-wide grant template.
1. Read the award letter and funding agreement before spending
Confirm the exact amount awarded, legal recipient, project period, permitted purchases, procurement conditions, reporting frequency, audit rights, confidentiality requirements and any provisions for suspension or recovery of funds. Check whether the grant is paid once or in tranches dependent on milestones.
Keep the signed agreement, approval notice, original proposal, approved budget and official correspondence together. If the award differs from the amount requested, update the implementation plan before purchasing equipment. Do not assume a supplier quotation in the original application authorises every later change.
The US Grants.gov post-award guidance describes implementation, financial reporting, progress reporting and closeout as distinct stages. It illustrates general grant-management practice; its US-specific deadlines do not automatically apply in Nigeria.
2. Separate grant spending from ordinary business transactions
Use an account or accounting ledger that clearly identifies the grant receipt and every associated payment. A dedicated bank account may be required by a particular agreement; where it is not, a separate bookkeeping code or cost centre can still make reconciliation easier.
Record the date, supplier, description, amount, payment method, approval and supporting document for every transaction. Avoid personal transfers, unrecorded cash withdrawals and purchases from connected parties without appropriate disclosure or required approval.
Suppose a grant funds sewing equipment. The supplier invoice, payment confirmation and delivery record should explain why money left the account and what was received. This creates an audit trail rather than merely a bank statement showing an outflow.
3. Spend within the approved budget and seek permission for changes
Grant funds are normally provided for defined purposes, not unrestricted withdrawals by the owner. Commonly restricted expenses may include personal consumption, unrelated business ventures, luxury items, non-project travel or assets beyond the grant's permitted scope. The actual list comes from the award, not from a universal prohibition.
If a supplier raises prices or equipment becomes unavailable, document the issue and ask the funder whether a replacement item or budget transfer is allowed. Obtain approval in the format the agreement specifies, preferably with written confirmation you can retain.
Do not quietly move money from staff training to stock purchases just because both expenses seem useful. A commercially sensible change may still breach a restricted grant agreement.
4. Build a simple grant spending ledger
A spreadsheet is sufficient for many small projects if it is complete, access-controlled and backed by source documents. Use a consistent reference number linking each expense to the corresponding invoice and proof of payment.
Recommended columns include date, transaction reference, approved category, item, supplier, budget, actual amount, payment evidence and approval status. Reconcile totals to the bank or payment record monthly, or more frequently if the award requires it.
Separate the cost of equipment from ongoing operating expenses. A grant received into a business account is not automatically profit available for the founder to withdraw.
5. Sample financial report for a fictional Nigerian business
Imagine a hypothetical Enugu clothing workshop awarded ₦500,000 under an invented grant that permits the five categories below. The figures are illustrative, not actual SMEDAN or Tony Elumelu Foundation award terms.
| Approved category | Budget (₦) | Spent (₦) |
|---|---|---|
| Sewing equipment | 200,000 | 185,000 |
| Fabric and materials | 130,000 | 120,000 |
| Skills training | 70,000 | 60,000 |
| Delivery and logistics | 40,000 | 30,000 |
| Approved customer outreach | 60,000 | 30,000 |
| Total | 500,000 | 425,000 |
Unspent balance: ₦75,000. A proper report should explain each material variance and attach supporting evidence. Do not automatically classify the ₦75,000 as business profit, purchase additional items with it or assume it must be refunded immediately. Ask the funder whether to retain, return or use it under an approved amendment.
To accompany this table, record what was actually delivered: for example, one machine installed, one operator trained and documented weekly production. Any claimed increase in sales must come from verifiable customer records, not projections presented as completed results.
6. Report project outcomes as well as expenditure
Financial reporting answers where the money went. Performance reporting answers whether the project achieved its purpose. Depending on the grant, relevant measures might include equipment installed, trainees completing instruction, units produced, jobs sustained, customer orders served or people benefiting from a service.
Choose a baseline, a target, the reporting date and reliable evidence. For example, a workshop could compare weekly production capacity before and after training, while also reporting actual orders separately. Avoid conflating production capacity, actual sales and revenue.
The SMEDAN Conditional Grant Scheme states that beneficiaries may be required to submit periodic reports, undergo evaluations or participate in monitoring. Its public page does not impose one specific reporting timetable on every recipient. Follow your own award instructions.
7. Do not confuse a non-repayable grant with an unconditional payment
The Tony Elumelu Foundation's 2026 announcement describes its US$5,000 seed capital as non-refundable for successful entrepreneurs. That describes the funding model, not permission to misrepresent facts or ignore any agreement conditions.
A grant contract may allow recovery if money was obtained through fraud, spent on prohibited items, or if specific conditions are not met. Other projects may permit modifications or have no ordinary repayment obligation at all. Do not claim that every beneficiary must repay money after an unsuccessful project; assess the exact contract and relevant law.
Likewise, a government-supported loan still carries debt obligations. FlyingEze's grants, loans and equity comparison explains the differences.
8. Are business grants taxable in Nigeria in 2026?
Never assume a grant is automatically tax-free. Section 4(1)(h) of the Nigeria Tax Act 2025 expressly includes “grants” among the categories of income, profits or gains potentially chargeable to tax. The Act took effect in 2026 under the Federal Government's transition guidance .
However, identifying a potentially taxable receipt is not the same as calculating tax payable. The result depends on the recipient's legal form, the nature and source of the grant, applicable exemptions, recognised expenses, taxable-profit rules and any relevant incentive. Companies, sole proprietors and charitable organisations may have different outcomes.
Keep the award letter, grant ledger, equipment invoices and spending evidence for the accountant or tax adviser. Ask the appropriate Nigeria Revenue Service or state revenue authority how the particular receipt should be reported. A non-repayable award is not a substitute for tax filing or normal business records.
9. Record the grant correctly in financial statements
Accounting recognition may differ from bank-cash movements. For entities using full IFRS, IAS 20 addresses government grants: recognition requires reasonable assurance of compliance and receipt, and income is generally matched systematically with related costs. Grants relating to assets can have a different presentation from grants supporting expenses.
Do not assume that IAS 20 automatically governs every private-foundation donation or every small enterprise's financial reporting. The applicable framework, grant characteristics and entity circumstances matter. A qualified accountant can determine whether and when to recognise grant income, deferred amounts, assets and expenses.
Accurate accounting also makes it easier to demonstrate whether the enterprise bought an asset, reimbursed an eligible cost or still holds funds subject to conditions.
10. Prepare for monitoring visits, reviews and audits
A funder may request proof that equipment exists, training occurred or spending matches approved categories. Keep invoices, photographs taken with appropriate permission, delivery notes, timesheets, relevant attendance registers and records of amendments.
Do not fabricate receipts or stage photographs. Equally, do not publish workers' identification documents or customer details just to demonstrate success. Nigeria's Data Protection Commission
The grantor may audit or inspect depending on the agreement. Cooperate through verified contacts and retain records for the contractual and applicable legal periods; do not adopt a foreign grant programme's retention period as a universal Nigerian rule.
11. Handle delays, shortfalls and unspent funds transparently
Projects rarely unfold exactly as forecast. If a machine arrives late, costs rise or projected demand falls, inform the grant officer through the approved channel, describe the reason and request guidance. Record the revised plan and any permitted extension.
Near the project end, reconcile the budget, submit the required financial and performance reports and obtain confirmation of what happens to unused money and purchased assets. Final reporting does not necessarily mean the funder has formally closed the award.
General Grants.gov guidance illustrates why final financial and project reports, outstanding issues and asset rules form part of grant closeout; use your Nigerian grant agreement for actual deadlines and obligations.
A practical 30-day grant-management plan
- Days 1–3: Review and file the agreement, confirm the amount received, approved budget and reporting calendar.
- Days 4–7: Create a grant-specific ledger, assign purchasing approval and verify suppliers.
- Days 8–14: Make eligible purchases, retain receipts and log actual delivery or training.
- Days 15–21: Compare budget to actual expenditure and project targets; flag discrepancies promptly.
- Days 22–30: Draft the first report if due, reconcile balances and clarify any change or unspent money.
These are suggested management checkpoints, not universal statutory or grant deadlines.
Frequently asked questions
Can I use grant money for personal expenses?
Only if a particular award expressly permits the relevant expense. Most project grants restrict spending to approved purposes. Review the agreement before making withdrawals.
Must every Nigerian grant recipient submit monthly reports?
No. Requirements differ by programme. Some require periodic reports, final reports or monitoring; others have simpler procedures. Use the funder's official timetable.
What happens if I do not spend the full grant?
The agreement controls whether unused money must be returned, retained pending approval or redirected to another approved activity. Ask before reallocating it.
Is a non-refundable grant free from income tax?
Not necessarily. Nigeria's 2025 Tax Act expressly mentions grants among potentially chargeable receipts. Actual treatment depends on recipient and transaction circumstances, exemptions and applicable tax rules.
Internal Linking Recommendations
For preparation before an award, see FlyingEze's small-business grant document checklist . The grant-proposal writing guide shows how initial targets, budgets and milestones should be constructed; that article is scheduled to publish before this one. The funding-model comparison distinguishes grant conditions from loan repayments and equity commitments. These resources provide context; the present guide focuses on responsibilities after receipt.
Conclusion
Receiving a business grant creates an opportunity—and often accountability. For founders benefiting from small business grants in Nigeria, the strongest approach is to understand the award terms, preserve traceable financial records, measure real outcomes, report honestly and resolve unused funds with the provider.
Financial discipline protects more than a single award. It improves decision-making, credibility with future funders and the ability to explain how support translated into business progress. Treat the grant as a project with measurable responsibilities, not an unexpected windfall.
Research verified 30 October 2026. This is general educational guidance, not individual tax, legal or accounting advice. Grant conditions and reporting schedules are programme-specific.