
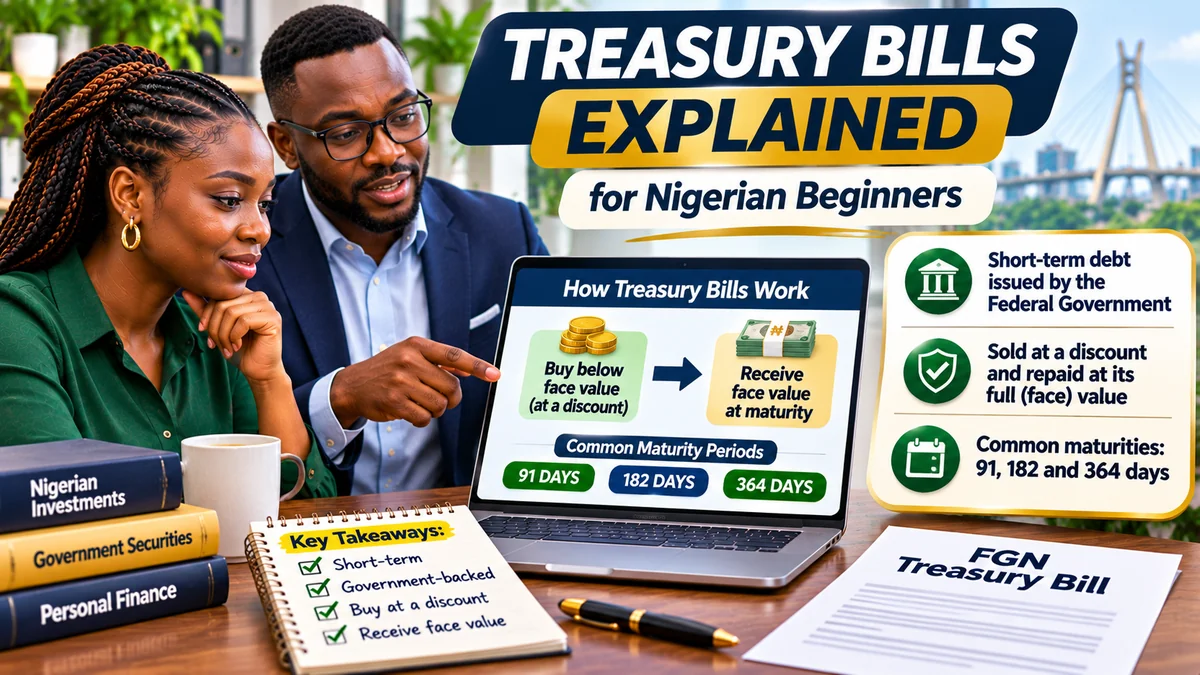
Treasury bills are short-term loans investors make to the Federal Government of Nigeria, usually for 91, 182 or 364 days. They are sold below their face value and normally repaid at that full face value when they mature. The difference between what you pay and what you receive is the investment's gross return, before any applicable taxes and fees.
If you want someone to explain treasury bills without complicated banking language, imagine paying ₦96,000 for a government promise to repay ₦100,000 on an agreed future date. Your potential ₦4,000 gross gain comes from buying the security at a discount, not from receiving monthly interest. The exact purchase price, tax treatment and maturity depend on the actual transaction.
For Nigerians saving toward school fees, rent, an emergency reserve or a business expense, Treasury bills can offer a relatively low-credit-risk option for money with a planned future use. But they are not cash in a savings account, and selling before maturity can cause a loss. This guide covers how they work, the meaning of discount rates and yields, where beginners can buy them, the 2026 minimum-investment rules, taxation and the questions to ask an authorised dealer. Research checked: 16 November 2026.
What exactly is a Treasury bill?
A Nigerian Treasury Bill (NTB), often called a T-bill, is a short-term Federal Government debt security. The Central Bank of Nigeria (CBN) issues and auctions these instruments on behalf of the Federal Government, working through the government's debt-management framework. When you buy one, you are effectively lending money for a specified period.
Unlike many conventional bonds, a Treasury bill is a discount instrument. It generally does not pay a separate monthly or quarterly coupon. Instead, it is bought for less than its maturity or face value, and the difference represents the gross interest income. FirstBank's Treasury bill guide describes the same discounted purchase and repayment-at-par structure.
Because the Federal Government is the issuer, the credit risk is generally regarded as low relative to many private investments. That does not remove inflation, market-price, intermediary, reinvestment or other risks. Nor does it make any app advertising “government-backed returns” a genuine seller of Treasury bills.
What are the 91-day, 182-day and 364-day Treasury bills?
The standard Nigerian primary-market tenors are:
| Tenor | Approximate duration | Why an investor might consider it |
|---|---|---|
| 91 days | About three months | Money needed relatively soon, with a known maturity date |
| 182 days | About six months | A savings goal due around the middle of the year |
| 364 days | About one year | Money that can remain invested for most of a year |
The CBN's Nigerian Treasury Bills auction page records recent sales for all three tenors. Choosing a longer maturity does not automatically guarantee a higher rate. What matters is the actual discount or yield available and whether the maturity date suits your plans.
If you buy an already-issued bill through the secondary market, its remaining time to maturity may be a different number of days. A bill originally issued for 364 days might have only 100 days left when a new investor buys it.
How Treasury bills make money: discount price, face value and yield
Three terms help explain Treasury bills correctly:
- Face value: The amount the government is scheduled to repay at maturity, such as ₦100,000.
- Discount or purchase price: The amount you pay now to acquire that face value. It is lower when buying a new bill at a positive discount.
- Gross return: Face value minus the purchase price, before charges and taxes if held to maturity.
For example, if you buy a ₦100,000 face-value Treasury bill for ₦96,000 and hold it to maturity, your gross gain is ₦4,000. Your return measured on the actual ₦96,000 invested is about 4.17% for that holding period—not 4% merely because you earned ₦4,000 on a ₦100,000 face value.
That is why the auction discount rate should not be confused with the annualised investment yield. A discount rate is commonly expressed as a percentage of face value using a day-count convention; the true holding-period yield instead compares earnings with your purchase cost.
Worked example: a 91-day bill with ₦100,000 face value
Consider a purely hypothetical 15% annual discount rate on a 91-day Nigerian Treasury bill with a ₦100,000 face value. These are teaching figures, not a live investment quote. The following calculation uses a 365-day basis to make the arithmetic transparent:
Purchase price = Face value × [1 − (discount rate × days / 365)]
Purchase price = ₦100,000 × [1 − (0.15 × 91 / 365)] = ₦96,260.27.
If you hold the bill until it matures, the government is scheduled to repay its ₦100,000 face value. The difference is a ₦3,739.73 gross discount gain, before taxes and fees.
| Illustrative item | Amount |
|---|---|
| Face value at maturity | ₦100,000.00 |
| Hypothetical annual discount rate | 15.00% |
| Time to maturity | 91 days |
| Purchase price | ₦96,260.27 |
| Gross gain at maturity | ₦3,739.73 |
| Gross holding-period return on cost | About 3.89% over 91 days |
| Simple annualised yield on cost | About 15.58% before tax and charges |
| Illustrative 10% withholding on gross gain | ₦373.97 |
| Illustrative gain after that withholding, before fees | ₦3,365.75 |
The last two rows illustrate the published withholding-tax treatment, assuming that rate applies to the payment and disregarding other charges. Your exact tax position and settlement method should be confirmed with the dealer and a qualified tax adviser. A 15% annual discount is not a promise that you will earn 15% cash profit in 91 days.
Dealers may quote an annual discount rate, an annualised yield or a net-of-fees return. Ask which measure is being displayed and request the exact cash you must pay today, face amount, maturity date and expected net maturity proceeds.
What were Nigerian Treasury bill rates in late 2026?
Rates change at each auction and in the secondary market. The CBN's government-securities summary , checked on 16 November 2026, displayed the following rates for its 28 October 2026 NTB auction:
| Security | CBN-listed marginal rate | Maturity date |
|---|---|---|
| 91-day Treasury bill | 15.40% | 28 January 2027 |
| 182-day Treasury bill | 15.79% | 29 April 2027 |
| 364-day Treasury bill | 15.80% | 28 October 2027 |
These figures are historical auction observations, not guaranteed rates offered to readers today. The published page's last displayed entry is not proof that there have been no subsequent auctions, and a bank's secondary-market quote may differ. Check the auction date, whether the figure is a discount or yield, and any tax and transaction costs before comparing products.
The CBN key-rates page also publishes labelled NTB rate observations. Do not treat a quoted 364-day rate as a guaranteed return across every bank or investing app.
How do you buy Treasury bills in Nigeria?
There are two principal markets and a third, indirect investing route.
1. Primary market: new bills sold by auction
In the primary market, authorised dealers submit bids for newly issued government bills through the CBN's auction process. Eligible clients arrange participation through a bank or other authorised money-market dealer. Auctions can be oversubscribed, so submitting a bid does not guarantee a full allotment or acceptance at your requested rate.
Importantly, the 2026 primary-auction minimum is very different from the small minimum sometimes quoted in old tutorials. A CBN tender notice for the September 2026 auction, reproduced by Public Procurement NG , specified a minimum bid of ₦50,001,000 in ₦1,000 increments. Stanbic IBTC's Treasury bill product page confirms the same primary-market minimum.
Some older general CBN FAQ content still mentions ₦10,000. Because that information conflicts with the specific 2026 auction notices, the newer auction terms and the dealer's current written instructions should take priority for an actual auction bid. A dealer may offer access through a different arrangement, but do not claim that every retail investor can place an individual primary-auction bid for ₦10,000.
2. Secondary market: buy bills that already exist
In the secondary market, banks, authorised dealers and brokers may sell Treasury bills that were issued previously. The price is negotiated or quoted using prevailing market conditions and remaining time to maturity. An individual investor may find smaller minimum purchase amounts here.
For example, Stanbic IBTC currently describes a ₦100,000 minimum for its secondary-market Treasury bill offering, with purchases in ₦10,000 increments thereafter. That is a provider-specific minimum, not a single national minimum for all investment apps and dealers.
Ask the dealer to state the face value, cash settlement price, true yield to maturity, commission, custody charge and redemption process in writing. Some dealer pages include service charges and value-added tax on applicable fees, which affect the net result.
3. Indirect route: a regulated money market fund
A money market mutual fund may invest part of its portfolio in Treasury bills and other eligible short-term instruments. Buying fund units is not the same as directly owning one specific Treasury bill: the fund manager selects securities, and the investor bears the fund's expenses and rules on subscriptions, redemptions and valuation.
The SEC's registered-operator directory
Step-by-step checklist for a first Treasury bill purchase
- Choose a genuine savings goal and date. Determine when you must spend the funds. Money needed next week should not be locked in a 364-day bill without planning for early-sale risk.
- Decide the amount you can leave invested. Keep enough accessible cash for emergencies, transport, essentials and near-term commitments.
- Choose primary or secondary access. Confirm the latest auction minimum or the selected dealer's current retail minimum. Do not confuse a pooled fund with direct ownership of NTBs.
- Verify the actual institution. Begin at an established bank's verified website or check a capital-market operator's legal name and permission. Do not rely exclusively on an influencer or WhatsApp link.
- Request the full quote. Ask for the tenor, issue and maturity dates, face value, discount rate versus yield, cash cost, fees, tax handling, and expected maturity proceeds.
- Complete the authorised account checks. Banks and dealers may request identity, contact and other KYC details through secure processes. Never share an OTP with an unrelated person claiming to be a CBN officer.
- Place the actual purchase or bid. Follow the dealer's authenticated instructions, obtain the allotment or trade confirmation and verify that the transaction was recorded.
- Keep statements and set a maturity reminder. Check the repayment destination and decide whether to spend, save or reinvest at the rates available then.
Access, minimum amounts and fees vary between institutions. No particular private bank or app named here is endorsed or recommended as the best option for every investor.
Can you withdraw your Treasury bill money before maturity?
You can generally ask an authorised dealer about selling an existing bill in the secondary market before its maturity date. But this is a sale at a market price, not an automatic no-penalty withdrawal from a bank account. The price depends on the remaining maturity, current rates, dealer spread and market conditions.
If market yields rise after you buy a fixed-return security, the value of an existing bill may fall. If yields decline, its price may rise. In either case, dealing costs can reduce proceeds. You could receive less than your purchase amount if you must sell early, even though a government bill held to maturity has a predetermined face-value repayment.
Before investing, tell your provider the exact date the money may be required. A nearer-maturity bill may suit that date better than the longest available tenor.
Are Treasury bills safe? Understand the real risks
Treasury bills are generally considered among the lower-credit-risk naira investments because repayment is an obligation of the Federal Government. The CBN's government-securities guidance describes their sovereign backing and market liquidity. But a government security should not be promoted as completely risk-free for every financial goal.
| Risk | What it means for a beginner |
|---|---|
| Inflation risk | Food, rent and transport prices may rise faster than your after-tax investment return |
| Early-sale price risk | You may lose money if you need to sell before maturity at an unfavourable market price |
| Reinvestment risk | When a short bill matures, the rate available for a new bill could be lower |
| Liquidity and dealing costs | A secondary buyer and attractive quote may not be available immediately; spreads and charges matter |
| Intermediary and fraud risk | An app or agent may misrepresent the product, ownership, rates or payment destination |
| Sovereign and policy risk | Government backing greatly affects credit risk but does not erase every possible default or policy disruption |
To understand why a positive nominal return can still feel inadequate when prices are rising, FlyingEze's explanation of Nigerian inflation and living costs provides useful context. Compare the after-tax, after-fee return with the costs you expect to face over the same period.
How are Treasury bill earnings taxed in Nigeria in 2026?
Do not assume Treasury bill income is tax-free. On 1 July 2025, the SEC issued a circular noting the expiry of an older exemption for certain short-term government securities and possible applicable withholding-tax obligations. Subsequently, Nigeria's tax authority directed financial institutions to withhold 10% on income from specified short-term securities, including Treasury bills, as reported by Reuters on 28 October 2025 .
The withholding concerns the income element, not a general 10% tax on the whole face value. The treatment of the deduction as a tax credit or final tax, and any further obligations, can depend on the investor and the applicable law. The tax rules are also not identical for NTBs, FGN bonds and CBN OMO bills, so the products should not be casually grouped together.
Ask your dealer for a written calculation showing the gross discount income, tax deducted, fees and the net amount you are expected to receive. This article is not a substitute for advice on your own tax situation.
Treasury bills vs fixed deposits, FGN bonds and money market funds
| Product | How returns are earned | Useful distinction |
|---|---|---|
| Direct Treasury bill | Generally purchased below face value and redeemed at face value at maturity | Specified maturity and government credit; early sale exposes market-price risk |
| Bank fixed deposit | Interest under a bank deposit contract | Bank product with deposit terms and applicable NDIC coverage rules for eligible deposits |
| FGN bond or savings bond | Typically coupon interest over a longer period under the issue terms | Different maturity, payout schedule and market-price risks |
| Money market mutual fund | Return from a portfolio of short-term instruments, after expenses | You hold units in the fund rather than one particular Treasury bill |
| Ordinary savings account | Bank interest and account services under deposit terms | Generally more convenient for frequent access, but rates and conditions differ |
The Debt Management Office's FGN bond guide explains longer-term government bonds and their coupon obligations. A Treasury bill has different cash flows and typically a shorter maturity. Compare the product's genuine risk, required holding period and net proceeds rather than focusing only on the advertised annual percentage.
Common beginner mistakes to avoid
- Confusing a discount rate with the realised yield. Ask what percentage is based on face value, purchase price and the actual number of days.
- Thinking a 364-day quotation applies to every bill. Each issue and secondary-market trade can have a different price and remaining duration.
- Relying on an outdated ₦10,000 auction minimum. The 2026 primary tender terms show a much higher direct-bid minimum; individual secondary dealers may offer smaller purchases.
- Believing interest is always tax-free. Consider the short-term securities withholding-tax rules and compare net returns.
- Investing emergency money without a liquidity plan. A bill may be sold early, but not necessarily at your preferred price.
- Confusing a money-market fund with direct T-bill ownership. Read what the product actually buys and the fund's rules.
- Sending funds to an unverified “government agent”. Confirm the bank or authorised dealer and official payment process.
If a suspicious agent has already received money, see FlyingEze's guide to responding after paying a suspected fraudulent account . The CBN phishing warning is another reminder not to disclose sensitive banking credentials through unverified links.
Frequently asked questions
What is a Treasury bill in simple terms?
It is a short-term loan to the Federal Government of Nigeria. An investor typically buys the bill for less than its face value and is scheduled to receive the face value when it matures. The difference is the gross income, before any taxes and charges.
How long do Nigerian Treasury bills last?
New standard Nigerian Treasury bills are commonly issued for 91, 182 and 364 days. A previously issued bill bought in the secondary market may have fewer days remaining.
How much money do I need to buy Treasury bills?
It depends on the route. Specific 2026 primary-auction notices set a ₦50,001,000 bid minimum, while individual banks and other dealers may offer smaller secondary-market purchases. Stanbic IBTC's current secondary-market product page states ₦100,000. Check the actual provider's rules.
Can I invest ₦10,000 in Treasury bills?
Not as a standalone bid under the cited 2026 primary-auction minimum. Some retail intermediaries or funds may offer smaller balances, but the investment could be a pooled product rather than directly held Treasury bills. Confirm the legal product and current minimum first.
What is the Treasury bill rate in Nigeria today?
There is no single fixed “today” rate for every Treasury bill. The CBN's page checked for this article displayed marginal rates of 15.40%, 15.79% and 15.80% for the 91-, 182- and 364-day issues at its 28 October 2026 auction. These are dated observations, not live offers or guaranteed future rates.
Do I earn interest monthly?
Usually no. Nigerian Treasury bills are discount instruments rather than monthly-coupon securities. The discount is reflected in the purchase price, with the face value scheduled to be repaid at maturity.
Can Treasury bills lose money?
They have relatively low sovereign credit risk when held to maturity, but selling early can create a price loss. Inflation, fees, tax and reinvestment rates can also weaken your financial outcome.
Are Treasury bill returns tax-free?
Do not assume so. Nigerian authorities introduced withholding-tax treatment for specified short-term securities in 2025, including Treasury bill income. Ask the intermediary about the relevant deduction and obtain advice for your tax circumstances.
What happens when my Treasury bill matures?
The security is scheduled to repay its face value through the relevant account or settlement arrangement, subject to applicable withholding and any outstanding settlement procedures. You may decide to use the money or purchase a new investment at the rates then available.
Which is better: a Treasury bill or a money market fund?
Neither is always better. A direct bill has a specified maturity and government credit exposure; a money market fund provides exposure through a pooled portfolio and its redemption rules. Compare minimum amounts, access, fees, taxation and what is actually held.
Who should consider Treasury bills?
They may suit someone with a definite future spending date, sufficient accessible emergency savings and a preference for lower-credit-risk naira securities. Whether they are suitable depends on personal circumstances and a realistic comparison of net return, inflation and liquidity.
Final beginner checklist
- I understand the difference between face value, purchase price, discount rate and yield.
- I know the real maturity date and do not need to sell early unless I accept price risk.
- I have verified the dealer and whether I am buying a direct Treasury bill or fund units.
- I checked the current minimum amount rather than relying on old auction rules.
- I requested a written quote for the cash cost, gross return, taxes and every fee.
- I can independently obtain a trade or allotment confirmation.
- I know the settlement account, expected repayment process and whom to contact if something goes wrong.
Conclusion: understand the price, not just the headline rate
Nigerian Treasury bills offer a straightforward concept: lend to the Federal Government for a relatively short period by buying a security at a discount and receiving its face value at maturity. The important decisions are the actual cash purchase price, time to maturity, available access route, expected after-tax income and whether you can afford to keep the money invested.
For beginners, the safest next step is to request an itemised Treasury bill quote from an independently verified institution and compare it with the official CBN auction information. If you understand what you pay, what you own, when it matures and what could reduce your return, you are much better placed to decide whether a Treasury bill suits your goal.



