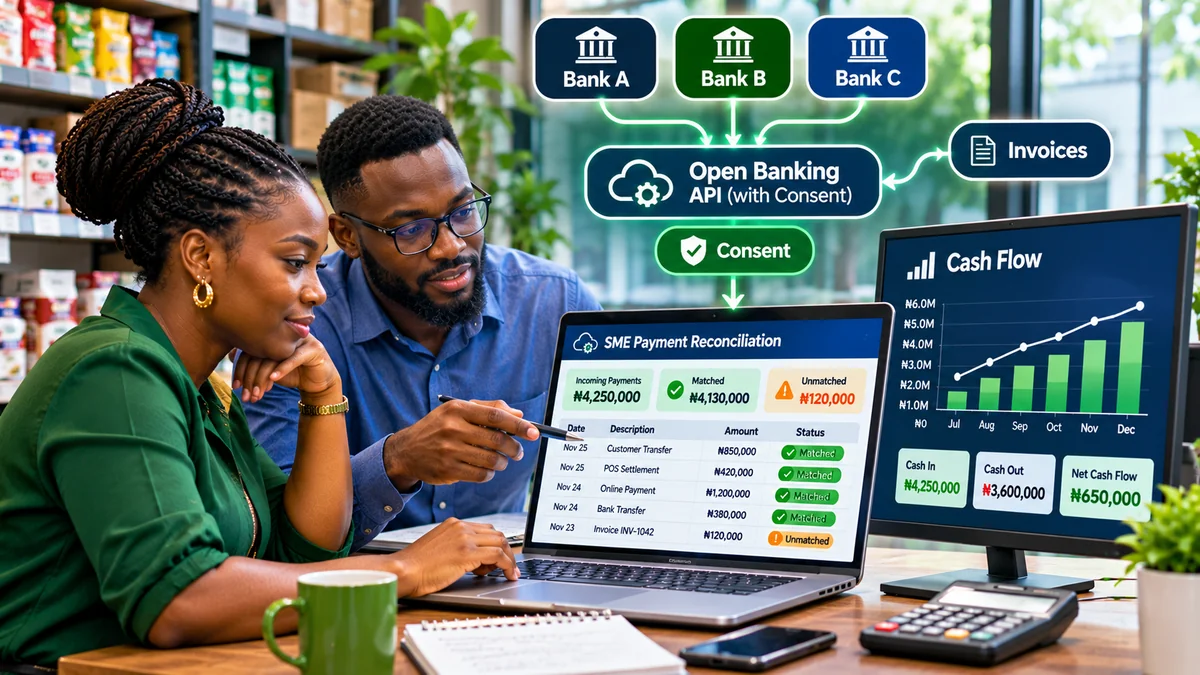
Open banking APIs could help Nigerian small and medium-sized enterprises (SMEs) reconcile payments and track cash flow by securely connecting permissioned bank-account information to their invoices, sales records and financial dashboards. Instead of repeatedly downloading bank statements from different institutions, an authorised system could retrieve transaction data, match genuine incoming credits to customers and identify unexplained payments for staff to investigate.
The potential is significant for a retailer with several bank accounts, an online shop using a payment gateway or a service provider waiting for invoice payments. However, the benefits depend on participating banks, available APIs, customer permission, accurate source records and the business's own financial controls. Open banking is not a magic payment-verification service, and a bank-data connection does not guarantee that a transfer will settle.
The Central Bank of Nigeria (CBN) issued the Operational Guidelines for Open Banking in Nigeria on 7 March 2023. Those guidelines establish a framework for customer-permissioned data sharing, participant oversight, API security and consent management. As of the research verification date, a fully confirmed nationwide production launch and universal access across Nigerian banks could not be established. The industry group Open Banking Nigeria reported in its July 2026 update that the original 1 August 2025 go-live target did not materialise; businesses should check each bank and provider's actual supported integrations rather than assume the national network is universally live.
This guide explains what the technology could do, what an SME can implement today through existing services, and how to avoid mistakes when combining bank balances, processor payouts and financial forecasts. Research verified 3 November 2026; all examples are illustrative.
What is open banking in Nigeria?
Open banking is a regulated approach to sharing specified financial information or services through application programming interfaces (APIs), under appropriate customer permissions and security controls. An API lets one approved computer system exchange structured information with another. Rather than giving a bookkeeper unrestricted access to online banking passwords, a business could grant an authorised service a defined permission to read relevant account information for a limited period.
Under the CBN framework, an API Provider makes data or services available; an API Consumer accesses them under the permitted arrangement; and the customer controls permission for data relating to them. The guidelines envisage an Open Banking Registry for oversight and require compliance with security, operational and data governance standards.
These roles are broader than simply a fintech connecting to a bank. Depending on what they do, other businesses may participate in permitted categories. But using an ordinary accounting application to view one's own bank transactions does not automatically make every retailer a regulated direct open-banking participant. A small business can often obtain practical benefits through an appropriately authorised provider rather than building a bank API network itself.
What is the state of open banking adoption in 2026?
It is important to separate regulatory authorisation, technical standards and production availability. The CBN's framework dates to 2021 and its operational guidelines to 2023. Open Banking Nigeria has published API specification and consent-flow materials , but standards documentation is not proof that a particular bank supports live connections for a chosen SME application.
The CBN's 2025 Fintech Report, released in 2026 describes continuing API fragmentation and implementation gaps. Open Banking Nigeria's July 2026 status update says workstreams had prepared governance, technical and security documents while the market awaited further direction. These findings make an important practical distinction: some firms already offer their own bank integrations or transaction feeds, but nationwide standardised interoperability should not be represented as complete without updated regulator and provider confirmation.
Before buying a product, ask whether its connection is a live bank-approved API, a payment-provider integration, an imported statement or a future open-banking feature. Ask exactly which Nigerian banks, accounts and data fields are covered.
1. Bring business account transactions into one place
A typical Nigerian SME may use one bank for customer collections, another for suppliers and a separate merchant account for online sales. Staff can spend hours checking statements and typing deposits into a spreadsheet. With authorised access to those business accounts, a data integration could standardise incoming and outgoing transactions into one dashboard.
That dashboard might show transaction date, account, amount, debit or credit direction, narrative, available reference and retrieval time. Each source record should retain a stable institution or transaction identifier where provided. The system should also show the last successful sync; a balance that has not updated for several hours must not be described as live.
Account aggregation alone does not reconcile sales. It simply provides bank-side evidence that can be compared with the invoices and other records already held by the business.
2. Match bank credits against invoices and customer orders
Suppose a wholesale shop creates invoice INV-1042 for ₦185,000. A customer claims to have transferred the funds. A properly configured reconciliation workflow would look for a receiving-side credit, compare the amount and available identifiers, then link that record to INV-1042.
If the incoming payment lacks an invoice reference, the system may propose a possible match using amount, timing and payer details, but it should not silently mark the invoice paid where there is material ambiguity. Two customers can send identical amounts, and a bank narrative can be incomplete. A cashier or accountant must review uncertain matches.
For payment-gateway transactions, the seller should check the provider's authenticated payment status. Paystack's Verify Payments guide distinguishes the successful API request from a transaction's own data.status. An open-banking transaction feed could complement this evidence, but it should not replace the payment provider's merchant-side verification where that is the relevant collection workflow.
3. Avoid counting gateway settlements twice
A successful customer card or transfer charge handled by a payment processor may create a merchant receivable before the net proceeds are paid to the retailer's bank. The later settlement is a movement of money already recorded, not a second sale.
For example, if an online shop receives ₦600,000 in verified gateway payments and incurs ₦12,000 of actual processing fees, it may expect a ₦588,000 net payout, assuming no other deductions. When the ₦588,000 reaches its bank, the accounting system should clear the processor receivable and record the fee appropriately, not add ₦588,000 to revenue again.
Open banking account data could help verify that the payout arrived and match it to a settlement record. The gateway remains the authoritative source for the underlying approved customer payments, fees, refunds or disputes. This separation matters for credible profitability and cash-flow reports.
Worked example: reconciling a fictional Nigerian shop's daily collections
Consider a shop with ₦2,500,000 in orders recorded during a trading day. Its customer collection records show:
| Order status or channel | Amount |
|---|---|
| Cash received and counted | ₦350,000 |
| Direct bank credits matched to invoices | ₦1,420,000 |
| Successful payment-gateway charges, gross | ₦600,000 |
| Unpaid or still-unverified orders | ₦130,000 |
| Total recorded orders | ₦2,500,000 |
Verified customer collections total ₦2,370,000. However, the receiving bank's daily transaction data shows ₦1,500,000 of direct incoming transfers: ₦1,420,000 matched to the day's invoices and ₦80,000 still unidentified. The unmatched ₦80,000 must be investigated, not invented as a new sale to make the books balance.
Assume the gateway's ₦600,000 in charges will generate a net payout of ₦588,000 tomorrow after ₦12,000 in actual fees. That money may be a provider settlement receivable today, not cash already in the company's bank. Cash on hand is ₦350,000, while bank-side credits associated with today's direct customer orders are ₦1,420,000; additional statement balances and outflows must be reconciled before calculating total available cash.
An integrated dashboard could surface the four separate items: ₦130,000 in outstanding customer orders, ₦80,000 in unidentified direct credits, ₦588,000 awaiting processor settlement, and any bank transactions not yet reflected in the internal ledger. This is more useful than one unsupported figure labelled “money received”. The amounts are fictional and illustrate control design, not the demonstrated performance of a live Nigerian open-banking product.
4. Improve day-to-day cash-flow visibility
Cash flow concerns actual and expected movements of money, not merely the value of invoices issued. Consent-based bank data could give owners a more timely picture of cash across multiple accounts, helping them see whether they can cover wages, supplier orders and other commitments.
A good dashboard should distinguish available bank cash, physical cash, processor funds awaiting payout, unpaid customer invoices and upcoming bills. Those categories have different levels of certainty. A sale on credit cannot pay tomorrow's electricity bill unless the customer pays in time.
For planning, combine confirmed balances with scheduled commitments and conservative estimates of future receipts. A 13-week forecast can show weekly opening cash, expected collections, operating payments and closing cash. The API can feed observed transactions into that model, but it cannot know when every debtor will actually pay or prevent an unexpected expense.
5. Detect cash-flow anomalies and reconcile more frequently
More frequent transaction data could help a business spot duplicate incoming credits, unusually large supplier payments, unidentified deposits, unexpected account fees and failed collection patterns sooner than a monthly statement review.
However, a repeated transaction in an API response may be a retry or duplicate data record rather than a second bank movement. The system must deduplicate safely using source identifiers and preserve the original records. A reversal or refund should link back to the originating payment instead of creating misleading revenue changes.
Alerts should prompt investigation, not automatically declare fraud. A confirmed bank movement can still be disputed or subject to other adjustments, and an account data feed cannot prove a customer's intent.
How would a secure SME open-banking integration work?
A practical architecture would include the business bank or approved data source, a consent and authentication layer, a secure integration service, a transaction-matching engine, an accounting ledger and a dashboard. The steps are straightforward in concept:
- The business owner identifies which accounts and information the software genuinely needs.
- A participating bank or authorised provider presents the permitted access request and obtains the required permission through an approved authentication process.
- The integration securely retrieves only the approved data and records the data source, access scope and last sync time.
- Transactions are normalised and compared with invoices, payment-provider events and ledger entries.
- High-confidence matches are recorded under defined controls; uncertain items are sent to an exception queue for human review.
- The dashboard updates verified receipts, unpaid invoices, cash balances and forecast assumptions without duplicating accounting entries.
The CBN framework includes a registry and participant accreditation requirements. Its operational guidance addresses API access, reconciliation controls, security and business continuity. Any entity providing regulated services should obtain legal and technical advice about which licences, participant responsibilities and contractual arrangements apply to its actual role.
Customer permission, privacy and security are essential
Open banking does not authorise a startup to collect customers' banking passwords or freely inspect their accounts. The CBN's customer-experience standards require explicit, informed and time-bound permission, a clear purpose, authentication and a means of refusing or revoking access. The user should know which information is requested, why, and for how long.
The Nigeria Data Protection Act, 2023 also sets requirements around lawful processing, transparency, minimisation, security and data-subject rights. An open-banking consent flow does not erase the need to assess the relevant data-protection obligations. Nor should a business assume that permission to retrieve bank transactions allows it to reuse personal financial information for unrelated advertising or profiling.
Choose providers that can explain encryption, access controls, audit logs, breach procedures and token revocation. Use least-privilege access for staff and protect API credentials on secure servers. Avoid screen scraping that asks employees to hand over full online banking credentials without a defensible security basis. Review retention periods and what happens to data after a connection is revoked.
If a business uses financial information belonging to a customer rather than its own company accounts, obtain the appropriate customer permission for the specific use. Never confuse access to a business collection account with unrestricted access to customers' personal banking histories.
How open banking differs from an ordinary payment gateway
| Capability | Typical payment gateway | Permissioned bank-data integration |
|---|---|---|
| Accept customer payments | Core function where supported | Not inherently a checkout processor |
| Confirm a gateway transaction | Merchant dashboard, verified API or webhook | May complement, not replace, provider records |
| Read authorised account transactions | Only where separately supported | Potential core use case |
| Bring together several bank accounts | Depends on product | Potential account-aggregation benefit |
| Reconcile invoices and bank records | Some services support matching | Possible when paired with invoice/accounting data |
| Forecast future cash flow | Not inherent | Requires additional forecasting logic and assumptions |
The word “open” does not mean all bank accounts become accessible to any app. Nor does an API connection itself move funds. Payment initiation is a separate service capability with additional permission and security requirements.
What can Nigerian SMEs implement before a nationwide rollout?
Businesses need not postpone basic reconciliation improvements. Start by using existing bank business portals, verified bank statement exports, payment-gateway webhooks and virtual collection references where supported. An ordinary daily reconciliation worksheet can already match invoice totals to bank deposits, cash counted, gateway charges and expected settlements.
FlyingEze's published overview of FCMB Collect and organised business collections illustrates the value of clear collection records. The next improvement is an exception queue showing unidentified credits, partial payments, duplicates and delayed payout batches. An account aggregation tool may later automate the import step, but the internal controls remain necessary.
For retail and hospitality businesses, integrated inventory, invoice and sales records can make payment matching more useful. P-Biz Solutions publicly lists business-management products; confirm their specific live payment, banking and accounting integrations before assuming they include nationwide open-banking connectivity.
What should a business ask an open-banking provider?
Ask for the exact list of participating banks and supported account types, whether the connection is live or a pilot, how frequently transactions refresh, whether historical data is available, and which fields are supplied. Request written terms describing fees, failed connection handling, uptime, data retention, consent revocation and incident reporting.
Also ask whether the integration is read-only, whether it can initiate payments, how account owners approve permission, and what registration or sponsorship structure applies to the provider. A demonstration screen showing three fictional banks is not evidence of production access to all Nigerian financial institutions.
Check that the product offers exportable reconciliation records and a manual fallback. If the API is unavailable during business hours, staff should be able to preserve orders and verify actual transfers through the bank's own authenticated channels.
A 30-day readiness plan for Nigerian SMEs
- Week 1 — Map the money: list business accounts, POS providers, gateways, invoice systems, branch cash tills and payout calendars; identify where payment records are currently duplicated.
- Week 2 — Clean records: give every invoice a unique ID, reconcile outstanding payments, and establish rules for unknown credits, refunds and partial payments.
- Week 3 — Test integrations: review available bank or gateway feeds, inspect provider security and consent controls, and trial imports on non-sensitive or properly authorised records.
- Week 4 — Measure the benefit: compare matching accuracy, staff time, unexplained balances, delayed settlement visibility and total costs against the previous manual process.
Do not automate irreversible fulfilment or money movement merely because a proposed match is above an arbitrary confidence score. Start with human review for unresolved items, particularly high-value transfers.
What are the main costs and limitations?
Possible costs include provider subscriptions, connection fees, engineering work, accounting integration, compliance support, employee training and incident response. The principal limitations include incomplete bank coverage, outages, inconsistent transaction descriptions, delayed data, consent expiration and the risk of exposing sensitive financial information.
A small shop with one account and a handful of daily transfers might gain little from an expensive API subscription. A multi-branch business operating across several banks may benefit much more. Compare costs with measured reductions in reconciliation hours, duplicate posting, unallocated payments and cash-flow surprises; do not invent a guaranteed return on investment.
Importantly, open-banking data access is not the same as a credit guarantee, payment finality guarantee, loan approval or licence to offer financial services. The benefits depend on disciplined accounting and authorised provider operations.
Frequently asked questions
Is open banking already live at every Nigerian bank?
No universal availability was confirmed in the sources reviewed on 3 November 2026. The CBN framework exists, but rollout and implementation remain uneven. Ask each provider for verified, currently supported bank connections.
Can open banking prevent fake transfer alerts?
Receiving-side bank records could help a merchant verify a genuine incoming credit, but they cannot guarantee zero fraud. A customer's screenshot still should not be treated as payment proof, and uncertain or stale feeds require independent checks.
Can an SME use open banking without building its own API?
Potentially, yes, through a service with the necessary live bank access and compliant arrangements. Check its role, authorisations, supported accounts and contract terms.
Does the customer have to share a banking password?
A secure consent-based approach should not require handing an application unrestricted banking credentials. The CBN framework describes specific permission, authentication and access controls.
Does open banking automatically calculate profit or cash flow?
No. Bank transactions are inputs, not a complete income statement. The system must still incorporate invoices, fees, expenses, refunds, unpaid obligations and accounting classifications.
Is open banking the same as Paystack or a POS terminal?
No. Payment processors accept or confirm payments through their own channels. Open-banking APIs are about authorised data or services between participants, and may complement existing payment systems.
Conclusion
Open banking could make Nigerian SME finance more connected, but the real value comes from trustworthy reconciliation rather than an API connection alone. With valid permission and reliable data, businesses could bring account transactions together, match credits to invoices, monitor settlements and build clearer cash-flow forecasts. Until coverage and rollout are confirmed for a given provider, SMEs should continue using authenticated banking records, payment-provider verification and disciplined daily reconciliation.
Start by fixing invoice references, recording every transaction once and separating paid orders from funds still awaiting settlement. Those controls remain useful whether an SME uses spreadsheets, an existing payment provider or a future fully interoperable open-banking connection.