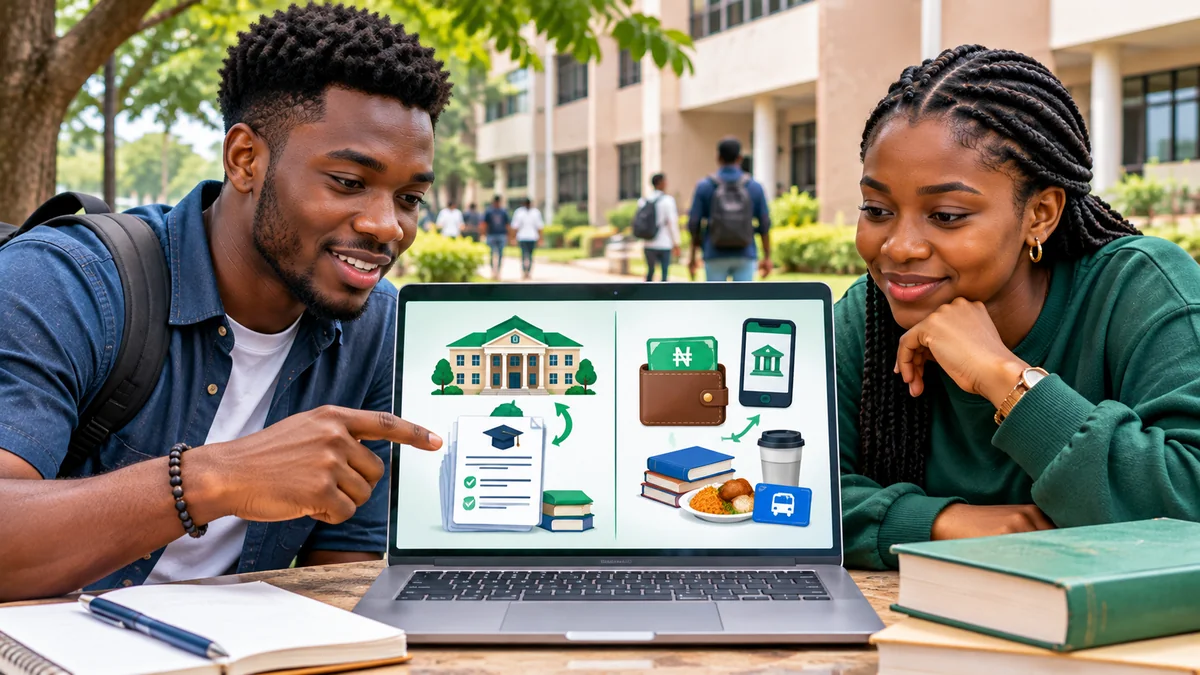
NELFUND Institutional Charges vs Upkeep Loans: What Nigerian Students Should Understand
A Nigerian student applying for the NELFUND student loan in the 2026/2027 academic session may see two different types of support: institutional charges and upkeep. They are not interchangeable. Institutional charges are approved education-related fees paid directly to the student's institution, while an approved upkeep loan is paid to the student's nominated bank account to help meet living costs during the eligible academic session.
The most important distinction is where the money goes, how it is approved and what the borrower must repay. An upkeep credit does not mean school fees have been settled, and an institutional payment to the university does not mean the student has received living-cost support. Both are loan obligations, not automatic gifts.
This guide explains how the two components work, the latest verified ₦20,000 monthly upkeep figure, session-based payment rules, common disputes and what to check before accepting a 2026/2027 loan. Information verified: 6 November 2026. Applicants should confirm their personal eligibility and live loan terms at the official NELFUND website and application portal .
Institutional charges vs upkeep: the difference at a glance
NELFUND's official loan terms identify loan amounts separately in institutional-fee and/or upkeep fields. The scheme's application explanation says verified institutional charges go to the institution, while approved upkeep payments go to the bank account supplied by the student.
| Question | Institutional charges loan | Upkeep loan |
|---|---|---|
| What is it for? | Approved institutional fees associated with eligible study | Living and study-related day-to-day expenses during an eligible session |
| Who receives the money? | The eligible university, polytechnic or college | The approved student's nominated bank account |
| How is the amount decided? | Institutional charges must be verified against the school's records | The approved monthly amount and eligible payment period apply |
| Payment pattern | Disbursement to the institution following approval and verification | Generally instalments during the eligible academic session |
| Can the student spend it freely? | No: the institution receives the fee payment | The student manages received upkeep for permitted personal needs |
| Is it repayable? | Yes, under the applicable loan agreement | Yes, under the applicable loan agreement |
This distinction also explains why one student might see fees recorded as paid while another checks their account for a monthly upkeep instalment. They are different disbursement events and should be tracked separately.
1. What counts as NELFUND institutional charges?
Institutional charges refer to the eligible fees verified for the student's school, programme and academic session. These may be described differently across institutions—for example, tuition or approved obligatory charges—but students should not assume that every fee, hostel bill, departmental levy or personal expense will be included automatically.
The Federal Ministry of Information's account of NELFUND fee reforms explains why clear fee descriptions and standardised verification matter. A ministerial committee recommended harmonised institutional-charge categories, timely verification and transparent reconciliation so that students, schools and NELFUND can identify what a payment actually covers.
Before applying, check the charges published by your institution for the correct session, level and course. If a fee shown in the student-loan dashboard differs from the school portal, speak to the institution's bursary or NELFUND desk before making assumptions. You cannot fix a university's official fee upload simply by inventing an amount in your own form.
FlyingEze previously reported on NELFUND's call for institutions to verify and upload student records . Fee accuracy and enrolment verification are both part of that institutional responsibility.
2. What is the NELFUND upkeep loan?
Upkeep is the separate personal-support component, intended to help eligible students manage ordinary living costs while studying. Examples may include meals, commuting, basic learning materials and other day-to-day needs. It is not a second tuition payment and should not be confused with money remitted to the school's bursary.
In a 30 March 2026 statement reported by the News Agency of Nigeria , NELFUND said the approved monthly upkeep amount remained ₦20,000, rebutting claims that it had risen to ₦25,000. That was the latest directly verified national rate found for this article. It should not be presented as a guaranteed, unchangeable figure for every later payment: students should check any newer official announcement and their approved dashboard.
FlyingEze's earlier report on the supposed upkeep increase provides useful background. The important point for students is that ₦20,000 refers to a monthly upkeep loan instalment, not the total amount NELFUND pays towards their institutional charges.
3. Can students choose institutional charges without upkeep?
Yes, according to a 2025 clarification published by the Nigeria Anti-Littering Trust Fund's government site , students can take the institutional-charges component without requesting monthly upkeep. The current public loan terms also refer to verified amounts under institutional fees and/or upkeep.
Applicants should examine the components offered in their own portal session and only request what they understand and need. Do not assume upkeep will automatically appear merely because your institutional fees were approved. Equally, do not assume all combinations or eligibility categories are available in the same way to every student. Follow the live portal's instructions and seek official clarification where a choice is unclear.
4. How long does monthly upkeep continue?
The most consequential policy change for planning is that upkeep disbursements are tied to the institution's academic session. NELFUND announced in August 2025 that payments for a particular session should cease when that session ends and that students advancing to the next academic year need to reapply for the relevant new session.
The National Universities Commission's reproduction of NELFUND's clarification says the change addresses differing academic calendars and duplicate upkeep payments. Students whose applications are rejected because the relevant session has closed may need to apply under their new academic session after resolving outstanding issues.
Do not calculate annual upkeep automatically as ₦20,000 × 12 months. The number of eligible instalments depends on the applicable session, approval and disbursement rules, not just twelve calendar months. Payment timing can also be affected by institution-uploaded academic calendars, bank-account issues or verification delays.
For personal budgeting, treat a pending instalment as not yet received. Avoid borrowing from a private lender or making an irreversible financial commitment on the assumption that NELFUND will pay on a fixed day every month.
5. A worked example: two separate amounts, one repayment responsibility
Consider a hypothetical eligible student whose verified institutional charges for a session are ₦120,000. Suppose that student also receives an approved upkeep loan of ₦20,000 per month for six eligible months.
| Illustrative component | Calculation | Recipient |
|---|---|---|
| Institutional charges | ₦120,000 | Institution |
| Upkeep actually disbursed | 6 × ₦20,000 = ₦120,000 | Student's bank account |
| Total received on the student's behalf | ₦240,000 | Split across the two recipients |
This is a teaching example, not a promise that six months or a ₦120,000 school-fee amount applies to any real student. The student would not receive the entire ₦240,000 personally. Under the public loan terms, the borrower remains responsible for amounts paid both to the school on their behalf and to their own account.
This illustrates why students should track institutional and upkeep disbursements separately while also understanding their combined borrowing position.
6. What happens if you paid school fees before NELFUND sent the money?
Some students pay fees to meet registration deadlines before NELFUND finishes its approval and disbursement process. If the Fund later pays the same verified charge on the student's behalf, the institution needs to reconcile the payment and determine the proper refund or credit under its procedure.
The Obafemi Awolowo University's November 2025 notice provides an example: it told eligible new students who had made required partial payments that those amounts would be refunded after NELFUND credited the university with full approved school charges. An October 2026 Bayero University announcement described a separate process for submitting evidence of previous payments to its NELFUND desk.
These are institution-specific examples, not a universal automatic-refund promise. Keep your student payment receipt, loan reference and the school's payment confirmation. Ask the bursary whether the amount will be refunded or reconciled, what documents are needed and when to follow up. Never pay an unofficial intermediary to “release” a refund.
7. What if the amount paid to your institution is wrong?
An approved loan entry and a corrected student account balance may not update at precisely the same time. Discrepancies can include an outdated fee schedule, wrong level or programme, duplicate postings, or a payment that the institution has not yet matched to the correct matriculation number.
The Federal Ministry of Information's 2025 NELFUND reforms announcement called for clearer fee nomenclature, verification processes and refund arrangements. For a 2026/2027 example, Emmanuel Alayande University of Education acknowledged discrepancies in the amounts reflected in applicants' records while its loan desk pursued corrections.
When a figure looks incorrect, compare the NELFUND dashboard, current school fee schedule and institutional student account. Record the exact variance and contact your school's authorised NELFUND or bursary office. Do not change personal identifiers, start duplicate applications or press a dispute control against your institution's explicit current directions.
8. Why upkeep may be late even when institutional fees are approved
Students often treat the two loan components as a single transfer. But different verification, payment and institutional reconciliation stages may mean that one component has been recorded while the other remains pending. A loan application can also encounter problems with outdated academic-session data, incorrectly entered bank-account information or incomplete verification.
NELFUND's clarification reported by the NUC identifies incomplete documents, mismatched names, incorrect account details and missing institutional verification among reasons that applications can be rejected. It says rejection reasons should appear on the applicant's dashboard.
First confirm the portal status for each component and the academic session. If the school-fee payment is complete but upkeep is pending, contact official NELFUND support with your application reference; where the problem concerns enrolment data or a bank detail, contact the responsible institution or bank. FlyingEze has reported on student complaints about NELFUND disbursement delays , underlining the need to rely on actual transaction records rather than rumours.
9. Are institutional charges and upkeep loans both repayable?
Yes. The public NELFUND loan terms state that a borrower remains personally responsible for sums paid to the educational institution on their behalf and for sums paid as upkeep. The scheme describes the loans as interest-free, but “interest-free” does not mean that the principal is waived.
Those published terms describe repayment obligations connected to NYSC and employment, including a provision stating that a participant who serves in NYSC begins repayment two years after completing the programme and a 10% salary deduction when employed. They also describe disclosure obligations for self-employed borrowers and the ability to repay early. These provisions are significant enough to read in full rather than relying on simplified social-media explanations.
The publicly posted terms also contain a reference to the 2023 Act despite the Students Loans (Access to Higher Education) Act, 2024 being the later framework described on NELFUND's website. Therefore, applicants should review the actual binding loan agreement presented to them and seek clarification on inconsistencies rather than assuming a short article overrides current legal documents.
10. How to manage the two components responsibly
Maintain a simple record of what you requested, what was approved, what was actually paid and who received it. A student does not need advanced accounting software: a spreadsheet or notebook is enough to reconcile loan statements with school receipts and bank alerts.
| Record | What to save | Why |
|---|---|---|
| Loan application | Application/reference ID, selected session and components requested | Establishes the request being reviewed |
| Institutional-charge approval | Approved amount and school/department details | Helps identify mismatched fees |
| School payment | School account statement, acknowledgement or bursary confirmation | Shows whether the institutional charge was settled |
| Upkeep payments | Bank credits, amounts and months received | Allows accurate personal budgeting and reconciliation |
| Corrections or refunds | Payment receipts, dispute/ticket numbers and official replies | Provides evidence for follow-up |
Keep your login credentials private and do not share your full BVN, NIN, bank statement or one-time verification codes in public groups. If an agent demands an advance “release fee” to activate your institutional or upkeep loan, verify the claim through the official NELFUND site ; do not pay on the strength of a WhatsApp message.
For upkeep budgeting, prioritise recurring essentials such as meals, local transport and course materials. Since instalments can be delayed or stop at the end of the school's academic session, avoid treating the loan as guaranteed income in months when no payment has been approved.
NELFUND 2026/2027: checklist before accepting both loan components
- Confirm you qualify for the current session and that your institution has uploaded valid enrolment records.
- Verify the official institutional charges for your course, level and academic session.
- Review whether the upkeep option is offered and whether you wish to request it.
- Check the latest officially confirmed upkeep amount, rather than relying on social-media claims of an increase.
- Confirm the correct bank account for upkeep and accurate identity information.
- Understand that academic-session dates affect eligibility and disbursement months.
- Keep school-fee receipts if you already paid, and ask about any school-specific refund process.
- Read the current loan agreement carefully: both components create repayment obligations.
- Submit and track your request only through official NELFUND channels.
Frequently asked questions
Does the ₦20,000 NELFUND upkeep payment cover school fees?
No. The ₦20,000 monthly amount confirmed in March 2026 was for upkeep. Approved institutional charges are a separate loan component paid directly to the school. Check any subsequent official revision to the upkeep rate.
Will NELFUND pay institutional fees into my personal bank account?
Ordinarily no. NELFUND's official description says the institutional-charge component goes to the institution, while approved upkeep is paid to the student bank account supplied in the application.
Can I request school fees without upkeep?
NELFUND's public loan terms and 2025 clarification allow the institutional-charge component without upkeep. Check the options available to your own application and session.
Is upkeep paid for twelve months every year?
Not automatically. NELFUND has tied upkeep to the relevant academic session; payments may stop when that session ends, and a new session may require another application.
What should I do if I paid my school fees and NELFUND paid the school too?
Keep your receipts and approach your institution's bursary or NELFUND desk for its official refund or reconciliation process. Procedures vary between schools and a refund should not be assumed until it has been confirmed.
Does an interest-free NELFUND loan have to be repaid?
Yes. Interest-free means the scheme does not charge interest under its stated terms; it does not mean that institutional fees or upkeep become grants. Read the binding loan agreement before accepting.
What if upkeep was approved but I have not received the bank credit?
Check the application dashboard, eligible session and account information, then use the official support channel. Keep the application reference and do not submit altered duplicate applications to bypass verification.
Conclusion
The distinction between NELFUND institutional charges and upkeep loans is straightforward but financially important: the school receives approved institutional charges, while the student receives approved living-cost support. Neither payment automatically proves the other has been completed, and both form part of the borrower's repayable loan obligation.
For the 2026/2027 session, verify school fees, check your own approved upkeep period, track each disbursement independently and retain proof of any personal payments or refunds. Applying with accurate information—and understanding what you are borrowing—will help you make better decisions throughout your studies.