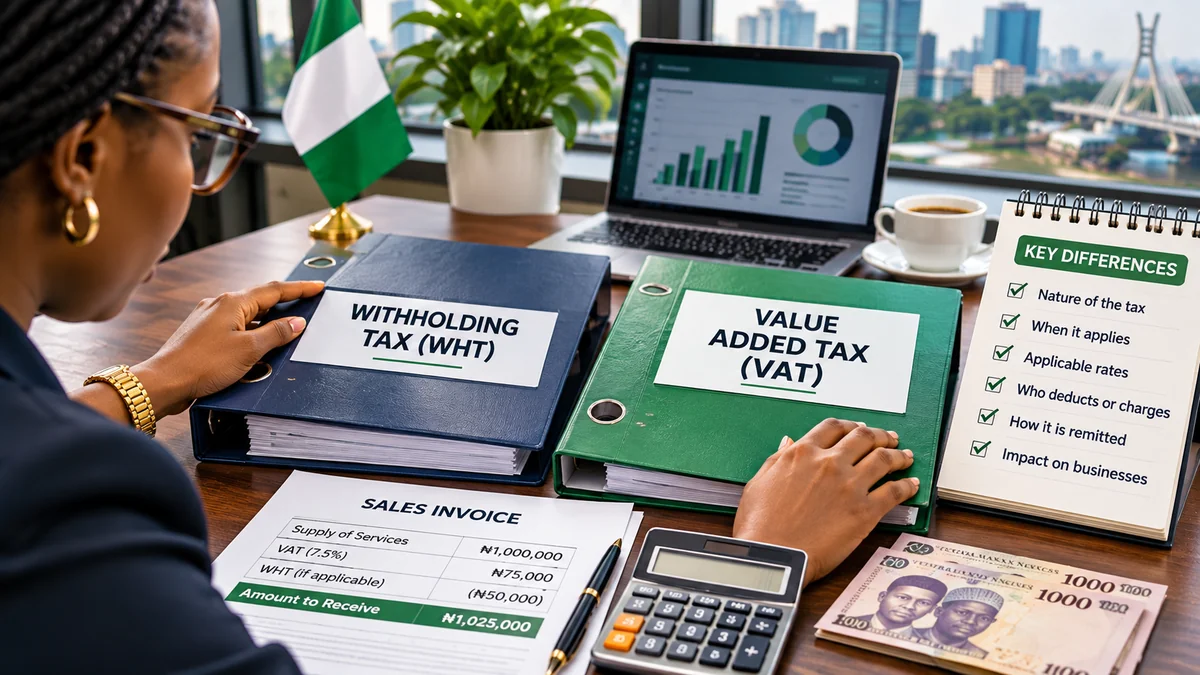
Withholding tax (WHT) and value-added tax (VAT) are different taxes in Nigeria, even when both appear on the same invoice. WHT is a deduction from specified income payments, often credited against the recipient's income-tax liability. VAT is a consumption tax charged on taxable goods and services. In 2026, Nigeria's standard VAT rate is 7.5%; withholding-tax rates differ by transaction and recipient, commonly including 2%, 5% and 10% for resident payments.
For example, suppose a Nigerian consultant issues a qualifying professional-services invoice for ₦1,000,000 before VAT. If VAT applies at 7.5%, the invoice shows an additional ₦75,000. If the client must deduct 5% WHT, it withholds ₦50,000 from the service fee—not from the VAT amount. Subject to any separate VAT-withholding obligation, the amount transferred to the consultant is ₦1,025,000. The two tax entries serve different purposes and should be accounted for separately.
This guide explains the difference, who pays or remits each tax, how invoices and credits work, what changed under Nigeria's 2026 tax framework, and the most common mistakes to avoid. It is general information, not advice on a specific transaction.
Withholding tax vs VAT in Nigeria: the differences at a glance
| Question | Withholding tax (WHT) | Value-added tax (VAT) |
|---|---|---|
| What is it? | Tax deducted at source from specified income payments; generally an income-tax advance or final tax | Consumption tax on taxable supplies of goods or services |
| Typical rate in 2026 | Depends on transaction and recipient; examples include 2%, 5% and 10% | Standard 7.5%; zero-rated and exempt supplies exist |
| How is it applied? | Usually deducted from the supplier's qualifying fee | Usually added to the price of a taxable supply |
| Who accounts for it? | The person or organisation legally required to deduct and remit | Normally the VAT-registered taxable supplier; certain customers must withhold or self-account |
| Where does it go? | NRS or the relevant state revenue service, depending on payee and transaction | Nigeria Revenue Service (NRS) |
| Can it be credited? | Creditable WHT offsets the recipient's income-tax assessment; some WHT is final | Eligible input VAT offsets output VAT; it cannot be used to settle income tax merely because it was paid |
| Key documents | Invoice, WHT calculation and withholding receipt/credit statement | Proper VAT invoice, input/output VAT register and VAT returns |
The official Lagos State Internal Revenue Service withholding-tax FAQ makes the central distinction explicit: WHT is generally an advance income-tax payment, whereas VAT is a consumption tax and cannot simply be offset against an income-tax bill.
What is withholding tax?
Withholding tax is a method of collecting tax before income reaches the recipient. A person required by law to deduct WHT retains the applicable percentage from a qualifying payment and remits it to the appropriate authority on behalf of the supplier, consultant or other beneficiary.
Under the Deduction of Tax at Source (Withholding) Regulations, 2024 , which began applying in January 2025, the rate depends on the payment. For instance, qualifying resident consultancy and professional fees generally carry 5%, ordinary qualifying supplies by a non-manufacturer generally carry 2%, and rent generally carries 10%.
WHT is normally not an extra charge on top of the contract price. It is part of the supplier's income that the payer diverts to the tax authority. For many resident businesses, the deduction becomes a credit against later income-tax liability. In prescribed cases it is a final tax, particularly for some non-resident or passive-income payments.
What is value-added tax?
VAT is a tax on the consumption of taxable goods and services. A supplier that is required to charge VAT adds it to the taxable selling price, collects it from the customer and accounts for it to the NRS. It is commonly borne by the final consumer, while registered businesses may recover eligible VAT paid on purchases through the input-tax credit mechanism.
Section 147 of the Nigeria Tax Act, 2025 fixes the standard VAT rate at 7.5%. The new Act and the Nigeria Tax Administration Act, 2025 took effect on 1 January 2026 and replaced the former VAT Act framework. Despite earlier proposals and rumours, the standard rate has not increased to 10% or 12.5% in 2026.
Not all supplies are standard-rated. Some are zero-rated, so the applicable VAT rate is 0%, and others are exempt. The difference matters for input-VAT recovery and for how the supplier reports transactions.
Why WHT reduces a payment while VAT usually increases an invoice
The easiest way to understand the difference is to look at each tax's direction:
- VAT: a registered supplier generally adds 7.5% to the price of a standard-rated supply and records the amount as output VAT.
- WHT: a customer who is required to deduct WHT generally subtracts the applicable tax from the qualifying fee and remits that deduction on behalf of the supplier.
One transaction may contain both entries. That does not automatically mean the business is being taxed twice on the same basis: the VAT addresses consumption, while WHT is connected to income-tax collection. Nor does deducting WHT cancel the requirement to account for VAT.
Worked example: WHT and VAT on the same ₦1 million invoice
Consider a resident Nigerian consultancy supplying an ordinary standard-rated professional service to a company legally required to deduct WHT. Assume the consulting fee is ₦1,000,000 before VAT, the applicable WHT rate is 5%, and the customer is not separately required to withhold VAT.
| Invoice or deduction line | Calculation | Amount |
|---|---|---|
| Consultancy fee | Agreed fee excluding VAT | ₦1,000,000 |
| Output VAT | 7.5% × ₦1,000,000 | +₦75,000 |
| Invoice total | Fee + VAT | ₦1,075,000 |
| Withholding tax | 5% × ₦1,000,000 | −₦50,000 |
| Amount transferred | Invoice total − WHT | ₦1,025,000 |
The supplier records the full ₦1,000,000 as revenue, not ₦1,025,000. It recognises ₦75,000 as output VAT rather than sales revenue, and records the ₦50,000 withheld as a tax credit or tax paid at source where applicable. The customer accounts for the ₦50,000 WHT remittance and receives the appropriate documentation.
Do not charge WHT on the VAT line. When VAT is properly separated from the underlying fee, the ordinary WHT calculation uses the qualifying payment value excluding VAT. A different treatment may be needed for complicated or improperly drafted contracts, so obtain advice before making unusual adjustments.
What if the customer must withhold VAT as well?
The expression withholding VAT can be confusing because it sounds like withholding tax. They are not the same mechanism.
Section 154 of the Nigeria Tax Act requires federal, state and local government bodies and other persons appointed by the NRS to collect or withhold VAT on specified purchases and remit it to the Service. Section 150 also addresses VAT on taxable supplies made into Nigeria by non-residents, including cases where the Nigerian recipient must withhold VAT.
Using the same ₦1,000,000 consultancy example, if the customer is required to withhold both the ₦75,000 VAT and ₦50,000 income-tax WHT, the supplier's cash receipt may instead be ₦950,000. The customer remits each amount under its correct tax regime, and the supplier needs evidence showing which sum was withheld for which purpose.
Do not assume every private customer is an appointed VAT-withholding agent. Also, a direction to self-account for VAT is not identical to ordinary WHT: different conditions, filings and documentation can apply.
What are output VAT and input VAT?
These terms explain why a registered trader does not ordinarily remit all VAT collected without any adjustment.
Output VAT
Output VAT is VAT charged on a business's taxable sales. If a taxable business sells standard-rated products for ₦1,000,000 before VAT, output VAT at 7.5% is ₦75,000.
Input VAT
Input VAT is VAT paid by a taxable person on its purchases. Under section 155 of the 2025 Act, eligible input VAT incurred on goods, services and fixed assets used to make taxable supplies can generally be credited against output VAT, subject to the applicable conditions and apportionment rules.
For example, if the business has ₦75,000 output VAT and ₦30,000 of allowable input VAT, the net VAT liability is ₦45,000. This is a VAT-to-VAT offset. A creditable WHT deduction is different: it is usually applied against the income-tax assessment and cannot simply be inserted as an input-VAT credit.
The 2026 changes expanded input-VAT recovery to qualifying services and fixed assets; businesses making both taxable and exempt supplies must apportion credits where required. Registered businesses should retain compliant invoices and evidence of business use. An excess input VAT amount may be carried forward or refunded under statutory procedures.
VAT zero-rated vs VAT-exempt: why the distinction matters
A zero-rated transaction is still within the VAT system but carries a 0% rate. An exempt transaction is outside the VAT charge for that supply. These treatments affect the supplier's entitlement to recover VAT on purchases.
| VAT category | Customer VAT | Typical examples |
|---|---|---|
| Standard-rated | 7.5% | Many ordinary taxable goods and professional services |
| Zero-rated | 0% | Basic food items, educational books and materials, medical services and specified exported services |
| Exempt | No VAT charged | Specified land/building interests, baby products and certain public passenger road-transport supplies |
Sections 185 and 186 of the Nigeria Tax Act, 2025 set out categories; exclusions and definitions must be checked. A business making taxable zero-rated supplies may be able to recover associated eligible input VAT, while purchases relating solely to exempt outputs generally do not receive the same credit treatment. This distinction is particularly important for hospitals, exporters, educational businesses and property-related transactions.
Do small businesses have to charge VAT or deduct WHT?
These are two separate questions. Section 22 of the Nigeria Tax Administration Act provides an exemption from routine monthly VAT filing for a qualifying small business, with an option to elect into VAT registration, charging and returns by written notice to the NRS. A business that ceases to qualify must begin complying with the applicable monthly return obligations. Businesses providing professional services do not automatically qualify for every small-business concession.
The 2024 WHT Regulations contain a different conditional small-payer relief for certain payments where the supplier has a valid tax ID and the monthly transaction ceiling is met. Eligibility for one relief does not establish eligibility for the other. Before issuing a VAT invoice or omitting WHT deduction, confirm the entity's current status and the relevant statutory definition.
For a broader overview of the responsibilities attached to business structure, see FlyingEze's comparison of freelancer and registered-company tax responsibilities in Nigeria .
Where are WHT and VAT remitted, and when?
The Nigeria Revenue Service generally administers VAT. Ordinary WHT may be due to the NRS or the state internal revenue service, depending on the recipient's status. LIRS states that WHT deducted from resident individuals and business names normally goes to the relevant state revenue authority, while WHT on company or non-resident payments ordinarily goes to the NRS.
| Obligation | General deadline |
|---|---|
| Ordinary VAT monthly return and remittance | 21st of the following month (subject to small-business and other special rules) |
| VAT withheld or self-accounted by designated persons under section 154 | 14th of the following month, unless the Service prescribes otherwise |
| WHT remitted to NRS | Generally 21st of the following month |
| Ordinary WHT remitted to a state | Generally 30th of the following month under the 2024 regulations; check current state instructions |
Watch the distinction: a company's ordinary monthly VAT return has a different statutory date from the remittance of VAT withheld by a designated agent. Treating all VAT obligations as due on the 21st can result in a missed 14th-day deadline. Set up separate calendar reminders and verify any NRS administrative direction.
What records are needed for WHT and VAT?
Each tax requires its own audit trail. Section 152 of the Nigeria Tax Act calls for a sequentially numbered VAT invoice containing details such as the supplier's tax ID, business name and address, registration number where applicable, supply date, buyer's name, gross amount and VAT rate and amount.
For WHT, preserve the contract, underlying gross invoice, payment confirmation, deduction calculation, evidence of remittance and the WHT receipt or credit statement provided to the beneficiary. Record the payee's identity and tax ID, the type of transaction, period and amount deducted.
A straightforward bookkeeping setup should use separate accounts for sales revenue, output VAT, input VAT, WHT receivable and WHT payable. Without this separation, a business can understate revenue, overstate tax expense or mistakenly apply an income-tax credit to its VAT liability.
For record-keeping practices, read how freelancers keep records for income-tax compliance and five common tax record-keeping mistakes .
Common WHT and VAT mistakes to avoid
- Calling both amounts “tax deducted”. VAT is generally added to the invoice; WHT generally reduces the supplier's net fee. Special VAT-withholding cases must be recorded separately.
- Using 7.5% as a WHT rate. The standard VAT rate is 7.5%; income WHT rates depend on the payment category.
- Deducting WHT from VAT itself. Start with the qualifying underlying supply value when the VAT amount is separately identified.
- Treating WHT as an input-VAT credit. WHT credits and VAT input credits belong to different tax calculations.
- Applying VAT to all goods and services. Zero-rated supplies, exemptions and qualified small-business treatment must be assessed.
- Assuming all VAT is due on the 21st. Statutory VAT-withholding agents may face the earlier 14th-day remittance deadline.
- Using one tax account and no supporting receipts. Reconcile the invoice, payment, WHT credit note and VAT return separately.
Frequently asked questions
Is withholding tax the same as VAT in Nigeria?
No. Withholding tax is normally a method of collecting income tax from specified payments; VAT is a separate consumption tax on taxable goods and services.
Can VAT and WHT be charged on the same invoice?
Yes. A standard-rated consultancy invoice may include 7.5% VAT while the customer deducts an applicable WHT percentage from the underlying service fee.
Is Nigeria's VAT rate still 7.5% in 2026?
Yes. The standard statutory rate is 7.5% under section 147 of the Nigeria Tax Act, 2025; some supplies are zero-rated or exempt.
Can withholding-tax credits reduce a VAT bill?
Not simply because the taxpayer has a WHT credit. Creditable WHT generally offsets assessed income tax. Eligible input VAT offsets output VAT under the VAT rules.
What is the difference between withholding VAT and withholding tax?
Withholding VAT means an authorised customer or agent remits VAT on a taxable supply directly to the NRS. Withholding tax, ordinarily abbreviated WHT, refers to tax deducted from specified income payments and administered under the income-tax withholding rules.
Conclusion
The essential difference between withholding tax and VAT in Nigeria is their purpose. Withholding tax commonly collects income tax early by subtracting part of a qualifying payment; VAT taxes consumption and is usually added to the selling price at 7.5% for standard-rated supplies. Both may arise from one invoice, but each has separate credits, records, deadlines and compliance duties.
Businesses should classify the transaction before calculating either amount, verify whether any VAT or WHT exemption applies, and distinguish between ordinary VAT collection and VAT withheld by designated agents. Accurate invoices and a separate ledger for each tax are the simplest ways to avoid costly mistakes.
Last fact-checked: 18 November 2026. Based on the Nigeria Tax Act, 2025, Nigeria Tax Administration Act, 2025, Deduction of Tax at Source (Withholding) Regulations, 2024, and current LIRS guidance. Verify subsequent official circulars before relying on any deadline or concession for a live transaction.